Table of Contents
- Alphabet Q3 2026 Earnings: Revenue Growth and Financial Performance
- Alphabet Revenue Breakdown: Google Services, Search and Advertising
- Google Cloud Earnings: AI Infrastructure and Enterprise Demand
- Alphabet AI Investment, Cash Flow and Financial Considerations
- Microsoft Q1 FY2027 Earnings: Revenue and Profitability
- Azure Earnings: Cloud Growth and AI Infrastructure
- Microsoft Business Segments and Revenue Diversification
- Microsoft Capital Expenditure, Cash Flow and Shareholder Returns
- Alphabet and Microsoft Earnings: Key Financial Data Tables
- Alphabet and Microsoft: Separate Business Outlooks
- Alphabet and Microsoft Earnings: Closing Financial Assessment
Alphabet Microsoft earnings provide an important view of how two major technology companies are monetizing artificial intelligence, expanding cloud infrastructure, and managing the financial requirements of large-scale technology investment. Alphabet reported third-quarter 2026 results for the period ended September 30, while Microsoft announced its first-quarter fiscal 2027 results for the same period.
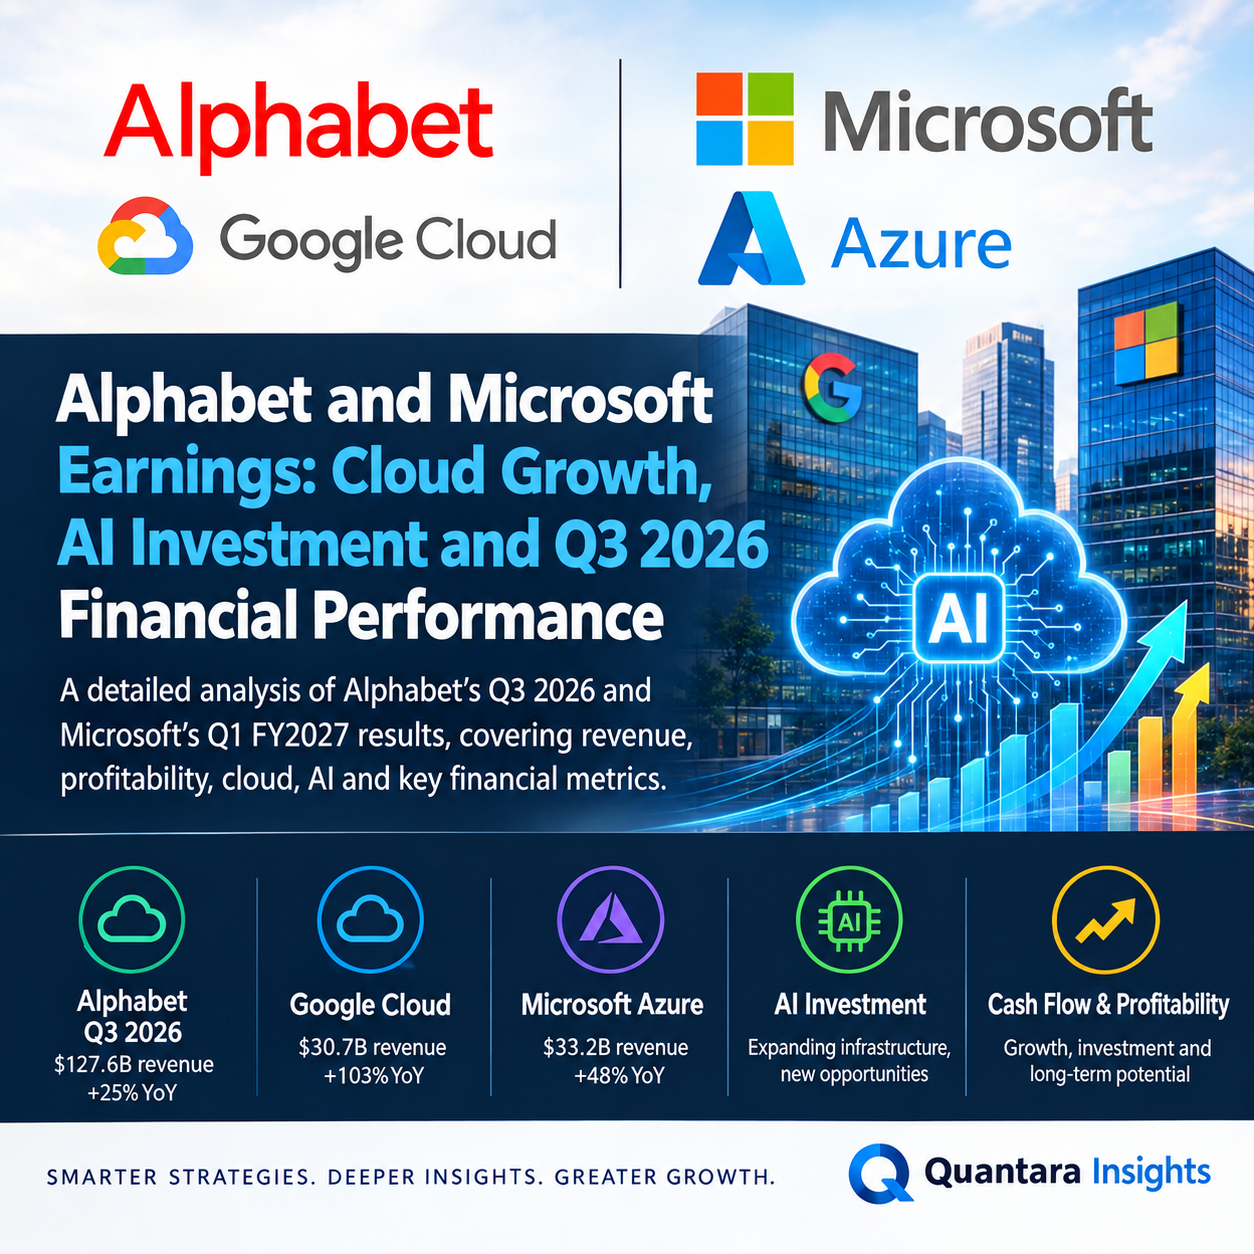
Alphabet recorded revenue of $127.6 billion, representing year-over-year growth of 25%. Google Cloud revenue increased 103% to $30.7 billion, while Google Services revenue advanced 11% to $96.3 billion. Operating income increased 30% to $40.6 billion, although net income available to common stockholders declined to $26.2 billion, reflecting a substantial change in investment-related gains and losses.
Microsoft reported revenue of $92.3 billion, an increase of 19%. Operating income reached $45.9 billion, up 21%, while GAAP net income increased 32% to $36.6 billion. Microsoft Cloud revenue reached $63.9 billion, growing 30%, and Azure revenue increased 48%.
The results highlight the continued importance of cloud computing, enterprise AI infrastructure, subscription-based services, and advertising to both companies. They also demonstrate that revenue growth and reported earnings can be influenced by different factors, including investment-related accounting adjustments, infrastructure spending, and operating costs.
This analysis examines Alphabet and Microsoft independently, covering their quarterly financial results, business segments, cloud operations, AI investment, profitability, cash flow, and capital allocation.
Alphabet Q3 2026 Earnings: Revenue Growth and Financial Performance
Alphabet’s third-quarter 2026 earnings demonstrated continued growth across its major business segments. Revenue increased at a faster rate than in the prior-year quarter, with Google Cloud recording particularly strong expansion.
The company reported its 13th consecutive quarter of double-digit revenue growth, supported by Google Search, advertising, subscriptions, enterprise cloud services, and AI-related infrastructure demand.
Alphabet’s results also reflected the growing financial significance of its AI strategy. The company is investing in infrastructure, proprietary technology, and AI services while continuing to generate substantial revenue from its established advertising and consumer businesses.
Alphabet Q3 2026 Financial Highlights
Alphabet’s consolidated financial results for the quarter ended September 30, 2026, are summarized below.
| Financial metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | $102.35B | $127.58B | +25% |
| Operating income | $31.23B | $40.58B | +30% |
| Operating margin | 30.5% | 31.8% | +1.3 percentage points |
| Net income | $34.98B | $26.47B | -24% |
| Net income available to common stockholders | $34.98B | $26.17B | -25% |
| Diluted earnings per share | $2.87 | $2.12 | -26% |
Figures are rounded. Operating margin is calculated using reported operating income and revenue.
Alphabet’s revenue growth was accompanied by an increase in operating income. This indicates that the company’s core operating activities generated higher profits while expanding its revenue base.
However, net income declined despite the improvement in operating performance. The primary factor was a substantial reversal in other income and expense, particularly gains and losses associated with equity securities.
In the prior-year quarter, Alphabet recorded $12.8 billion in other income. In Q3 2026, the company reported $8.2 billion in other expense.
This change demonstrates why Alphabet earnings should be examined through both operating and non-operating financial measures.
Revenue, operating income, and operating margin provide information about the performance of the company’s business operations. Net income and diluted earnings per share also incorporate investment-related gains and losses, interest expense, and income taxes.
For investors and financial analysts, the distinction is important. Alphabet’s operating performance strengthened during the quarter, even though reported net income declined.
Alphabet Revenue Growth and Operating Performance
Alphabet generated $127.6 billion in quarterly revenue, compared with $102.3 billion in the third quarter of 2025.
The $25.2 billion increase represents substantial growth across the company’s operations. Google Services remained the largest contributor to consolidated revenue, while Google Cloud accounted for an increasingly significant share of the business.
The company’s revenue structure continues to include several major categories:
- Google Search and other advertising.
- YouTube advertising.
- Google Network advertising.
- Google subscriptions, platforms, and devices.
- Google Cloud infrastructure and enterprise services.
- Other Bets.
This diversification allows Alphabet to generate revenue from advertising, consumer subscriptions, enterprise infrastructure, and technology products.
Google Services remains the company’s principal revenue source. Its business includes Search, YouTube, Android, Chrome, Google Maps, Google Play, consumer devices, and subscription-based products.
Google Cloud serves enterprise customers through infrastructure, platform services, productivity applications, and other enterprise offerings.
Other Bets includes several businesses that are not individually material to Alphabet’s consolidated results.
The combination of these operations allows Alphabet to maintain a large advertising business while expanding its enterprise technology operations.
Alphabet Operating Margin and Profitability
Alphabet’s operating income increased from $31.2 billion to $40.6 billion.
The operating margin increased from approximately 30.5% to 31.8%, indicating that the company generated a larger amount of operating income for each dollar of revenue.
The improvement in operating margin is significant because Alphabet’s revenue growth occurred alongside higher research and development expenditure, infrastructure costs, and other operating expenses.
Research and development expenditure increased from $15.2 billion to $20.6 billion during the quarter.
The increase reflects the financial importance of ongoing technology development, including AI-related research and infrastructure.
Alphabet’s operating performance also benefited from Google Cloud’s expansion. Google Cloud’s operating income increased substantially, helping improve the company’s consolidated operating results.
The company’s financial performance therefore reflects two important developments: continued growth in its established Google Services operations and an expanding contribution from Google Cloud.
Alphabet Net Income and Earnings Per Share
Alphabet reported net income of $26.5 billion for Q3 2026, compared with $35.0 billion in the prior-year quarter.
Net income available to common stockholders was $26.2 billion, while diluted earnings per share declined from $2.87 to $2.12.
The decline in net income was not primarily caused by weaker operating income. Instead, it reflected a significant change in other income and expense.
Alphabet reported a net loss of $8.2 billion in other income and expense during Q3 2026. The corresponding figure in Q3 2025 was positive $12.8 billion.
The company’s earnings release identified an $8.7 billion net loss on equity securities during the quarter. This loss reduced net income and diluted earnings per share.
The impact of investment-related volatility can be substantial for companies with significant investment portfolios.
For this reason, Alphabet’s earnings should be considered through several measures rather than relying on net income or EPS alone.
The company’s revenue, operating income, operating margin, and segment profitability provide additional information about its underlying business performance.
Alphabet Financial Position and Capital Allocation
Alphabet’s balance sheet reported total assets of approximately $1.0 trillion at September 30, 2026.
Cash, cash equivalents, and marketable securities totaled $265.1 billion. Long-term debt was $125.1 billion, while total liabilities were $325.8 billion.
The company’s balance sheet also reflected substantial investment in property and equipment.
Property and equipment, net, increased from $246.6 billion at December 31, 2025, to $372.8 billion at September 30, 2026.
The increase highlights the scale of Alphabet’s infrastructure investment.
Alphabet also reported the issuance of senior unsecured notes during the quarter, generating net proceeds of $28.7 billion for general corporate purposes.
The company’s capital allocation includes infrastructure investment, research and development, shareholder dividends, and other corporate activities.
The financial position provides an important context for evaluating Alphabet’s ongoing AI and cloud investment strategy.
Alphabet Revenue Breakdown: Google Services, Search and Advertising
Alphabet’s revenue composition remains heavily influenced by advertising, particularly Google Search and YouTube. These businesses provide a substantial revenue base that supports investment in cloud infrastructure, AI research, and consumer technology products.
Google Services generated $96.3 billion in revenue during Q3 2026, compared with $87.1 billion in the prior-year quarter. The increase was supported by growth in Search, YouTube advertising, and subscription-based products.
The Google Services segment includes several different revenue streams. Advertising remains the largest contributor, but subscriptions, platforms, and devices are becoming increasingly important.
Google Search and Other Advertising Revenue
Google Search and other revenue increased from $56.6 billion in Q3 2025 to $63.4 billion in Q3 2026.
The 12% year-over-year increase was supported by continued demand for Search advertising and growth in search activity.
Alphabet reported that its year-over-year Search query growth rate was the highest it had been in five years. The company also indicated that commercial queries were growing, suggesting continued activity in searches associated with products, services, and purchasing decisions.
Search remains a central component of Alphabet’s advertising business.
The company’s advertising model allows businesses to reach users based on their search activity and commercial intent. This provides advertisers with an established channel for reaching potential customers.
The growth in Search revenue indicates that Alphabet continues to generate substantial advertising revenue while expanding its AI capabilities.
AI-related changes to Search may influence how users interact with the platform, how results are presented, and how advertising is delivered.
However, the third-quarter results demonstrate that Search remained an important source of revenue growth during the reporting period.
YouTube Advertising Revenue
YouTube advertising revenue increased from $10.3 billion to $11.2 billion.
The increase represents approximately 9% year-over-year growth.
YouTube continues to generate revenue through advertising, subscriptions, and other consumer services. The platform benefits from a broad range of content categories, including entertainment, education, music, sports, and professional content.
The advertising business is supported by demand from businesses seeking to reach audiences through video.
YouTube also contributes to Alphabet’s subscription revenue through services such as YouTube Music and YouTube Premium.
Alphabet reported that YouTube Music and Premium surpassed 150 million subscribers globally, including trials.
This subscription base provides an additional revenue stream beyond advertising.
The combination of advertising and subscription revenue allows YouTube to monetize user engagement through multiple channels.
Google Network Advertising Revenue
Google Network revenue increased from $7.35 billion to $7.46 billion.
The increase was comparatively modest, representing approximately 1% year-over-year growth.
Google Network includes advertising revenue generated through partner websites and other network properties.
The performance of this business is important because it provides information about advertising activity beyond Google’s owned platforms.
While Search and YouTube recorded stronger growth, Google Network revenue remained relatively stable.
The difference in growth rates across Alphabet’s advertising businesses demonstrates the importance of examining individual revenue categories rather than relying exclusively on consolidated advertising figures.
Google Subscriptions, Platforms and Devices
Google subscriptions, platforms, and devices revenue increased from $12.87 billion to $14.29 billion.
The increase represents approximately 11% growth.
This category includes consumer subscription services, applications, devices, and other products.
Subscription revenue can provide a recurring source of income, while device sales contribute to Alphabet’s broader consumer technology business.
The growth in this category reflects the continued expansion of Alphabet’s consumer services beyond advertising.
Products such as Google One, YouTube Music, YouTube Premium, and other subscription offerings allow the company to generate revenue from users directly.
The financial contribution of these services is particularly relevant as Alphabet continues to develop its AI products and integrate AI capabilities into its consumer ecosystem.
Alphabet Google Services Revenue Table
The following table provides a detailed breakdown of Alphabet’s major Google Services revenue categories.
| Revenue category | Q3 2025 | Q3 2026 | Approx. growth |
|---|---|---|---|
| Google Search and other | $56.57B | $63.35B | 12% |
| YouTube advertising | $10.26B | $11.21B | 9% |
| Google Network | $7.35B | $7.46B | 1% |
| Google advertising | $74.18B | $82.01B | 11% |
| Subscriptions, platforms, and devices | $12.87B | $14.29B | 11% |
| Google Services total | $87.05B | $96.30B | 11% |
Source figures are from Alphabet’s Q3 2026 earnings release. Growth percentages are rounded.
The table demonstrates that Google Search and other advertising remained Alphabet’s largest individual revenue category.
Google Services generated approximately three-quarters of Alphabet’s consolidated revenue during the quarter.
This concentration in Google Services provides Alphabet with a substantial revenue base, although it also means that advertising performance remains an important factor in the company’s overall financial results.
The expansion of Google Cloud provides an additional source of growth and reduces the relative concentration of Alphabet’s revenue in advertising.
Google Cloud Earnings: AI Infrastructure and Enterprise Demand
Google Cloud was one of the most significant contributors to Alphabet’s Q3 2026 financial performance.
Revenue increased from $15.2 billion to $30.7 billion, representing year-over-year growth of 103%.
The increase reflects demand for enterprise cloud infrastructure, AI-related services, Google Cloud Platform, and TPU systems.
Google Cloud’s performance is important because it demonstrates how Alphabet is expanding its enterprise technology business while continuing to operate a large consumer advertising platform.
The company reported record growth in Google Cloud revenue during the quarter.
Google Cloud Revenue Growth
Google Cloud revenue reached $30.7 billion in Q3 2026.
The segment’s revenue increased by approximately $15.6 billion compared with the prior-year quarter.
This growth was substantially higher than Alphabet’s consolidated revenue growth of 25%.
The difference demonstrates the increasing contribution of enterprise cloud services to Alphabet’s overall business.
Google Cloud generates revenue through consumption-based infrastructure services, platform offerings, subscriptions, enterprise applications, and other products.
Its customer base includes businesses using cloud infrastructure for data storage, computing, application development, AI workloads, and enterprise software.
As companies increase their use of AI, demand for computing infrastructure and cloud services can expand.
Google Cloud’s third-quarter results reflect this demand.
Google Cloud Platform and Enterprise AI Solutions
Google Cloud Platform provides infrastructure and platform services for enterprise customers.
Businesses can use these services to develop, deploy, and operate applications without having to build and manage all their own computing infrastructure.
Google Cloud also offers AI-related services that support enterprise development and deployment of AI applications.
These offerings are relevant to companies seeking to incorporate AI into business operations, customer services, analytics, and software development.
The financial contribution of these services can come from infrastructure consumption, enterprise subscriptions, and other cloud-related revenue.
Google Cloud’s 103% revenue growth suggests that enterprise demand has become a significant contributor to Alphabet’s financial performance.
However, revenue growth alone does not provide a complete view of the business.
Operating income and operating margin are also important because cloud infrastructure requires substantial investment in computing equipment, data centers, networking, and energy.
TPU Systems and AI Infrastructure
Alphabet’s earnings release identified TPU systems sales as a meaningful contributor to Google Cloud revenue growth.
TPUs are specialized processors designed for AI-related computing workloads.
Alphabet’s ability to develop and provide its own AI infrastructure is relevant to its enterprise cloud strategy.
The company can offer customers computing resources and AI-related services through Google Cloud while also using its own infrastructure to support internal AI development.
The earnings release indicated that demand for TPU systems was strong across a wide range of customers.
This demand contributes to Google Cloud’s revenue, while also supporting Alphabet’s broader AI infrastructure strategy.
The financial implications extend beyond hardware sales.
AI infrastructure can support enterprise services, model deployment, application development, and cloud consumption.
As a result, the financial contribution of AI infrastructure can occur through multiple revenue categories.
Google Cloud Operating Income and Profitability
Google Cloud’s operating income increased from $3.6 billion in Q3 2025 to $11.1 billion in Q3 2026.
The increase was substantially higher than the segment’s revenue growth rate in absolute dollar terms.
Google Cloud’s operating margin also improved.
| Google Cloud financial metric | Q3 2025 | Q3 2026 |
|---|---|---|
| Revenue | $15.16B | $30.71B |
| Operating income | $3.59B | $11.12B |
| Operating margin | 23.7% | 36.2% |
| Revenue growth | — | 103% |
Operating margins are calculated from reported segment revenue and operating income.
The improvement in operating margin indicates that Google Cloud generated more operating income from each dollar of revenue.
This is an important development because cloud infrastructure businesses require substantial capital investment and operating expenditure.
Higher revenue can improve profitability when infrastructure capacity is used more efficiently and the business generates additional revenue from existing resources.
Google Cloud’s operating performance therefore provides an important measure of the financial contribution of Alphabet’s enterprise cloud strategy.
The segment’s growth also demonstrates that cloud infrastructure is becoming an increasingly important component of Alphabet’s consolidated earnings.
Google Cloud’s Contribution to Alphabet’s Financial Performance
Google Cloud accounted for approximately 24% of Alphabet’s consolidated revenue during Q3 2026.
Its operating income represented a substantial contribution to Alphabet’s consolidated operating income.
Google Cloud’s operating income increased by approximately $7.5 billion compared with the prior-year quarter.
Alphabet’s consolidated operating income increased by approximately $9.3 billion during the same period.
This relationship demonstrates the importance of Google Cloud’s operating improvement to Alphabet’s overall financial performance.
Google Services remained the largest contributor to revenue and operating income, but Google Cloud’s growth was particularly significant.
The expansion of Google Cloud provides Alphabet with a growing enterprise revenue stream that is less directly dependent on advertising demand.
However, the business remains exposed to infrastructure costs, enterprise spending patterns, competitive pressures, and the financial requirements of AI development.
Alphabet AI Investment, Cash Flow and Financial Considerations
Alphabet’s AI strategy is closely connected to its investment in computing infrastructure, research and development, and enterprise cloud services.
The company is developing AI models, expanding cloud infrastructure, and integrating AI capabilities into consumer and enterprise products.
These activities require significant investment.
The financial results indicate that Alphabet is generating substantial revenue growth from its AI and cloud operations, although the costs associated with infrastructure expansion remain an important consideration.
Gemini Adoption and AI Model Usage
Alphabet reported several AI-related developments during Q3 2026.
The Gemini app reached one billion users, making it the fastest-growing product in Alphabet’s history, according to the company’s earnings release.
Alphabet also reported that its first-party model APIs were processing nearly 32 billion tokens per minute.
This represented more than four times the volume processed a year earlier.
These metrics provide information about the scale of Alphabet’s AI usage.
The growth in AI activity is relevant to the company’s broader business strategy because AI capabilities can be integrated into Search, consumer applications, enterprise services, and cloud infrastructure.
Alphabet’s AI products can generate financial value through several channels:
- Increased engagement with consumer services.
- Enterprise subscriptions and AI applications.
- Cloud infrastructure consumption.
- AI-related hardware and infrastructure sales.
- Advertising-related improvements and commercial search activity.
The financial contribution of these activities may not always be directly identifiable in consolidated revenue.
For example, AI features integrated into Google Search may contribute to the performance of the existing Search advertising business rather than generating a separate revenue category.
Similarly, enterprise AI demand can support Google Cloud revenue through infrastructure consumption and AI-related services.
The growth in AI usage therefore provides context for Alphabet’s financial results, but it should not be treated as a direct measure of AI profitability.
Alphabet Capital Expenditure and Infrastructure Investment
Alphabet’s capital expenditure increased significantly during 2026.
The company’s Q3 2026 cash flow statement reported purchases of property and equipment of $51.4 billion during the quarter.
The corresponding figure for Q3 2025 was $24.0 billion.
The increase reflects the scale of Alphabet’s infrastructure investment.
Capital expenditure includes investment in property and equipment, which can include data centers, computing infrastructure, networking equipment, and other long-lived assets.
These investments support Alphabet’s cloud services, AI model development, Search operations, and other technology businesses.
Capital expenditure is important because it affects cash flow differently from operating expenses.
Operating expenses are generally recognized in the income statement during the relevant period, while capital expenditure is recorded as an investment in assets and affects cash flow when the expenditure occurs.
The financial impact of capital expenditure can therefore extend across several reporting periods.
Alphabet’s infrastructure investment supports its ability to expand capacity, but it also creates a requirement for the company to generate sufficient future revenue and operating cash flow.
Alphabet Operating Cash Flow and Free Cash Flow
Alphabet generated $42.3 billion in operating cash flow during Q3 2026.
Capital expenditure was $51.4 billion.
The difference resulted in negative free cash flow of $9.1 billion.
| Alphabet cash flow metric | Q3 2025 | Q3 2026 |
|---|---|---|
| Operating cash flow | $48.41B | $42.29B |
| Capital expenditure | $23.95B | $51.36B |
| Free cash flow | $24.46B | -$9.07B |
Free cash flow is calculated as operating cash flow less capital expenditure, consistent with Alphabet’s definition.
The decline in free cash flow reflects the increase in infrastructure investment and the reduction in quarterly operating cash flow.
Operating cash flow declined from $48.4 billion to $42.3 billion.
At the same time, capital expenditure increased from approximately $24.0 billion to $51.4 billion.
This combination resulted in a substantial change in free cash flow.
The distinction between operating cash flow and free cash flow is particularly important for technology companies investing heavily in AI infrastructure.
Operating cash flow provides information about the cash generated by business operations.
Free cash flow provides additional information about the cash remaining after capital expenditure.
A company can report higher revenue and operating income while experiencing lower free cash flow if capital expenditure increases substantially.
Alphabet’s Q3 2026 results illustrate this relationship.
Investment-Related Volatility in Alphabet Earnings
Alphabet’s reported net income was influenced by changes in the value of investment securities.
The company reported a net loss of $8.7 billion on equity securities during Q3 2026.
This contributed to the decline in net income compared with the prior-year quarter.
Investment-related gains and losses can create volatility in reported earnings because their value may change due to market conditions and other factors.
These gains and losses are separate from the operating performance of Alphabet’s principal business segments.
For financial analysis, this distinction is relevant when assessing the company’s underlying profitability.
Alphabet’s operating income increased by 30%, while net income available to common stockholders declined by approximately 25%.
The difference demonstrates that operating performance and reported earnings can move in different directions.
It also reinforces the importance of examining operating income, net income, cash flow, and segment profitability together.
Alphabet Financial Considerations
Alphabet’s financial performance includes several areas that warrant continued attention.
First, advertising remains a significant contributor to revenue. Changes in advertising demand, user activity, and commercial search behavior can influence the company’s financial results.
Second, Google Cloud is expanding rapidly, but its infrastructure requirements are substantial.
Third, AI-related investment requires ongoing expenditure on computing capacity, research, and product development.
Fourth, investment-related gains and losses can influence reported net income.
Finally, free cash flow is an important financial measure because it provides information about the cash available after capital expenditure.
These considerations do not negate Alphabet’s revenue and operating income growth. Rather, they provide a broader framework for understanding the company’s financial performance.
Microsoft Q1 FY2027 Earnings: Revenue and Profitability
Microsoft reported its first-quarter fiscal 2027 results for the period ended September 30, 2026.
The company generated $92.3 billion in revenue, representing year-over-year growth of 19%.
Operating income increased 21% to $45.9 billion, while GAAP net income increased 32% to $36.6 billion.
Microsoft’s results were supported by growth in cloud services, enterprise infrastructure, Microsoft 365, and AI-related products.
Microsoft Cloud revenue reached $63.9 billion, increasing 30% year over year.
Azure revenue increased 48%, while commercial remaining performance obligations reached $677 billion.
The results demonstrate continued growth across Microsoft’s enterprise technology operations.
Microsoft Q1 FY2027 Financial Highlights
The following table summarizes Microsoft’s reported financial results.
| Financial metric | Q1 FY2026 | Q1 FY2027 | Growth |
|---|---|---|---|
| Revenue | $77.67B | $92.28B | 19% |
| Operating income | $37.96B | $45.92B | 21% |
| GAAP net income | $27.75B | $36.63B | 32% |
| GAAP diluted EPS | $3.72 | $4.92 | 32% |
| Non-GAAP net income | $30.83B | $36.42B | 18% |
| Non-GAAP diluted EPS | $4.13 | $4.89 | 18% |
| Microsoft Cloud revenue | — | $63.9B | 30% |
| Azure revenue growth | — | — | 48% |
Microsoft’s non-GAAP measures exclude the impact from investments in OpenAI, as described in the company’s earnings release.
Microsoft’s revenue increased by approximately $14.6 billion compared with the prior-year quarter.
Operating income increased by approximately $8.0 billion.
The company’s operating income growth exceeded its revenue growth rate, indicating an improvement in operating profitability.
Microsoft’s GAAP net income increased by 32%, although the comparison was influenced by investment-related accounting adjustments.
The company’s non-GAAP results provide an additional view of performance after adjusting for the impact of investments in OpenAI.
Microsoft Revenue and Operating Income
Microsoft’s revenue reached $92.3 billion during Q1 FY2027.
The company generated revenue through cloud infrastructure, productivity software, enterprise applications, devices, gaming, advertising, and other technology services.
Microsoft’s operating income increased from $38.0 billion to $45.9 billion.
The increase reflects higher revenue and operating performance across the company’s business segments.
Microsoft’s operating margin was approximately 49.7%, compared with 48.9% in the prior-year quarter.
This indicates that the company generated a higher proportion of operating income from each dollar of revenue.
The improvement in operating margin is relevant because Microsoft continues to invest in AI infrastructure and enterprise cloud services.
The company’s financial performance therefore reflects both growth in revenue and the ability to maintain operating profitability while expanding infrastructure capacity.
Microsoft GAAP and Non-GAAP Earnings
Microsoft reported GAAP net income of $36.6 billion and diluted earnings per share of $4.92.
The company’s non-GAAP net income was $36.4 billion, while non-GAAP diluted earnings per share was $4.89.
The non-GAAP results exclude the impact from investments in OpenAI.
Microsoft stated that the impact from these investments increased net income and diluted earnings per share by $207 million and $0.03, respectively, during Q1 FY2027.
In the prior-year quarter, investment-related losses reduced net income by $3.1 billion and diluted earnings per share by $0.41.
The difference in investment-related accounting adjustments influenced the year-over-year growth rates in GAAP earnings.
Microsoft’s GAAP net income increased 32%, while non-GAAP net income increased 18%.
The non-GAAP figures provide an additional perspective on Microsoft’s operating performance by adjusting for the impact of these investment-related items.
However, GAAP results remain the company’s reported financial measures and should be considered alongside the adjusted figures.
Microsoft Cloud Revenue and Commercial Performance
Microsoft Cloud revenue reached $63.9 billion, increasing 30% year over year.
The company reported that growth accelerated to 30%, or 31% on a constant-currency basis.
Microsoft Cloud includes Azure, Microsoft 365 commercial cloud services, and other enterprise cloud offerings.
The company’s enterprise cloud business generates revenue through subscriptions, consumption-based services, software licensing, infrastructure, and other technology offerings.
Microsoft Cloud’s revenue growth reflects continued demand for enterprise technology services.
The company’s cloud infrastructure is also relevant to its AI strategy because AI workloads require computing resources, storage, networking, and software platforms.
The financial performance of Microsoft Cloud therefore provides information about the company’s ability to monetize enterprise demand for cloud and AI services.
Commercial Remaining Performance Obligations
Microsoft reported commercial remaining performance obligations of $677 billion, representing growth of 73%.
Remaining performance obligations provide information about contracted revenue that has not yet been recognized.
This measure can help provide context for future revenue visibility.
However, the timing of revenue recognition depends on contractual terms, service delivery, and other factors.
The increase in commercial remaining performance obligations indicates that Microsoft has a substantial base of contracted commercial business.
The metric is particularly relevant for enterprise cloud services, where customer commitments may extend across multiple years.
It should not be treated as equivalent to immediate revenue or cash flow, but it provides additional information about the company’s commercial activity.
Azure Earnings: Cloud Growth and AI Infrastructure
Azure is a central component of Microsoft’s enterprise cloud business.
Microsoft reported Azure revenue growth of 48% during Q1 FY2027. The growth rate was unchanged on a constant-currency basis.
Azure provides cloud infrastructure and platform services for enterprise customers. These services support application development, data storage, computing, analytics, AI workloads, and other enterprise technology requirements.

Azure’s financial performance is important because it provides information about Microsoft’s ability to generate revenue from enterprise cloud demand.
Azure Revenue Growth
Microsoft reported Azure revenue growth of 48% year over year.
The company’s product and service revenue table reported Azure revenue of $33.2 billion, compared with $22.4 billion in the prior-year quarter.
The reported Azure revenue category increased by approximately $10.8 billion.
| Azure financial metric | Q1 FY2026 | Q1 FY2027 |
|---|---|---|
| Azure revenue | $22.38B | $33.17B |
| Revenue growth | — | 48% |
| Constant-currency growth | — | 48% |
Azure revenue figures are from Microsoft’s product and service offerings revenue table. The reported growth rate is the company’s stated Azure growth metric.
The increase in Azure revenue reflects continued enterprise demand for cloud services.
Azure’s business model includes infrastructure services, platform services, and AI-related offerings.
Enterprise customers can use Azure to operate applications, deploy AI models, manage data, and support business operations.
The financial contribution of Azure can therefore extend across multiple enterprise technology requirements.
Microsoft Cloud and Azure Revenue
Microsoft Cloud revenue reached $63.9 billion during Q1 FY2027.
Azure revenue increased 48%, while Microsoft Cloud revenue increased 30%.
The difference in growth rates reflects the broader composition of Microsoft Cloud.
Microsoft Cloud includes several enterprise services, including Azure and Microsoft 365 commercial cloud.
The company’s cloud revenue therefore reflects a combination of infrastructure consumption, enterprise software subscriptions, and other cloud services.
Azure’s growth rate was higher than Microsoft Cloud’s consolidated growth rate, indicating that Azure was an important contributor to the company’s cloud expansion.
However, Microsoft Cloud revenue and Azure revenue should not be treated as interchangeable measures.
Microsoft Cloud represents a broader category of enterprise cloud services, while Azure is a specific component of Microsoft’s cloud business.
Azure and Microsoft’s Agents and Infra Segment
Microsoft’s Q1 FY2027 results were reported under a revised segment structure.
The company reported two major segments:
- Agents and Infra.
- Devices and Consumer.
Agents and Infra generated $76.8 billion in revenue, representing growth of 25%.
The segment includes Azure, Microsoft 365 commercial cloud, productivity and server licensing, industry solutions, and other enterprise services.
This segment structure reflects Microsoft’s focus on enterprise technology, infrastructure, and AI-related business activity.
Azure’s growth contributes to the overall performance of Agents and Infra.
The segment also includes several established enterprise software businesses that generate recurring revenue.
The combination of infrastructure services and software subscriptions provides Microsoft with multiple sources of enterprise revenue.
Azure Infrastructure Investment
Azure’s expansion requires investment in computing infrastructure.
Microsoft’s Q1 FY2027 cash flow statement reported additions to property and equipment of $39.4 billion.
The corresponding figure for the prior-year quarter was $19.4 billion.
The increase demonstrates the scale of Microsoft’s infrastructure investment.
Capital expenditure supports data centers, computing equipment, networking infrastructure, and other long-lived assets.
These investments are relevant to Azure because cloud services require sufficient infrastructure capacity to support customer demand.
AI workloads can also require substantial computing resources.
Microsoft’s infrastructure investment therefore supports both its existing cloud business and the expansion of AI-related services.
However, capital expenditure also affects cash flow.
The financial contribution of infrastructure investment depends on the company’s ability to generate revenue and operating income from the assets over time.
Azure Profitability and Financial Considerations
Microsoft’s Agents and Infra segment generated operating income of $40.6 billion during Q1 FY2027.
The segment’s operating income increased from $32.7 billion in the prior-year quarter.
The segment’s operating margin was approximately 52.8%.
The result demonstrates that Microsoft’s enterprise technology business generated substantial operating income while expanding revenue.
However, the segment includes multiple businesses, and the company did not separately disclose Azure operating income in the supplied earnings release.
For this reason, Azure’s individual operating margin cannot be calculated directly from the reported figures.
Azure’s revenue growth provides information about demand, while Microsoft’s segment operating income provides broader information about enterprise profitability.
Both measures are relevant to the company’s financial performance.
Microsoft Business Segments and Revenue Diversification
Microsoft’s financial results reflect the performance of several enterprise and consumer businesses.
The company’s revised segment structure provides a clearer view of its enterprise infrastructure operations and consumer technology activities.
Agents and Infra generated the majority of Microsoft’s revenue during Q1 FY2027.
Devices and Consumer generated $15.5 billion, representing a decline of 3%.
The difference in performance demonstrates that Microsoft’s enterprise technology business continued to expand while some consumer-related categories experienced weaker demand.
Agents and Infra Revenue
Agents and Infra generated $76.8 billion in revenue.
The segment’s revenue increased from $61.7 billion in the prior-year quarter.
The 25% growth rate reflects the performance of Azure, Microsoft 365 commercial cloud, productivity and server licensing, industry solutions, and other enterprise services.
The segment’s operating income increased from $32.7 billion to $40.6 billion.
| Agents and Infra financial metric | Q1 FY2026 | Q1 FY2027 |
|---|---|---|
| Revenue | $61.67B | $76.80B |
| Operating income | $32.72B | $40.56B |
| Revenue growth | — | 25% |
| Operating margin | 53.0% | 52.8% |
Operating margins are calculated using reported segment revenue and operating income.
The segment’s revenue growth demonstrates the importance of enterprise cloud and software services to Microsoft’s financial performance.
The slight decline in operating margin indicates that operating income increased broadly in line with revenue.
The result reflects continued profitability alongside investment in infrastructure and enterprise technology.
Microsoft 365 Commercial Cloud Revenue
Microsoft 365 commercial cloud revenue increased 18% on an adjusted basis, normalized for a one-percentage-point benefit from in-period revenue recognition in the prior-year period.
The company reported growth of 17% on a reported basis.
Microsoft 365 commercial cloud provides productivity and collaboration services for enterprise customers.
The service generates revenue through subscriptions and related cloud offerings.
The growth in Microsoft 365 commercial cloud provides an additional source of recurring enterprise revenue.
The business also contributes to Microsoft’s broader enterprise cloud strategy.
Microsoft 365 services can be integrated with Azure and other enterprise technology offerings, allowing the company to generate revenue through multiple products and services.
Microsoft 365 Consumer Cloud Revenue
Microsoft 365 consumer cloud revenue increased 17% on a reported basis.
The company’s constant-currency growth rate was 16%.
Consumer cloud services provide subscription-based revenue from individual users and households.
The growth in this category demonstrates continued demand for Microsoft’s consumer productivity and cloud services.
Subscription-based revenue can provide a recurring source of income, although growth depends on customer retention, pricing, product adoption, and other factors.
Industry Solutions Cloud Revenue
Microsoft’s industry solutions cloud revenue increased 10%.
The category includes cloud services designed for specific industries and business requirements.
Industry solutions can provide enterprise customers with technology that supports business processes, data management, and other operational requirements.
The growth in this category provides an additional source of revenue beyond Azure and Microsoft 365.
Devices and Consumer Revenue
Microsoft’s Devices and Consumer segment generated $15.5 billion in revenue, compared with $16.0 billion in the prior-year quarter.
Revenue declined 3%.
The segment includes Windows OEM and devices, Xbox content and services, Search and advertising, and other consumer-related businesses.
The company’s earnings release reported the following results:
| Revenue category | Q1 FY2026 | Q1 FY2027 | Growth |
|---|---|---|---|
| Search and advertising | $5.94B | $6.55B | 12% |
| Xbox | $5.51B | $5.38B | -2% |
| Windows OEM and devices | $4.55B | $3.55B | -22% |
| Devices and Consumer total | $16.00B | $15.48B | -3% |
Revenue categories are from Microsoft’s product and service offerings table. Xbox content and services growth was reported separately from total Xbox revenue.
The results demonstrate differences in performance across Microsoft’s consumer technology businesses.
Search and advertising revenue increased 12%, while Xbox content and services revenue declined 2%.
Windows OEM and devices revenue declined 22%.
The performance of these categories indicates that Microsoft’s consumer business was affected by different demand conditions across its products and services.
The expansion of enterprise cloud services therefore remained an important contributor to Microsoft’s consolidated revenue growth.
Microsoft Capital Expenditure, Cash Flow and Shareholder Returns
Microsoft’s financial performance should also be evaluated through operating cash flow, capital expenditure, and shareholder returns.
The company generated $58.0 billion in operating cash flow during Q1 FY2027.
Capital expenditure was $39.4 billion, compared with $19.4 billion in the prior-year quarter.
The increase in capital expenditure reflects Microsoft’s investment in infrastructure and enterprise technology.
These investments support Azure, Microsoft Cloud, and AI-related services.
Microsoft Operating Cash Flow
Microsoft’s operating cash flow increased from $45.1 billion to $58.0 billion.
The increase represents approximately 29% growth.
Operating cash flow provides information about the cash generated by the company’s business operations.
Microsoft’s operating cash flow was higher than its reported net income, reflecting non-cash expenses and changes in operating assets and liabilities.
The company’s cash flow performance is important because it provides information about its ability to fund infrastructure investment, dividends, share repurchases, and other corporate activities.
Microsoft Capital Expenditure
Microsoft reported additions to property and equipment of $39.4 billion during Q1 FY2027.
The increase from $19.4 billion in the prior-year quarter reflects the scale of infrastructure investment.
Capital expenditure is relevant to Microsoft’s cloud and AI strategy because enterprise computing services require substantial infrastructure.
However, capital expenditure also reduces the cash available after investment.
The relationship between operating cash flow and capital expenditure is therefore important when evaluating Microsoft’s financial performance.
Microsoft Free Cash Flow
Using operating cash flow less additions to property and equipment, Microsoft’s quarterly free cash flow was approximately $18.6 billion.
| Microsoft cash flow metric | Q1 FY2026 | Q1 FY2027 |
|---|---|---|
| Operating cash flow | $45.06B | $58.00B |
| Capital expenditure | $19.39B | $39.37B |
| Free cash flow | $25.66B | $18.63B |
Free cash flow is calculated as operating cash flow less additions to property and equipment.
Microsoft’s operating cash flow increased, but free cash flow declined because capital expenditure increased substantially.
This demonstrates that operating cash flow and free cash flow can move in different directions.
The increase in infrastructure investment reduced the amount of cash remaining after capital expenditure.
For financial analysis, the distinction is important because infrastructure investment may support future revenue, but it also creates an immediate cash requirement.
Microsoft Shareholder Returns
Microsoft returned $10.2 billion to shareholders through dividends and share repurchases during Q1 FY2027.
The company’s cash flow statement reported:
- $6.8 billion in common stock dividend payments.
- $4.4 billion in common stock repurchases.
These payments demonstrate that Microsoft continued to return capital to shareholders while investing in infrastructure.
The company also reported a substantial operating cash flow base.
Shareholder returns and infrastructure investment are both important components of Microsoft’s capital allocation strategy.
However, the financial impact of these activities should be considered alongside the company’s cash flow requirements.
Alphabet and Microsoft Earnings: Key Financial Data Tables
The following tables summarize the financial results of Alphabet and Microsoft for their respective reporting periods.
The companies reported results for the same calendar quarter, but their fiscal reporting periods differ.
Alphabet reported Q3 2026, while Microsoft reported Q1 FY2027.
The figures should therefore be interpreted according to each company’s reporting period and accounting presentation.
Alphabet Q3 2026 Financial Results
| Financial metric | Q3 2025 | Q3 2026 |
|---|---|---|
| Revenue | $102.35B | $127.58B |
| Operating income | $31.23B | $40.58B |
| Operating margin | 30.5% | 31.8% |
| Net income | $34.98B | $26.47B |
| Diluted EPS | $2.87 | $2.12 |
| Operating cash flow | $48.41B | $42.29B |
| Capital expenditure | $23.95B | $51.36B |
| Free cash flow | $24.46B | -$9.07B |
Alphabet’s financial results demonstrate strong revenue and operating income growth, alongside lower net income and free cash flow.
The difference reflects investment-related losses and increased capital expenditure.
Alphabet Segment Revenue and Operating Income
| Alphabet segment | Q3 2025 revenue | Q3 2026 revenue | Q3 2026 operating income |
|---|---|---|---|
| Google Services | $87.05B | $96.30B | $39.16B |
| Google Cloud | $15.16B | $30.71B | $11.12B |
| Other Bets | $0.34B | $0.37B | -$2.05B |
| Alphabet-level activities | — | — | -$7.66B |
| Consolidated total | $102.35B | $127.58B | $40.58B |
Alphabet-level activities are not a revenue segment. They primarily include shared AI research and development and other corporate expenses.
The table demonstrates the contribution of Google Services and Google Cloud to Alphabet’s operating income.
Google Services remained the largest contributor, while Google Cloud’s operating income increased substantially.
Other Bets and Alphabet-level activities continued to generate operating losses.
The financial performance of these categories provides context for the company’s consolidated operating margin.
Microsoft Q1 FY2027 Financial Results
| Financial metric | Q1 FY2026 | Q1 FY2027 |
|---|---|---|
| Revenue | $77.67B | $92.28B |
| Operating income | $37.96B | $45.92B |
| Operating margin | 48.9% | 49.7% |
| GAAP net income | $27.75B | $36.63B |
| GAAP diluted EPS | $3.72 | $4.92 |
| Non-GAAP net income | $30.83B | $36.42B |
| Non-GAAP diluted EPS | $4.13 | $4.89 |
| Operating cash flow | $45.06B | $58.00B |
| Capital expenditure | $19.39B | $39.37B |
| Free cash flow | $25.66B | $18.63B |
Microsoft’s results demonstrate growth in revenue, operating income, and operating cash flow.
Capital expenditure increased substantially, resulting in lower free cash flow.
The difference between GAAP and non-GAAP earnings reflects the impact of Microsoft’s OpenAI investment-related accounting adjustments.
Microsoft Segment Revenue and Operating Income
| Microsoft segment | Q1 FY2026 revenue | Q1 FY2027 revenue | Q1 FY2027 operating income |
|---|---|---|---|
| Agents and Infra | $61.67B | $76.80B | $40.56B |
| Devices and Consumer | $16.00B | $15.48B | $5.36B |
| Consolidated total | $77.67B | $92.28B | $45.92B |
The table demonstrates that Agents and Infra generated the majority of Microsoft’s revenue and operating income.
The segment’s growth was supported by Azure, Microsoft 365 commercial cloud, productivity and server licensing, industry solutions, and other enterprise services.
Devices and Consumer revenue declined, although the segment continued to generate operating income.
Google Cloud and Azure Growth Metrics
| Cloud metric | Alphabet | Microsoft |
|---|---|---|
| Reporting period | Q3 2026 | Q1 FY2027 |
| Cloud revenue | $30.71B | Microsoft Cloud: $63.9B |
| Reported growth | 103% | Microsoft Cloud: 30% |
| Specific infrastructure metric | Google Cloud Platform and TPU systems | Azure revenue growth: 48% |
| Segment operating income | $11.12B | Not separately disclosed for Azure |
| Cloud segment operating margin | 36.2% | Not separately disclosed for Azure |
The companies use different reporting categories. Microsoft Cloud includes a broader set of enterprise cloud services than Azure alone.
The table provides context for the scale and growth of the companies’ cloud businesses.
Google Cloud reported 103% revenue growth, while Microsoft’s Azure revenue growth was 48%.
Microsoft Cloud revenue was higher than Azure revenue because Microsoft Cloud includes additional enterprise cloud services.
The distinction is important when interpreting the companies’ reported cloud metrics.
Alphabet and Microsoft: Separate Business Outlooks
Alphabet and Microsoft continue to expand their cloud and AI businesses while maintaining substantial revenue from established technology products and services.
Their Q3 2026 and Q1 FY2027 earnings provide information about how these companies are generating revenue, investing in infrastructure, and managing operating profitability.
The companies have different business structures and reporting categories. Alphabet’s results include a large advertising business, Google Cloud, and other technology operations. Microsoft’s results include enterprise cloud infrastructure, productivity software, consumer technology, gaming, and advertising.
The following sections examine the financial considerations for each company independently.
Alphabet’s Growth Opportunities and Financial Considerations
Alphabet’s third-quarter results demonstrate continued growth across Google Services and Google Cloud.
Google Services generated $96.3 billion in revenue, while Google Cloud generated $30.7 billion.
The company’s consolidated revenue increased 25%, and operating income increased 30%.
These results indicate that Alphabet continued to expand its established advertising operations while generating substantial growth from enterprise cloud services.
Google Services and Advertising Revenue
Google Search remains an important contributor to Alphabet’s revenue.
Search and other advertising revenue increased 12%, while YouTube advertising revenue increased approximately 9%.
The growth in Search queries also provides information about user activity.
Alphabet’s advertising business remains an important source of revenue and operating income.
The company’s established advertising operations provide a substantial revenue base that supports investment in cloud infrastructure and AI development.
However, advertising demand can be influenced by economic conditions, business spending, user activity, and changes in digital advertising markets.
The performance of Google Services therefore remains an important factor in Alphabet’s overall financial results.
Google Cloud Expansion
Google Cloud’s revenue growth of 103% was one of the most significant developments in Alphabet’s earnings.
The segment generated $30.7 billion in revenue and $11.1 billion in operating income.
The improvement in operating margin indicates that Google Cloud generated a larger contribution to Alphabet’s operating profitability.
The company’s enterprise cloud business is also relevant to its AI strategy.
Google Cloud can generate revenue from infrastructure consumption, enterprise AI applications, platform services, and TPU systems.
The continued expansion of these services provides Alphabet with an additional source of revenue beyond advertising.
However, cloud infrastructure requires substantial investment in computing capacity, data centers, networking, and other technology assets.
The financial contribution of Google Cloud therefore depends on the relationship between revenue growth, operating costs, capital expenditure, and infrastructure utilization.
AI Investment and Cash Flow
Alphabet’s AI strategy requires ongoing investment in infrastructure and research.
The company reported capital expenditure of $51.4 billion during Q3 2026.
This expenditure exceeded quarterly operating cash flow of $42.3 billion.
The result was negative free cash flow of $9.1 billion.
The difference between operating cash flow and capital expenditure is an important consideration for Alphabet’s financial performance.
Infrastructure investment can support future revenue, but it also creates an immediate cash requirement.
Alphabet’s financial results therefore demonstrate the importance of evaluating revenue growth alongside capital expenditure and free cash flow.
Alphabet’s Financial Position
Alphabet reported $265.1 billion in cash, cash equivalents, and marketable securities at September 30, 2026.
The company’s financial position provides context for its ongoing investment strategy.
However, the balance sheet should be considered alongside debt, capital expenditure, operating cash flow, and other financial commitments.
The company’s investment-related gains and losses also remain relevant to reported net income.
For financial analysis, Alphabet’s operating performance, segment profitability, cash flow, and balance sheet provide a more complete view of its financial position than any single earnings measure.
Microsoft’s Growth Opportunities and Financial Considerations
Microsoft’s first-quarter fiscal 2027 results demonstrate continued growth across enterprise cloud services, productivity software, and AI-related infrastructure.
Revenue increased 19% to $92.3 billion.
Operating income increased 21% to $45.9 billion.
Microsoft Cloud revenue increased 30% to $63.9 billion, while Azure revenue increased 48%.
These results indicate that enterprise technology services remained important contributors to Microsoft’s financial performance.
Azure and Enterprise Cloud Services
Azure’s revenue growth provides information about demand for Microsoft’s cloud infrastructure.
The business supports enterprise computing, application development, data management, AI workloads, and other technology requirements.
Microsoft Cloud’s revenue growth also reflects the performance of Microsoft 365 commercial cloud and other enterprise services.
The combination of infrastructure services and software subscriptions provides Microsoft with multiple sources of enterprise revenue.
The company’s commercial remaining performance obligations of $677 billion provide additional information about contracted enterprise business.
However, the timing of revenue recognition depends on contractual terms and service delivery.
Microsoft 365 and Recurring Revenue
Microsoft 365 commercial cloud revenue increased 18% on an adjusted basis.
The business provides enterprise productivity and collaboration services through subscriptions and related cloud offerings.
Subscription-based services can provide recurring revenue and support customer retention.
Microsoft’s established productivity software business also provides an additional source of enterprise revenue beyond Azure infrastructure services.
The financial contribution of Microsoft 365 is therefore relevant to the company’s broader cloud strategy.
Infrastructure Investment and Cash Flow
Microsoft’s capital expenditure increased substantially during Q1 FY2027.
The company reported additions to property and equipment of $39.4 billion, compared with $19.4 billion in the prior-year quarter.
Operating cash flow increased to $58.0 billion.
However, free cash flow declined to approximately $18.6 billion.
The difference reflects the increase in infrastructure investment.
The company’s cash flow performance demonstrates that operating cash flow can increase while free cash flow declines.
This distinction is important when evaluating Microsoft’s infrastructure investment and capital allocation.
Microsoft’s Financial Position and Shareholder Returns
Microsoft continued to generate substantial operating cash flow while investing in infrastructure and returning capital to shareholders.
The company returned $10.2 billion through dividends and share repurchases during the quarter.
These payments reflect Microsoft’s ongoing capital allocation strategy.
The company’s financial results also indicate that enterprise cloud services generated a substantial contribution to operating income.
However, infrastructure investment, operating costs, and the timing of revenue recognition remain important considerations.
Microsoft’s financial performance should therefore be evaluated through revenue, operating income, cash flow, capital expenditure, and shareholder returns.
Alphabet and Microsoft Earnings: Closing Financial Assessment
Alphabet and Microsoft reported substantial revenue growth during their respective third-quarter and first-quarter fiscal reporting periods.
Alphabet generated $127.6 billion in revenue, representing year-over-year growth of 25%.
Microsoft generated $92.3 billion in revenue, representing growth of 19%.
Both companies reported higher operating income, reflecting continued expansion across their technology businesses.
Alphabet’s operating income increased 30% to $40.6 billion, while Microsoft’s operating income increased 21% to $45.9 billion.
The results demonstrate the continued financial importance of cloud computing, enterprise technology, AI infrastructure, and established consumer services.
Alphabet’s Google Cloud business generated $30.7 billion in revenue, increasing 103%.
Microsoft Cloud revenue reached $63.9 billion, increasing 30%, while Azure revenue increased 48%.
The cloud businesses therefore remained important contributors to the companies’ financial performance.
However, the reported earnings also demonstrate the importance of examining financial results beyond revenue growth.
Alphabet’s net income declined because of investment-related losses, despite higher operating income.
Microsoft’s GAAP net income increased 32%, while its non-GAAP net income increased 18%, reflecting the impact of investment-related accounting adjustments.
Both companies also increased infrastructure investment.
Alphabet’s capital expenditure reached $51.4 billion, while Microsoft’s additions to property and equipment reached $39.4 billion.
The increase in capital expenditure affected free cash flow at both companies.
Alphabet reported negative free cash flow of $9.1 billion, while Microsoft generated approximately $18.6 billion in free cash flow.
These results demonstrate that revenue growth, operating profitability, and cash flow can be influenced by different factors.
For Alphabet, the expansion of Google Cloud and continued growth in Google Services remain important contributors to financial performance.
For Microsoft, Azure, Microsoft Cloud, and enterprise software services continue to provide substantial revenue and operating income.
The financial results also demonstrate that AI-related investment is becoming increasingly important to both companies.
The scale of infrastructure investment creates opportunities for future revenue growth, but it also requires careful consideration of operating costs, capital expenditure, and cash flow.
Alphabet Microsoft earnings therefore provide a useful view of the financial development of two major technology businesses, with cloud infrastructure, AI investment, and established revenue streams remaining central to their financial performance.
Editorial Note: This article is intended for informational and educational purposes only. It provides an analysis of Alphabet’s and Microsoft’s reported financial results and does not constitute financial, investment, tax, or legal advice. The information should not be interpreted as a recommendation to buy, sell, or hold any security. Readers should conduct their own research and consult a qualified financial adviser before making investment decisions. Financial results and market conditions may change, and past performance is not necessarily indicative of future results.