Economic Report | Week Ahead: 26–30 October 2026
Table of Contents
- Economic Calendar: Key Events for 26–30 October 2026
- Week Ahead: Central Bank Decisions and Economic Data
- Chinese Fifth Plenum — Monday
- Israeli Legislative Election — Tuesday
- FOMC Policy Announcement — Wednesday
- Bank of Canada Policy Announcement — Wednesday
- Reserve Bank of New Zealand Policy Announcement — Wednesday
- UK Autumn Budget — Wednesday
- Australian CPI — Wednesday
- ECB Policy Announcement — Thursday
- US GDP — Thursday
- US PCE Inflation — Thursday
- Tokyo CPI — Thursday
- BoJ Policy Announcement — Friday
- Week in Review: Economic Data and Policy Developments
- Market Implications: Interest Rates, Bonds and Currencies
- Conclusion: The Key Events to Watch
- Editorial Note and Disclaimer
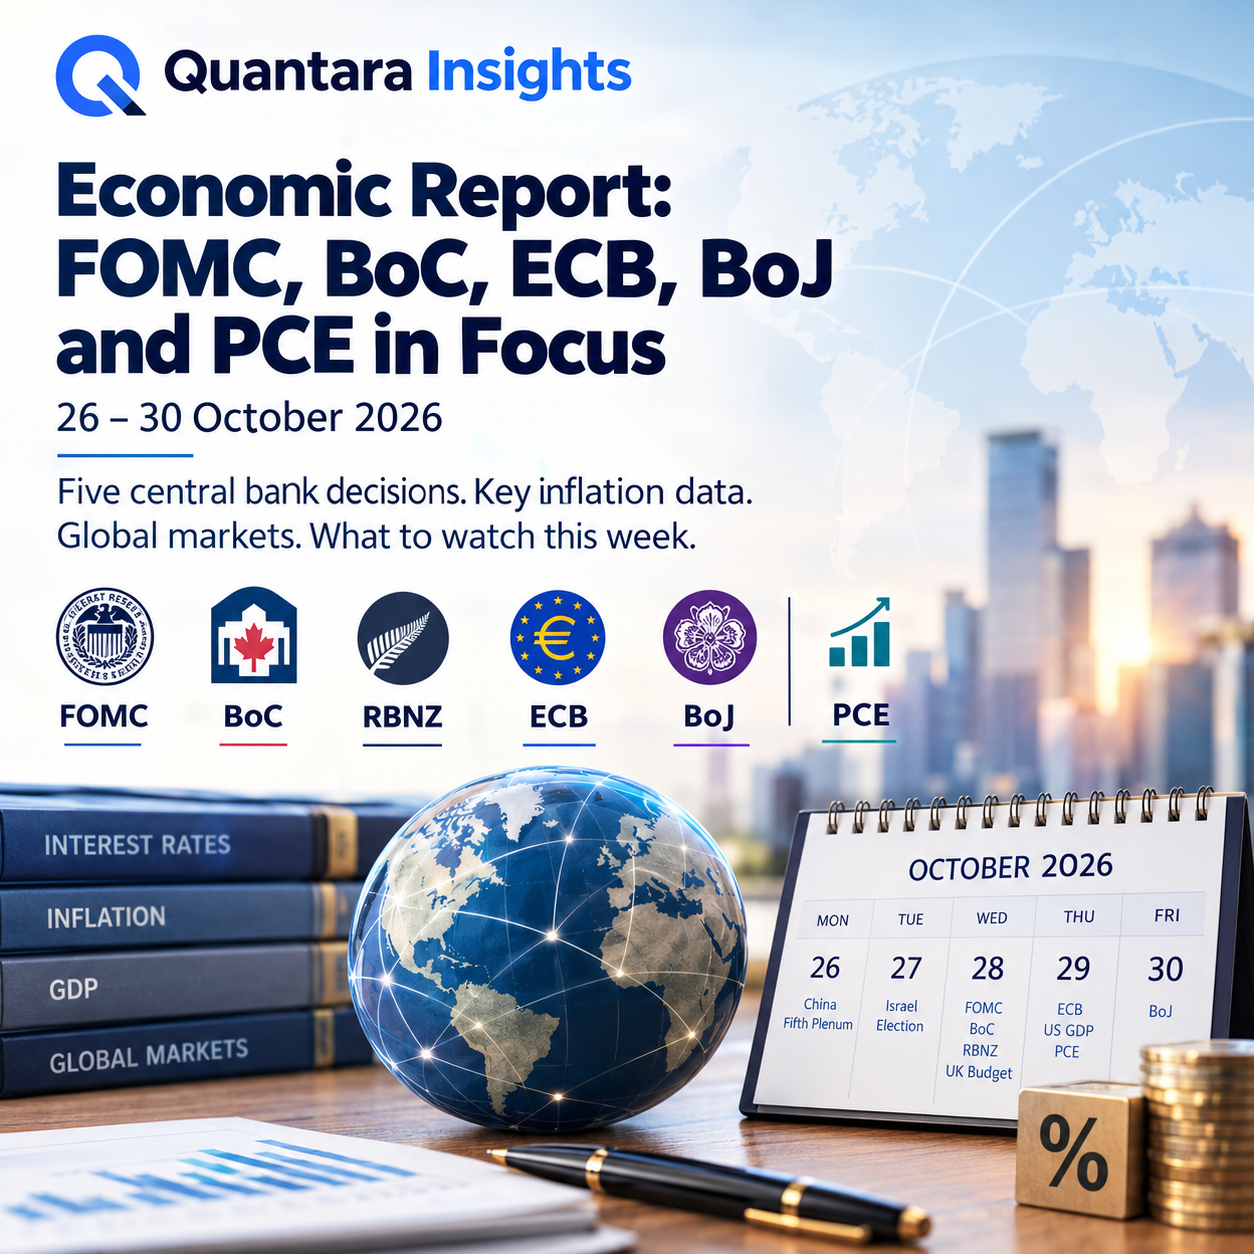
The Economic Report for 26–30 October 2026 focuses on a particularly busy week for global monetary policy, inflation and economic growth. Five major central banks are scheduled to deliver policy decisions, while US third-quarter GDP and September Personal Consumption Expenditures (PCE) inflation data will provide important information about the direction of the world’s largest economy. The Federal Reserve, Bank of Canada (BoC), Reserve Bank of New Zealand (RBNZ), European Central Bank (ECB) and Bank of Japan (BoJ) will all be in focus as markets assess the implications for interest rates, currencies and government bond yields.
The week also includes the UK Autumn Budget, Australian inflation, Japanese Tokyo CPI, European growth and inflation figures, and a range of regional economic indicators. Together, these releases should provide a broader picture of whether price pressures are proving persistent, whether economic activity is maintaining momentum and how policymakers are balancing inflation risks against growth concerns.
The FOMC announcement on Wednesday is likely to be one of the main global market events. Investors will assess not only the policy rate decision but also the accompanying statement, the voting pattern and any clues about the likely direction of policy in the coming months. The BoC and RBNZ decisions will add a regional dimension to the week’s monetary policy developments, while the ECB and BoJ will provide further insight into the differing challenges facing Europe and Japan.
On Thursday, US GDP and PCE inflation will be especially important. GDP will help establish whether economic activity maintained a firm pace during the third quarter, while PCE inflation will provide another assessment of the progress, or lack of progress, towards price stability. A combination of resilient growth and persistent inflation could complicate the outlook for interest rates.
The European and Japanese data releases will also matter. Eurozone GDP, national inflation reports and Tokyo CPI could influence expectations for the ECB and BoJ, while Canadian GDP at the end of the week will provide a useful update on activity following the BoC’s decision.
The central theme for markets will be the interaction between inflation, growth and monetary policy. The direction of interest rates will depend not only on whether individual releases beat or miss expectations, but also on how policymakers interpret the combined evidence.
Economic Calendar: Key Events for 26–30 October 2026
The following calendar highlights the main scheduled events and economic releases for the week. Market forecasts cited in the analysis represent expectations available when the original report was prepared and should not be treated as confirmed outcomes.
Monday, 26 October
- US Treasury buyback, with liquidity support focused on the 20-year to 30-year sector.
- Chinese Fifth Plenum begins, with discussions expected to continue through 29 October.
- Swedish Producer Price Index (PPI) for September.
- German Ifo Business Climate Index for October.
Tuesday, 27 October
- Israeli legislative election for the Knesset.
- Chinese industrial profits for September.
- US durable goods orders for September.
- Richmond Fed Manufacturing Index for October.
- Dallas Fed Manufacturing Index for October.
Wednesday, 28 October
- Federal Reserve FOMC policy announcement.
- Bank of Canada policy announcement and Monetary Policy Report.
- Reserve Bank of New Zealand policy announcement.
- UK Autumn Budget.
- Australian CPI for September and the third quarter.
- German GfK Consumer Confidence for November.
- Italian industrial sales and producer price data.
Thursday, 29 October
- European Central Bank policy announcement.
- US advance estimate of third-quarter GDP.
- US September Personal Income and Outlays report, including PCE inflation.
- Tokyo CPI for October.
- Swedish third-quarter GDP and eurozone economic sentiment.
- EU–Canada summit begins.
Friday, 30 October
- Bank of Japan policy announcement.
- Japanese unemployment rate for September.
- French, German, Spanish and Italian GDP or preliminary inflation releases.
- Eurozone third-quarter GDP.
- Canadian GDP for August.
- Turkish central bank meeting minutes.
- EU–Canada summit continues.
Week Ahead: Central Bank Decisions and Economic Data
Chinese Fifth Plenum — Monday
China’s Fifth Plenum is scheduled to take place from 26 to 29 October. The meeting is expected to focus primarily on Party governance, internal discipline and policy priorities ahead of the 21st Party Congress in 2027. Although the meeting is not necessarily expected to produce an immediate, large-scale stimulus package, the economic direction outlined in the concluding communiqué will be closely followed.
For financial markets, the central question is whether Chinese policymakers provide clearer indications of their willingness to support domestic demand. The economy has continued to face an uneven recovery, with exports providing an important source of support while household consumption and confidence have remained more subdued.
Investors will therefore look for references to consumption, infrastructure investment, local government debt and the development of strategic industries. Any indication that policymakers intend to accelerate infrastructure spending or expand targeted measures to support household demand could influence expectations for Chinese growth.
The local government debt issue is particularly important. Local authorities have faced constraints on their ability to finance projects, while property-related weakness has continued to weigh on confidence and economic activity. A more explicit commitment to managing these pressures could be interpreted as a positive signal, although the scale and implementation of any measures would ultimately matter more than the wording alone.
China’s focus on strategic industries also remains relevant to global markets. Investment in advanced manufacturing, technology and other priority sectors could support industrial production and exports, but would not necessarily translate into an immediate improvement in household consumption.
For currencies and commodities, the implications will depend on whether the meeting signals a meaningful change in the growth outlook. Stronger support for domestic demand could improve sentiment towards industrial commodities and selected Asian currencies. A communiqué that reiterates existing priorities without offering additional measures may have a more limited impact.
The key point is that investors should distinguish between broad policy objectives and specific measures. A statement supporting growth does not automatically imply a near-term stimulus announcement. The details of any financing arrangements, spending commitments or consumption initiatives will be more important in determining the likely economic effect.
Israeli Legislative Election — Tuesday
Israel is scheduled to hold a legislative election for the 120-member Knesset. The political outlook is uncertain, with the original report indicating that neither the bloc associated with Prime Minister Benjamin Netanyahu nor the opposition group led by former IDF chief Gadi Eisenkot was expected to secure the 61 seats required for a parliamentary majority.
If the election produces another fragmented parliament, negotiations between political parties could take time. The performance of smaller parties around the electoral threshold will be important because relatively small changes in seat allocation can influence coalition arithmetic.
From a market perspective, the election’s direct economic impact will depend on whether the result produces a workable government and whether that government can establish a credible policy direction. Domestic fiscal policy, security spending and confidence could be affected by prolonged political uncertainty.
Geopolitics will remain an important consideration. Investors are likely to assess the implications for Israel’s approach to Iran, the Palestinians and regional normalisation. The extent to which the election changes security policy or relations with the United States and regional partners could influence perceptions of geopolitical risk.

The original analysis suggested that a Netanyahu-led government would be likely to maintain a confrontational security stance towards Iran and its regional proxies. An Eisenkot-led government could also maintain a firm position on Iran, while potentially placing greater emphasis on coordination with the United States and regional partners. These are political assessments rather than certain outcomes.
An inconclusive result would create a different source of uncertainty. Coalition negotiations could delay policy decisions and prolong questions about the government’s composition. Markets would then focus on whether the process appears likely to produce a stable administration or an extended period of political uncertainty.
For financial markets more broadly, the election is likely to be secondary to the major central bank decisions and US inflation releases unless the result materially changes the geopolitical outlook. Nevertheless, it forms part of the wider risk environment in which energy prices, currencies and investor confidence are being assessed.
FOMC Policy Announcement — Wednesday
The Federal Open Market Committee (FOMC) is scheduled to announce its monetary policy decision on Wednesday, making the Federal Reserve a central focus of the week’s Economic Report. The original report’s baseline expectation is for the Fed to leave its policy rate unchanged at 3.75%–4.00%.
That expectation reflects the view that policymakers may prefer to assess incoming inflation and growth data before making another adjustment to monetary policy. The decision will be particularly important because the US economy has shown resilience while inflation pressures have remained a challenge.
The original report cites a Reuters economist poll in which 94 of 100 respondents expected a hold. That survey result should be read as a snapshot of market and economist expectations at the time the source was prepared, rather than a guarantee of the Committee’s decision.
The policy debate is complicated by the combination of economic resilience and elevated inflation. The Atlanta Fed’s GDPNow estimate was cited in the original analysis as tracking third-quarter growth at approximately 3.5%. If growth remains firm, the Fed may have less reason to ease policy quickly. At the same time, stronger activity can support demand and make it more difficult for inflation to return consistently to the central bank’s target.
The original report also highlights energy costs and tariffs as possible sources of inflation pressure. Higher energy prices can affect household spending directly and increase costs for businesses. Tariffs can raise the prices of imported goods and intermediate inputs, although the eventual effect depends on how costs are distributed among producers, importers, retailers and consumers.
Policymakers must therefore assess whether recent price increases are temporary or likely to become more persistent. A short-lived energy-related increase may not require the same policy response as broad inflation across services, housing-related costs and other components. If price pressures become more widespread, however, the argument for maintaining restrictive monetary policy becomes stronger.
The PCE report scheduled for Thursday will be particularly relevant to this debate. Although the FOMC decision precedes the release, the new figures could influence market expectations for subsequent meetings. Investors will examine both monthly and annual inflation rates, with particular attention to the core measure, which excludes food and energy prices.
The voting pattern will also be important. The original report notes that some analysts expected possible dissent from officials who had previously favoured a more restrictive stance. A split vote could reveal differences in how Committee members assess the balance between inflation risks and economic conditions.
A unanimous hold would not necessarily indicate that the Fed is comfortable with the inflation outlook. The statement and accompanying communication could still signal that policymakers remain concerned about persistent price pressures. Conversely, a decision to maintain rates while acknowledging risks on both sides could indicate that officials want additional evidence before deciding on the next move.
The original report cites a market and analyst debate in which some participants anticipated further increases, potentially taking the policy rate to 4.00%–4.25% or higher. Those expectations should be understood as conditional forecasts. The eventual path will depend on inflation, labour-market conditions, economic activity and financial conditions.
For bond markets, the distinction between a hold and a change in guidance may be more important than the decision itself. If the Fed leaves rates unchanged but signals a prolonged period of restrictive policy, short-term yields may remain supported. If it places greater emphasis on emerging weakness in employment or demand, investors may reassess the expected timing of future moves.
Currency markets will likewise focus on the relative policy outlook. A more restrictive Fed stance could support the US dollar against currencies whose central banks appear more inclined to ease. However, the response will also depend on what markets have already priced in and how other central banks communicate their own decisions.
The FOMC announcement should therefore be assessed through three questions: whether the policy rate changes, how policymakers describe the inflation outlook, and whether the communication alters expectations for subsequent meetings. The answers will help determine how the decision feeds into broader interest rate expectations.
Bank of Canada Policy Announcement — Wednesday
The Bank of Canada is scheduled to announce its policy decision on Wednesday, alongside the release of its quarterly Monetary Policy Report. The original report highlights an increase in market expectations for a rate hike, driven by concerns about persistent inflation and the possibility that higher energy costs could broaden into other parts of the economy.
The Canadian inflation outlook presents policymakers with a difficult balance. Headline inflation was reported at 3.1% year on year in September, below the cited consensus expectation of 3.2% but above the previous reading of 3.0%. The softer-than-expected result did not eliminate concerns about inflation expectations or the potential effect of energy prices.
The original report also points to the Bank’s third-quarter Business Outlook Survey. It states that 41% of firms expected inflation above 3% over the following two years, compared with 44% previously. Five-year inflation expectations rose to 3.91% from 3.39%.
These survey measures matter because inflation expectations can influence wage negotiations, pricing decisions and household behaviour. If firms and consumers expect inflation to remain elevated, they may adjust prices and spending decisions accordingly. That can make it more difficult for a central bank to bring inflation down without maintaining restrictive financial conditions.
The energy-price question is particularly important. A temporary rise in energy prices may initially affect headline inflation, but a prolonged increase can influence transportation, production and service costs. The extent to which these pressures pass through to core inflation will be a key consideration for the BoC.
The original report notes that Royal Bank of Canada had shifted its forecast towards a hike, while Governor Tiff Macklem had warned that the longer elevated energy prices persisted, the harder they would be to look through. Such comments suggest that policymakers may be reluctant to assume that energy-related inflation will fade quickly.
However, a rate increase would not be without risks. Higher borrowing costs could weigh on household spending, housing activity and business investment at a time when growth remains uncertain. The Bank must assess whether tightening is necessary to contain inflation expectations or whether the existing policy stance is sufficient to moderate demand.
The Monetary Policy Report will provide important context for the decision. Investors will examine the Bank’s updated projections for growth and inflation, its assessment of risks and any changes to its interpretation of the balance between supply-side and demand-side pressures.
The original analysis cited market pricing that implied a substantial probability of a 25-basis-point increase. Those expectations are not equivalent to a confirmed decision. The outcome will depend on the Governing Council’s assessment of the inflation outlook and the risks facing the Canadian economy.
If the BoC raises rates and signals that further tightening may be necessary, Canadian short-term yields could move higher. The Canadian dollar could also receive support if markets interpret the decision as more restrictive than expected. The size and persistence of any reaction will depend on the accompanying statement and the extent to which the move has already been priced in.
A hold could produce a different response, particularly if markets have attached a high probability to an increase. In that case, investors would focus on whether the Bank views the decision as a temporary pause or evidence that the inflation outlook has become less concerning.
The BoC decision is therefore one of the week’s most important events for Canadian assets. The policy rate, the Monetary Policy Report and the Governor’s press conference should be considered together when assessing the likely path of interest rates.
Reserve Bank of New Zealand Policy Announcement — Wednesday
The Reserve Bank of New Zealand (RBNZ) is also scheduled to announce its policy decision on Wednesday. The original report describes expectations for a 25-basis-point increase in the Official Cash Rate to 3.00%, although the outlook is complicated by a slightly softer-than-expected third-quarter CPI report.
Inflation was reported at 3.7% year on year, compared with an expectation of 3.8%, while the quarterly increase was 0.7%, below the cited forecast of 0.8%. Although the data came in marginally below expectations, the annual rate remained above the RBNZ’s 1%–3% target range.
The distinction between the annual rate and the latest quarterly movement is important. A softer quarterly reading may suggest that momentum is easing, but it does not necessarily establish that inflation is returning to target. Policymakers will need to assess the composition of the data, the persistence of services inflation and the effect of exchange-rate movements on import prices.
The original report notes that ANZ, BNZ and ASB expected a hike, citing above-target inflation, a weaker New Zealand dollar and higher energy prices. A weaker currency can increase the domestic cost of imported goods, while higher fuel and transportation costs can affect a broad range of prices.
Westpac, by contrast, expected the RBNZ to hold at 2.75%. The difference of opinion illustrates the uncertainty surrounding the decision. A central bank may choose to tighten policy if it believes inflation risks are becoming entrenched, or hold if it considers the existing policy setting sufficiently restrictive and wants to assess the effect of earlier changes.
Markets were reported to be pricing in a roughly 75%–80% probability of a 25-basis-point increase. That pricing provides a useful indication of expectations but can change rapidly as new information emerges.
The statement will be important in determining whether the decision represents the beginning of a broader tightening cycle or a limited response to persistent inflation. Investors will look for changes in the RBNZ’s assessment of inflation expectations, domestic demand, wage growth and the outlook for imported inflation.
For the New Zealand dollar, the reaction will depend on the difference between the actual decision and the policy path implied by markets. A hike accompanied by cautious guidance may not generate sustained currency strength if investors believe the Bank is nearing the end of its tightening process. A hold accompanied by a firm warning about inflation could also limit any dovish interpretation.
The RBNZ decision adds another dimension to the week’s global monetary policy picture. Differences between New Zealand, Canada and the United States may influence relative yields and currency valuations, particularly if their respective central banks communicate different levels of concern about inflation.
UK Autumn Budget — Wednesday
The UK Autumn Budget will be an important fiscal event during a week dominated by monetary policy and inflation data. The original report suggests that the Chancellor may seek to deliver a relatively measured package, balancing fiscal constraints with an effort to avoid unnecessarily damaging business confidence.
The central issue is fiscal headroom. The source analysis cites a previous estimate of approximately £23.6 billion and suggests that the figure could fall towards £15 billion. Such estimates are sensitive to the assumptions used for economic growth, inflation, borrowing costs, tax receipts and public spending.
A smaller fiscal buffer would limit the Government’s ability to absorb adverse economic developments without changing taxes or spending plans. It could also increase the importance of demonstrating a credible fiscal framework to bond investors.
The original report suggests that a capital gains tax increase was no longer a central expectation. It also highlights the possibility of higher taxes on banks, potentially raising between £2 billion and £5 billion depending on the approach taken. These possibilities should be treated as elements of the original market outlook rather than confirmed Budget measures.
Investors will also look for clarity on defence spending, energy-related measures, the Triple Lock, the proposed “Your First Home” scheme and possible adjustments to utility bills. The implications of any policy will depend on the final details, implementation timetable and interaction with existing commitments.
For businesses, the composition of the Budget will matter as much as its headline fiscal effect. Measures that raise operating costs or reduce investment incentives could weigh on hiring and capital expenditure. Conversely, a more predictable tax environment could help reduce uncertainty for firms making longer-term decisions.
The banking sector may be particularly sensitive to any proposed tax changes. Investors will assess whether additional taxation affects profitability, lending incentives or the ability of banks to absorb other cost pressures. The ultimate effect will depend on whether measures are targeted, temporary or structural.
The gilt market will be another focus. The original analysis anticipates a potential move away from longer-dated issuance and a modest increase in the overall issuance plan. Investors will examine the expected volume and maturity distribution of borrowing, as well as the relationship between the fiscal outlook and debt-servicing costs.
The interaction between fiscal policy and monetary policy is important. A Budget that supports demand could complicate the inflation outlook if the economy is already facing persistent price pressures. A more restrictive fiscal stance could have the opposite effect, although the impact would depend on which taxes and spending programmes are adjusted.
The Budget should therefore be assessed across three areas: the credibility of the fiscal projections, the distribution of tax and spending changes, and the implications for government borrowing. Those factors will help determine the response of gilt yields, sterling and UK-focused equities.
Australian CPI — Wednesday
Australian CPI is scheduled to be released on Wednesday, providing an important update ahead of the Reserve Bank of Australia’s policy meeting on 3 November.
The original report expects the third-quarter and September inflation readings to rise. It also cites comments from RBA Deputy Governor Hauser that the inflation outlook had become materially worse and that quarterly trimmed-mean inflation could exceed the Bank’s previous forecast of 0.8%.
The cited consensus expectation for a 1.0% quarterly increase would represent an important test of the RBA’s assessment. A reading above expectations could strengthen the case for another rate increase, particularly if the underlying measures show broad-based price pressures rather than a rise concentrated in a small number of volatile categories.
Trimmed-mean inflation is particularly relevant because it attempts to reduce the influence of unusually large price changes. It can provide a clearer view of the underlying inflation trend than headline CPI alone, although it is still necessary to consider the full range of indicators.
If underlying inflation remains firm, the RBA may conclude that demand and pricing behaviour are not cooling sufficiently. That could support a more restrictive policy stance, even if some components of headline inflation moderate.
A softer report could produce a different interpretation. If the data show that price pressures are easing more consistently, policymakers may prefer to hold rates while assessing the effect of previous policy decisions.
Markets were reported to be pricing in roughly equal probabilities of a hike or a hold at the next meeting. This means that a meaningful surprise could have a pronounced effect on short-term interest rate expectations and the Australian dollar.
The reaction will depend on the details. A high headline CPI reading driven by temporary or volatile components may have a different effect from a rise in trimmed-mean inflation and services prices. Investors will therefore assess the composition of the report rather than focusing exclusively on the headline number.
Australian inflation also forms part of the wider global picture. Persistent price pressures across several economies would make it more difficult for central banks to relax policy, while a more consistent moderation in inflation could create greater flexibility.
ECB Policy Announcement — Thursday
The European Central Bank is scheduled to announce its policy decision on Thursday. The original report does not expect a rate increase at this meeting, although it notes that the economic and inflation backdrop could still support further tightening at a later stage.
The ECB faces a complicated combination of price pressures, uneven growth and fiscal uncertainty. The performance of the eurozone economy outside France has been relatively resilient in the source analysis, while developments in French bond markets and domestic politics have created additional uncertainty.
French government bond yields and the spread between French and German borrowing costs have attracted attention because they reflect investor assessments of fiscal sustainability and political risk. A sustained rise in borrowing costs can affect financing conditions and create pressure for fiscal adjustments.
However, monetary policy cannot directly resolve every fiscal or political problem. The ECB must distinguish between changes in financial conditions that threaten the transmission of monetary policy and developments that primarily reflect country-specific fiscal risk.
The original report highlights questions about the Transmission Protection Instrument (TPI), which is intended to address unwarranted and disorderly market dynamics that threaten the transmission of monetary policy. Investors may look for clarification on how the ECB assesses the French situation and whether it believes recent market movements affect the broader policy outlook.
Inflation remains the other central consideration. If price pressures persist and economic activity holds up, the ECB may retain the option of further tightening. If growth weakens materially, however, the case for another increase becomes less straightforward.
A hold would not necessarily signal that the tightening cycle is definitively over. The statement and press conference will be important in showing how the Governing Council interprets the balance of risks and what evidence it would need before changing policy again.
Investors will pay particular attention to the ECB’s description of inflation persistence, wage developments, services prices and the outlook for domestic demand. They will also listen for any direct reference to France’s fiscal and bond-market situation.
For eurozone government bonds, the decision and communication could affect both the expected path of short-term interest rates and country-specific risk premiums. German yields may respond primarily to the ECB’s policy outlook, while French yields may also be influenced by fiscal and political developments.
The euro’s response will similarly depend on relative policy expectations. If the ECB appears more restrictive than markets anticipated, the currency could receive support. If the Bank places greater emphasis on weak activity or signals a prolonged pause, the reaction could be less supportive.
The ECB announcement is therefore likely to be judged not only by whether rates change, but also by how policymakers communicate their willingness to respond to future inflation data and financial-market developments.
US GDP — Thursday
The US advance estimate of third-quarter GDP is scheduled for Thursday and will provide an important assessment of economic momentum. The original report cites a consensus forecast of 3.0% quarter-on-quarter at a seasonally adjusted annual rate, following growth of 2.2% in the second quarter.
The Atlanta Fed’s GDPNow estimate was cited at approximately 3.5%, indicating that some tracking models were pointing to stronger growth than the consensus forecast. These estimates are not interchangeable with the official GDP release, but they provide a useful indication of how available data are feeding into expectations.
The headline GDP figure will attract attention, although the composition of growth will be equally important. Consumer spending, business investment, inventories, government spending and net exports can all make different contributions to the overall result.
The original report cites an analysis from Continuum Economics that expected headline growth of 2.8%, with final sales to domestic buyers rising by 3.8%. It also anticipated strong business investment, including investment associated with artificial intelligence.
Investment in technology infrastructure and AI-related equipment can provide support to capital expenditure even when other parts of the economy are more subdued. However, the sustainability of that investment will depend on expected returns, financing conditions and the broader outlook for business demand.
Inventories and trade were identified in the original analysis as important sources of uncertainty. Inventory accumulation can add to measured GDP in a given quarter, but it does not necessarily indicate stronger final demand. Conversely, a large contribution from imports can reduce headline GDP through the national accounting treatment of trade, even where imports reflect strong domestic spending or investment.
This is why analysts often examine final sales to domestic purchasers alongside headline GDP. The former helps assess the underlying strength of domestic demand by reducing the influence of inventory movements and net exports.
The price data included in the GDP report will also be relevant. The original report cites an expectation for core PCE inflation to rise at an annualised quarterly rate of approximately 2.4%, compared with 3.3% previously. The figure will provide another indication of how inflation evolved during the quarter, although the monthly September PCE report will offer a more recent snapshot.
For the Federal Reserve, the combination of growth and inflation will matter more than either number in isolation. Strong GDP accompanied by persistent price pressures could reinforce the argument for keeping interest rates restrictive. Strong growth combined with moderating inflation could provide policymakers with greater flexibility.
A weaker GDP result might raise questions about the durability of demand, especially if consumer spending and business investment also slow. However, a single quarter of slower growth would not automatically establish that the economy was entering a prolonged downturn.
Bond markets will assess whether the report changes the expected path of monetary policy. A stronger-than-expected result could push yields higher if investors conclude that the economy can withstand restrictive policy for longer. A weaker result could lower yields if it leads to expectations of a more cautious policy stance.
Equity markets may respond differently depending on the composition of growth. Strong business investment can support earnings expectations in some sectors, while higher yields can weigh on valuations. The report’s implications will therefore depend on both the growth details and the accompanying inflation figures.
US PCE Inflation — Thursday
US PCE inflation is one of the most important releases in this week’s Economic Report because it provides a key measure of the price pressures monitored by the Federal Reserve. The September Personal Income and Outlays report is scheduled for Thursday, alongside the advance GDP estimate.
The original report cites expectations for headline PCE inflation to rise by 0.5% month on month in September, compared with 0.3% previously. The annual headline rate was expected to increase to 3.6% from 3.4%.
Core PCE inflation, which excludes food and energy, was expected to rise by 0.3% month on month, compared with 0.2% previously. The annual core rate was expected to increase to 3.1% from 3.0%.
These figures are the original report’s cited consensus estimates, not confirmed outcomes. Their importance lies in what they would suggest about the persistence of inflation and the degree of progress towards the Federal Reserve’s objective.
Headline PCE can be influenced by changes in food and energy prices, making it sensitive to movements in oil, fuel and other commodities. Core PCE excludes those categories to provide a view of underlying price pressures, although it remains important to consider the full range of inflation measures.
The original report notes that September CPI and PPI releases pointed to upside risks for PCE inflation. Headline CPI reportedly rose by 0.6% month on month, in line with expectations, while core CPI increased by 0.3%, above the cited 0.2% forecast.
The producer price data were described as substantially stronger than expected, with headline PPI rising by 1.3% month on month against a forecast of 0.5%, and core PPI increasing by 0.7% against a forecast of 0.3%.
These indicators can provide clues about the direction of PCE inflation, but their components do not map directly or uniformly into the PCE measure. The PCE index uses different weights and includes categories that may be treated differently in other price indices.
The original analysis notes that airline fares increased sharply, while some healthcare and insurance components relevant to PCE were softer. This difference illustrates why the relationship between CPI, PPI and PCE is not mechanical. Some price movements may be strong in one report but have a smaller effect on another.
The original report also cites Bank of America estimates of a 0.34% monthly increase in core PCE and a 0.52% increase in headline PCE. Those estimates implied an annual core rate around 3.1%, with headline inflation around the mid-3% range. The bank reportedly cautioned that its projections were subject to greater uncertainty because of methodological changes affecting certain services categories.
The Federal Reserve will be interested in whether the inflation trend is broad-based and persistent. One stronger monthly reading may be influenced by specific categories, but repeated increases across services, goods and other components would be more concerning.
The three-month annualised rate of core PCE is another measure highlighted by the original analysis. It can provide a more recent indication of inflation momentum than the year-on-year rate, which is affected by the comparison with prices a year earlier. However, annualising short periods can make the measure volatile, so it should be considered alongside monthly and annual figures.
If core PCE rises more strongly than expected, markets may conclude that inflation progress has stalled. That could reinforce expectations for restrictive interest rates and reduce the likelihood of near-term easing. If the report is softer, investors may become more confident that price pressures are moderating, although one release would not settle the policy debate.
The original report cites Pantheon Macroeconomics as arguing that the data could lift the three-month annualised core PCE rate towards 3.0% from 2.0%. The firm reportedly considered that too high for the Federal Reserve to claim convincing progress on inflation, while still expecting the Fed to wait until December before considering another increase.
This illustrates the difference between an inflation assessment and a policy decision. Even if the data are disappointing, policymakers may prefer to wait for additional evidence, particularly if the labour market is showing signs of weakness or if a rate increase could impose additional costs on economic activity.
The timing of the release is also significant. The FOMC decision comes on Wednesday, before the September PCE data are published on Thursday. The figures therefore cannot inform the Committee’s Wednesday decision, but they may affect market expectations for subsequent meetings.
For the US dollar, the reaction will depend on whether the data change the relative outlook for US interest rates. A stronger inflation report could support the currency if markets price in a more restrictive Fed. A softer report could weigh on the dollar if investors reduce expectations for further tightening.
Bond yields may respond to the same reassessment. Shorter-dated Treasury yields are particularly sensitive to changes in the expected policy rate, while longer-dated yields also reflect growth, inflation expectations and the term premium.
The most useful way to interpret the PCE release will be to compare the headline and core monthly changes, the annual rates and the composition of price movements. The report should then be considered alongside GDP, employment and other indicators to assess the likely direction of Federal Reserve policy.
Tokyo CPI — Thursday
Tokyo CPI is scheduled for Thursday and will provide an early indication of inflation trends ahead of Japan’s national CPI figures. The release is especially relevant because it coincides with the BoJ policy meeting period and could influence expectations for future monetary tightening.
The original report notes that Tokyo headline CPI rose to 2.7% year on year in September from 1.9% previously, while core and super-core measures also increased. Higher energy costs and imported inflation were identified as contributing factors.
Tokyo inflation is closely monitored because it can provide an early indication of national price developments. However, it is not a perfect substitute for the nationwide figures. Differences in regional price patterns and the composition of expenditure mean that the national outcome may not match the Tokyo reading exactly.
For the BoJ, the important question is whether inflation reflects temporary cost pressures or a more durable change in domestic price-setting behaviour. Imported inflation can raise prices even when domestic demand is not especially strong. More persistent inflation may be indicated when firms continue to pass through costs and wage growth supports household purchasing power.
A stronger-than-expected Tokyo CPI reading could reinforce expectations that the BoJ will eventually raise interest rates again. A softer report could reduce immediate pressure for tightening, although policymakers would still need to assess the national inflation trend and wage developments.
The yen may respond to any shift in expectations for the policy rate, particularly relative to the Federal Reserve. A more hawkish interpretation of Japanese inflation could support the currency if markets anticipate a narrowing of the interest rate differential. However, exchange rates are also influenced by risk sentiment, capital flows and broader market positioning.
The timing of the Tokyo CPI release means investors may assess the data alongside the BoJ’s policy communication. A strong reading would be more influential if policymakers also express confidence that underlying inflation is approaching or reaching their objective.
BoJ Policy Announcement — Friday
The Bank of Japan’s policy announcement is scheduled for Friday, 30 October, following the September policy adjustment described in the original report. The source analysis expects the BoJ to leave its policy rate unchanged at 1.25%, with attention focused on the Bank’s inflation assessment and updated Outlook Report.
The BoJ’s challenge differs from that of central banks dealing primarily with above-target inflation after a period of strong demand. Japan has spent many years attempting to establish durable inflation and wage growth. Policymakers therefore need to determine whether recent price increases represent a sustainable change in domestic conditions or are being driven mainly by energy prices and a weaker yen.
The original report cites Governor Ueda as saying that underlying inflation was already quite close to 2%. It also suggests that the BoJ could revise its inflation forecasts and reassess whether underlying inflation has reached its target.
A change in the Bank’s language could be important. Describing inflation as approaching the target is not the same as concluding that it has been achieved on a sustainable basis. If policymakers express greater confidence in the durability of inflation, markets may infer that further increases in interest rates are more likely.
However, a pause in October would not necessarily signal a reversal of the tightening process. The Bank may prefer to assess the impact of its September move before deciding whether another adjustment is appropriate.
Investors will therefore focus on the updated Outlook Report, the treatment of underlying inflation, the wage outlook and the risks associated with the yen. A weaker currency can increase import prices, particularly for energy and other commodities. Yet the effects on domestic demand and corporate profits can vary across sectors.
The original report suggests that December may be a more likely timing for another rate increase, with markets anticipating the possibility of a further 25-basis-point move by year-end. This remains a forecast rather than a commitment from the Bank.
For Japanese government bonds, a more hawkish inflation assessment could put upward pressure on yields as investors reassess the expected policy path. The yen could also respond if markets anticipate a narrower interest rate differential with other major economies.
The BoJ’s communication will therefore matter as much as the decision to hold rates. Investors will look for evidence that policymakers are becoming more confident in the inflation outlook, while also assessing whether economic conditions can support a gradual continuation of policy normalisation.
Week in Review: Economic Data and Policy Developments
The previous week’s releases provide useful context for the central bank decisions ahead. Inflation remained an important theme in Canada and the United Kingdom, while Chinese activity data showed some improvement. Business surveys in the UK and eurozone also offered clues about the state of economic momentum.
Canadian CPI — Monday
Canadian inflation was softer than expected in September, with headline CPI reported at 3.1% year on year against a cited forecast of 3.2%, compared with 3.0% previously.
The original report states that CPI excluding gasoline rose by 2.2% year on year, easing from 2.4% in August. Slower food price inflation was also noted, with the annual rate declining to 2.2% from 2.8%.
The Bank of Canada’s average core inflation measure reportedly eased to 2.0% from 2.2%. These developments provided some evidence that underlying inflation pressures were moderating, although the headline rate remained above the previous month’s reading.
Despite the softer report, expectations for a BoC rate increase remained elevated in the source analysis. The concern was that energy-driven inflation could become more persistent, particularly if firms passed higher costs through to consumers.
The original report also highlighted an increase in five-year inflation expectations in the Bank’s business survey. Such measures matter because inflation expectations can influence pricing behaviour and wage negotiations, potentially making inflation more persistent.
The Canadian data therefore present a mixed picture. Softer core inflation and easing food-price pressures suggest some moderation, while the headline increase and survey measures indicate that inflation risks have not disappeared.
This tension helps explain why the BoC decision is likely to attract considerable attention. Policymakers must determine whether the recent inflation pattern is consistent with a gradual return to target or whether further tightening is needed to prevent expectations from becoming entrenched.
Chinese Activity Data — Monday
Chinese activity data were broadly stronger than expected in the original report. GDP growth was reported at 4.5% year on year, compared with a cited expectation of 4.4% and a previous reading of 4.3%.
Retail sales growth accelerated to 1.1% from 0.4%, while industrial production also edged higher. These figures suggested that activity had improved, although the report cautioned that the underlying picture remained uneven.
Exports were identified as a likely source of support for GDP, while domestic demand continued to appear relatively weak. Retail sales may also have benefited from spending associated with the Mid-Autumn Festival, making it important to distinguish temporary calendar effects from a sustained improvement in consumption.
The stronger readings could reduce immediate pressure for additional stimulus. However, a single set of better data does not establish that the recovery is self-sustaining.
The original report suggests that policymakers may continue to favour targeted measures to support investment and housing while leaving the seven-day reverse repo rate unchanged at 1.40% for the remainder of the year. That is an assessment of the likely policy path, not a confirmed commitment.
The key issue for markets is whether domestic demand strengthens sufficiently to reduce reliance on external demand and policy support. If household spending remains weak, policymakers may still need to consider additional measures in the coming months.
Chinese Loan Prime Rates — Tuesday
China’s one-year and five-year Loan Prime Rates were reported as unchanged at 3.00% and 3.50%, respectively, marking the 17th consecutive month without a change.
The decision followed an earlier move to leave the seven-day reverse repo rate at 1.40%. The original report notes that targeted support measures had been announced in late September, with an emphasis on investment and the housing sector.
The unchanged Loan Prime Rates indicate that the authorities did not use this decision to make a broad adjustment to benchmark lending rates. However, policy support can also be delivered through targeted lending facilities, liquidity measures and changes to the structure of the monetary policy framework.
The original analysis cites discussion about the possibility of replacing the seven-day reverse repo rate with the overnight repurchase rate as the central bank’s main operational reference. Analysts reportedly suggested that such a change could reduce borrowing costs by the equivalent of approximately 15 basis points.
Any change to the operating framework would need to be assessed in terms of how it affects market pricing and the transmission of monetary policy. A technical adjustment to the reference rate does not automatically translate into a uniform reduction in borrowing costs across the economy.
For markets, the broader question remains whether monetary easing can improve credit demand and support the housing sector. Lower borrowing costs can help, but their effect may be limited if households and businesses remain cautious about the economic outlook.
UK Jobs Report — Tuesday
The UK employment report was better than expected in some respects, with the unemployment rate unexpectedly declining. However, the original analysis also highlighted a fall in payrolled employees and a significant decline in vacancies.
The vacancy decline was described as the largest since the beginning of 2026 and was attributed partly to smaller businesses facing higher labour costs. This suggests that the labour market may be showing signs of strain even if the headline unemployment rate appears relatively resilient.
The distinction between employment levels, payroll data and vacancies is important. A decline in vacancies can indicate that businesses are becoming more cautious about hiring, while a fall in payrolled employees may suggest that some employers are already reducing headcount.
The report did not materially alter the source analysis’s expectation that the Bank of England could tighten policy in November. Persistent inflation was still seen as a central concern, particularly in services and wage-sensitive components.
At the same time, the labour-market data add to the case for caution. If businesses are reducing hiring plans because of higher costs and uncertain demand, additional tightening could place further pressure on employment and investment.
The UK Autumn Budget therefore takes on added importance. Businesses will be assessing not only the direction of monetary policy but also the effect of taxation and other fiscal decisions on operating costs and confidence.
UK Inflation — Wednesday
UK headline CPI was reported at 3.5% year on year in September, approximately 40 basis points above the Bank of England’s cited forecast. The original report described this as a hawkish surprise that could strengthen expectations for a November rate increase.
Fuel prices were identified as a significant contributor to the headline increase. Other energy-related components also moved higher, while core measures rose more moderately.
Services inflation remains particularly important because it can reflect domestic demand, wage pressures and the pricing behaviour of businesses. The original analysis notes that services inflation was moving closer to 4%, making it an important measure for the Bank of England to monitor.
The airfares component was another point of uncertainty. An unusually large contribution from airfares can distort the interpretation of a monthly report, and any subsequent revision could affect the assessment of the underlying trend.
Nevertheless, the broader concern was that the inflation outlook could remain elevated into the winter period. Higher energy bills and other cost pressures could affect household budgets and business pricing decisions.
For the Bank of England, the challenge is to determine whether these pressures are likely to fade or become more persistent. A rate increase could help restrain demand and inflation expectations, but it would also increase borrowing costs for households and businesses.
The original report suggests that expectations for a tightening cycle could strengthen if inflation remains high. The eventual path will depend on the composition of inflation, the labour market and the effect of earlier policy decisions.
BoK Policy Announcement — Thursday
The Bank of Korea reportedly kept its Base Rate unchanged at 3.00% by a unanimous decision. The Bank opted to assess the effect of its previous rate increases amid uncertainty surrounding the Middle East and policy developments in major economies.
Despite leaving the rate unchanged, the original report describes the Bank’s stance as hawkish. It also notes that the BoK raised its growth expectations for the current year and the following year relative to earlier forecasts, while projecting higher inflation for the following year.
A stronger growth outlook can give policymakers more room to maintain a restrictive policy stance, particularly if inflation remains above their preferred path. However, the decision to hold also indicates that the Bank wants to assess how previous increases are affecting demand and financial conditions.
For the South Korean economy, external demand, trade conditions and developments in major economies remain important considerations. Uncertainty about energy prices and geopolitical conditions can also affect inflation and business confidence.
The unchanged decision demonstrates that a central bank can maintain a cautious approach even when its overall communication remains firm. The next moves will depend on whether growth and inflation evolve in line with the Bank’s revised projections.
UK Flash PMI — Friday
The UK’s preliminary purchasing managers’ indices were stronger than expected across the board in October, according to the original report. The survey results indicated the strongest growth rate since February.
The improvement was notable because the economy had been operating amid uncertainty ahead of the Autumn Budget. Businesses may have delayed investment or hiring decisions while awaiting clarity on taxation, spending and other fiscal measures.
Stronger PMI readings suggest that activity may have been more resilient than expected. However, surveys are not equivalent to official output data, and the details of new orders, employment, input costs and selling prices remain important.
For the Bank of England, a stronger activity backdrop alongside persistent inflation could make it more difficult to justify a rapid easing of policy. If demand remains firm and price pressures continue, the Bank may conclude that interest rates need to remain restrictive.
The original analysis suggests that the possibility of further tightening during 2027 was becoming more prominent in market discussions. That remains dependent on subsequent inflation and growth data rather than the PMI report alone.
The combination of resilient business activity and elevated prices is therefore an important theme heading into the new week. The Budget may also influence how businesses interpret the outlook for the coming months.
Eurozone Flash PMI — Friday
The eurozone PMI series was described in the original report as consistent with growth of approximately 0.3% quarter on quarter, slightly slower than the pace implied by September’s figures.
The overall picture suggested that the economy was expanding, but the performance of individual countries remained uneven. France was a particular concern, with the report indicating that headline measures had fallen into contraction.
French political and fiscal uncertainty could weigh on business confidence and investment. The original analysis also highlighted the possibility that recent bond-market volatility and civil unrest could affect future revisions to the survey results.
The eurozone outlook therefore presents a challenge for the ECB. The broader economy may be sufficiently resilient to withstand additional tightening, but weakness in France and other vulnerable areas could argue for a more cautious approach.
The report also referred to the possibility of renewed attention on the ECB’s Transmission Protection Instrument if French bond-market pressures persisted. However, the ECB’s ability to address country-specific fiscal concerns through monetary policy is limited.
The implications for the next policy decision will depend on the balance between inflation and growth. If inflation remains persistent despite moderate growth, the ECB may still consider tightening. If activity deteriorates more broadly, the case for further increases may weaken.
UK Retail Sales — Friday
UK retail sales were weaker than expected in September, according to the original report. The figures suggested that consumers remained cautious ahead of the Autumn Budget and amid concerns about energy bills and the broader cost of living.
Higher fuel costs were identified as one factor affecting spending. Relatively warm weather may also have delayed typical autumn purchases, illustrating how seasonal patterns can affect monthly retail data.
The result adds to the mixed picture from the UK economy. Employment and some business surveys have shown resilience, while consumer spending and business confidence remain vulnerable to price pressures and policy uncertainty.
Retail sales are important because household consumption accounts for a substantial part of economic activity. Persistent weakness could weigh on GDP and encourage businesses to take a more cautious approach to hiring and investment.
For the Bank of England, weaker spending may be relevant when assessing how restrictive policy is affecting demand. However, a single monthly release is unlikely to determine the policy outlook, particularly while inflation remains elevated.
The next phase of consumer spending will depend on real income growth, energy costs, borrowing conditions and the effect of the Budget on household confidence.
Japanese CPI — Friday
Japanese national CPI was reported in the original analysis to have risen to 2.1% year on year, compared with 1.9% previously. Core CPI also increased to 2.1% from 1.7%.
The report attributed the rise partly to persistent energy costs and a weaker yen, which increased import prices. The move above the BoJ’s 2% target provides another reason for policymakers to assess whether inflation is becoming more durable.
The source analysis suggests that the figures supported the case for further tightening, although no rate change was expected at the October meeting. Markets were reported to be pricing in a substantial probability of a rate increase in December.
The BoJ must determine whether inflation is being driven primarily by imported costs or whether wage growth and domestic pricing behaviour are supporting a more persistent trend. The distinction matters because the Bank’s policy framework is focused on achieving stable inflation over time rather than responding mechanically to every change in headline prices.
A sustained rise in wages and domestic demand could strengthen the case for normalising policy. If inflation is primarily imported and household purchasing power is weakening, the Bank may prefer a more gradual approach.
The yen and Japanese government bond yields will remain sensitive to changes in the expected policy path. A more confident inflation assessment could increase expectations for further tightening, while a cautious statement could reinforce the view that the Bank will move gradually.
Market Implications: Interest Rates, Bonds and Currencies
The week’s economic releases and central bank decisions will provide a broad test of the relationship between inflation and growth across major economies. The direction of interest rates will depend on the interaction of these factors rather than on any single data point.
For the United States, the FOMC announcement and PCE inflation release will be central. If economic activity remains resilient while inflation proves persistent, investors may expect restrictive policy to remain in place for longer. If inflation moderates and growth loses momentum, expectations may shift towards a more cautious approach.
In Canada and New Zealand, the policy decisions will reveal how policymakers are weighing inflation expectations against growth risks. The BoC’s updated projections and the RBNZ’s assessment of the latest CPI data will be particularly important in determining whether further tightening is likely.
The ECB’s decision will be interpreted in the context of both inflation and uneven economic performance. France’s fiscal situation adds another dimension, because sovereign bond spreads can respond to political and fiscal developments independently of the broader monetary policy outlook.
In Japan, the BoJ’s inflation assessment will be closely watched for clues about the timing of further policy normalisation. A more confident view of underlying inflation could support expectations for additional rate increases, although the pace of adjustment will depend on wages and economic activity.
Government bond markets will focus on changes in expected policy rates, inflation expectations and the perceived risks to growth. Shorter-dated yields are often especially sensitive to central bank expectations, while longer-dated yields also reflect fiscal developments and the outlook for economic growth.
Currency markets will compare the relative policy paths of different central banks. A central bank does not necessarily need to raise rates to support its currency; it may be enough for its communication to be more restrictive than markets had anticipated. Conversely, a rate increase that is fully priced in may produce a limited response if policymakers signal that the move is likely to be the last for some time.
Equity markets will face a similarly mixed set of influences. Strong growth can support corporate earnings, while higher yields may weigh on valuations. Persistent inflation can also affect profit margins if businesses are unable to pass higher costs on to customers.
The most important distinction is between the policy decision itself and the signal it sends about the future. Markets are forward-looking, so an unexpected change in guidance can be more influential than a decision that matches consensus.
Investors should therefore assess the week’s events by comparing actual results with expectations, examining the composition of the data and considering how each release changes the outlook for monetary policy.
Conclusion: The Key Events to Watch
The Economic Report for 26–30 October 2026 centres on five central bank decisions, US GDP and PCE inflation, and a series of important regional economic releases. The FOMC, BoC and RBNZ decisions on Wednesday will set the tone for the first part of the week, while the ECB, US GDP and PCE releases on Thursday will provide further information about inflation and growth. The BoJ announcement and European and Canadian data will close the week.
For the Federal Reserve, the key question is whether inflation is moderating sufficiently to provide greater policy flexibility. The BoC and RBNZ will need to weigh persistent price pressures against the risks of slowing activity. The ECB must balance inflation concerns with uneven growth and French fiscal uncertainty, while the BoJ will assess whether inflation is becoming sustainable enough to justify further policy normalisation.
The central theme is the interaction between economic momentum and price stability. Strong growth does not automatically imply higher interest rates, and a softer inflation reading does not guarantee an easing of policy. The details of the data and the response from policymakers will determine how expectations evolve.
With so many important releases concentrated into a short period, the relative differences between central banks may be as significant as the individual decisions. Markets will be looking for evidence that clarifies the direction of interest rates and the broader economic outlook.
Editorial Note and Disclaimer
This report summarises scheduled economic releases, policy expectations and market commentary based on the information available when the analysis was prepared. Forecasts, consensus estimates and market-implied probabilities may change as new information becomes available. They should not be interpreted as confirmed outcomes or guarantees of future central bank decisions.
Economic indicators may be revised, and individual data releases can produce market reactions that differ from expectations. Readers should consider the broader economic context and the possibility of uncertainty when interpreting the analysis.
This article is provided for informational and educational purposes only. It does not constitute investment advice, a recommendation to buy or sell any financial instrument, or a solicitation to enter into any transaction. Readers should make their own assessments and consult a suitably qualified financial professional where appropriate.
Clock-change note: UK clocks go back on Sunday, 25 October 2026. US clocks change on Sunday, 1 November 2026. During the intervening week, London and New York will be four hours apart rather than the usual five-hour difference. Readers should verify the local time of scheduled data releases and central bank announcements before planning around them.