
Table of Contents
- Economic Report: Key Events for 14–18 September 2026
- Economic Report: The FOMC and Fed Take Centre Stage
- Why the September FOMC Meeting Matters
- Inflation Remains Central to Fed Policy
- The Labour Market Provides the Other Side of the Fed’s Mandate
- The September Economic Projections
- Fed Communication Could Matter More Than the Decision
- Oil Prices and the Fed’s Inflation Outlook
- What the FOMC Could Mean for Markets
- Economic Report: UK Inflation Sets the Stage for the BoE
- Economic Report: BoJ Policy Normalisation Remains in Focus
- Economic Report: Canada, China and Other Key Data
- Economic Report: The Week in Review
- Economic Report: What Matters Most for Markets Next Week
- Economic Report: What Investors Should Watch
- Economic Report: A Week Defined by Monetary Policy
- Economic Report: Key Takeaways
- Frequently Asked Questions
- What are the most important economic events for September 14–18, 2026?
- When is the September 2026 FOMC decision?
- Why is the September FOMC meeting important?
- What will the Fed consider before its September decision?
- When is the September 2026 BoE decision?
- Will the Bank of England raise interest rates in September 2026?
- Why is UK inflation important for the BoE?
- When is the September 2026 BoJ decision?
- Why is Japanese CPI important for the BoJ?
- How could the FOMC decision affect financial markets?
- Final Economic Report Outlook
Economic Report — The week of 14–18 September 2026 brings an unusually concentrated set of economic and monetary-policy events, with the Federal Reserve, Bank of England and Bank of Japan all in focus alongside a substantial run of inflation, employment, consumer spending and industrial data.
The FOMC decision will be the central event for global markets during the first half of the week, followed shortly afterward by the BoE and BoJ decisions. The sequencing is important. UK inflation is due immediately before the Bank of England meeting, while Japanese inflation arrives close to the Bank of Japan’s policy decision. That creates a week in which fresh economic data could influence expectations almost immediately rather than simply shaping the outlook for subsequent meetings.
The broader monetary policy backdrop is complicated by renewed energy-price pressure, geopolitical uncertainty, changing expectations for interest rates and increasingly divergent economic conditions across the major economies. For the Fed, the balance between inflation and labour-market conditions remains central. For the BoE, the challenge is assessing whether higher energy costs will produce a temporary inflation increase or broader second-round effects. For the BoJ, the question is how quickly monetary policy should continue moving away from an accommodative stance.
The week also includes Canadian CPI, Chinese activity data, UK employment figures, US retail sales, euro-area inflation, Japanese CPI, UK retail sales, US industrial production and the ECOFIN meeting.
The result is a dense economic calendar in which individual releases could influence interest-rate expectations, government bond yields, currencies and broader financial conditions.
Economic Report: Key Events for 14–18 September 2026
The most important events of the week are spread across all five trading days, but the concentration of central-bank decisions from Wednesday through Friday makes the second half of the week particularly significant.
Monday: Canadian CPI
Canada’s August CPI report begins the week and will provide another indication of how persistent inflation pressures are becoming.
The report is particularly relevant because gasoline and energy prices have been an important source of recent inflation volatility. Policymakers at the Bank of Canada will need to distinguish between temporary energy-driven movements and evidence that inflation is becoming more broadly embedded.
The Canadian labour market has also shown signs of losing momentum, creating a policy balance between inflation risks and weaker employment conditions.
Tuesday: Global Activity and Labour-Market Data
Tuesday brings Chinese industrial production, retail sales and fixed-asset investment, alongside UK employment data, the German ZEW survey and Indian trade data.
The Chinese releases will provide an important read on the balance between external and domestic demand. Strong export performance has contrasted with softer domestic consumption and investment, making the composition of Chinese growth increasingly important for the global outlook.
UK employment data will also receive attention ahead of Wednesday’s inflation report and Thursday’s BoE decision.
Wednesday: FOMC, US Retail Sales and UK Inflation
Wednesday is the most concentrated day of the week.
The FOMC will announce its policy decision and publish updated economic projections. The meeting is particularly important because the Federal Reserve’s outlook for inflation, employment and interest rates will determine whether current market expectations are sustainable.
US retail sales will provide an additional indication of consumer resilience.

At the same time, UK CPI will be released ahead of the BoE meeting. The inflation data could therefore have an immediate influence on expectations for Thursday’s policy decision.
Thursday: BoE Decision
The Bank of England takes centre stage on Thursday.
The market focus will extend beyond the headline Bank Rate decision to the MPC voting split, the language surrounding inflation and energy prices, and the annual quantitative-tightening decision.
The composition of the vote may be particularly important because a change in the balance between members favouring a hold and those preferring a rate increase could influence expectations for subsequent meetings.
Friday: BoJ and Japanese CPI
Friday concludes the week with the Bank of Japan’s decision and Japanese inflation data.
The BoJ is assessing whether the Japanese economy can sustain further policy normalisation while inflation remains above the levels seen during the country’s previous low-inflation period.
The combination of the inflation data, the policy decision and Governor Ueda’s communication will be closely watched by the foreign-exchange market, particularly because the yen remains sensitive to changes in the expected interest-rate differential between Japan and the United States.
Economic Report: The FOMC and Fed Take Centre Stage
The FOMC is the most important monetary-policy event on the calendar this week.
The Federal Reserve’s September 15–16 meeting includes a fresh set of economic projections, making the event more significant than a standard policy meeting. The decision itself will matter, but the projections, rate expectations and Chair’s communication may have an even greater influence on markets.
The Fed has been operating against an unusually complex combination of inflation uncertainty, labour-market developments, energy-price volatility and changes in financial conditions.
The central question is whether the latest inflation data justify a more restrictive policy stance or whether the broader economic picture argues for patience.
Why the September FOMC Meeting Matters
The FOMC meeting comes at a point when market expectations have become particularly sensitive to incoming economic data.
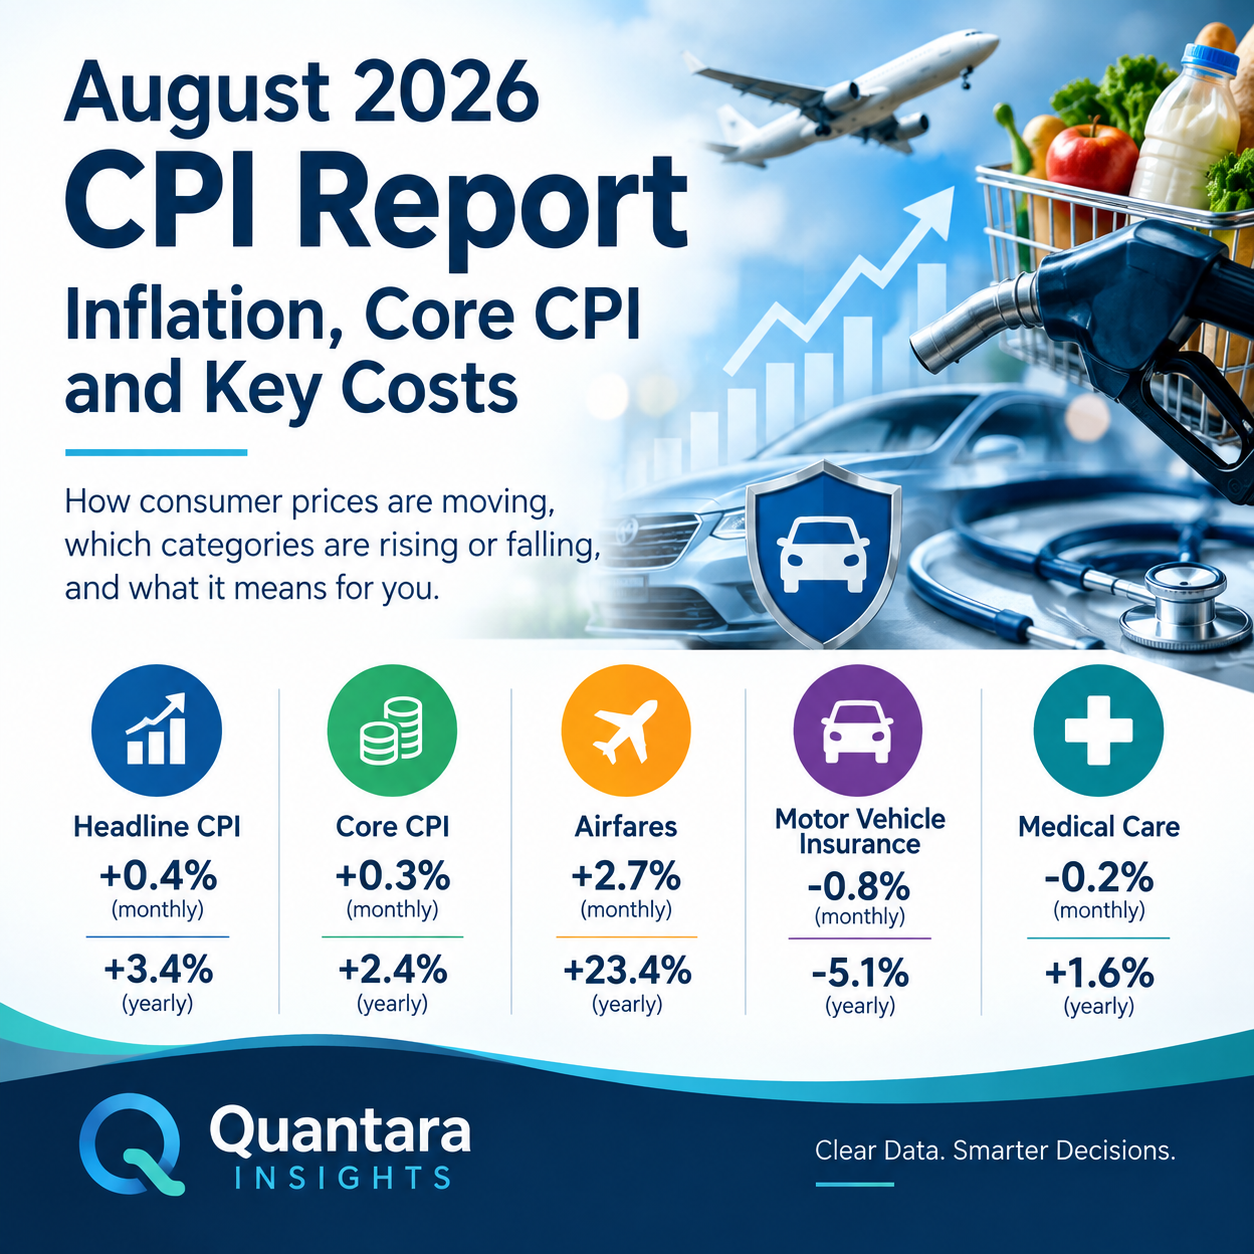
The August CPI report showed stronger-than-expected core inflation on a monthly basis, increasing expectations for a possible rate increase. At the same time, the labour market has remained more resilient than some previous data had suggested.
That combination gives the Fed greater flexibility.
If inflation remains above target while employment remains relatively firm, policymakers have more scope to maintain or increase restrictive policy. Conversely, if inflation pressures are judged to be temporary and labour-market conditions deteriorate, the case for caution becomes stronger.
The market therefore enters the meeting with a focus not only on the immediate decision but on how policymakers assess the balance of risks.
Inflation Remains Central to Fed Policy
Inflation remains one of the most important considerations for the Federal Reserve.
The latest US inflation figures showed core CPI rising more strongly than expected on a monthly basis. While the annual rate remained comparatively contained, the monthly acceleration raised questions about whether progress toward the Fed’s inflation objective could become less consistent.
The composition of inflation is also important.
A renewed increase in non-housing services inflation would be more concerning for policymakers than a temporary increase in energy prices. Services inflation can be more persistent because it is closely linked to wages, demand and business pricing behaviour.
Energy prices nevertheless complicate the outlook.
Higher oil prices can directly increase headline inflation while also raising transportation, production and distribution costs. The key question for central banks is whether those effects remain concentrated in energy-related categories or spread into broader consumer prices.
The Labour Market Provides the Other Side of the Fed’s Mandate
The labour market remains equally important.
Recent employment data have shown more resilience than earlier estimates suggested. Payroll growth was stronger than expected, while revisions also improved the underlying picture.
That matters because a resilient labour market reduces the immediate need for the Fed to provide support through lower interest rates.
At the same time, employment indicators need to be interpreted carefully. Monetary policy works with a lag, meaning that a labour market that currently appears healthy may still respond to earlier restrictive policy.
The FOMC therefore faces a familiar policy problem: inflation may require restraint, but excessive restraint could eventually weaken employment and economic growth.
The September Economic Projections
The Summary of Economic Projections will be one of the most closely watched parts of the meeting.
Investors will assess how policymakers have changed their forecasts for:
- Economic growth
- Unemployment
- Inflation
- The policy rate
- Longer-run interest rates
The distribution of individual rate projections can be particularly important because it provides information about how policymakers view the appropriate path for interest rates.
A relatively hawkish set of projections could reinforce higher Treasury yields and support the dollar. A more cautious projection profile could have the opposite effect.
The market will therefore look beyond the headline rate decision and assess whether the Fed’s internal outlook has changed.
Fed Communication Could Matter More Than the Decision
When a policy meeting is closely anticipated, the accompanying communication can become more important than the decision itself.
The statement, projections and press conference can clarify how policymakers interpret the inflation data and whether the current policy setting is sufficiently restrictive.
Investors will also look for any discussion of financial conditions.
Higher bond yields, wider credit spreads or tighter lending conditions can influence economic activity even without a change in the policy rate. If financial conditions have already tightened materially, policymakers may judge that markets are doing part of the work for them.
This is particularly relevant when long-term Treasury yields are rising because of stronger growth expectations, higher term premiums, increased government borrowing or other market forces.
Oil Prices and the Fed’s Inflation Outlook
Energy prices are an additional complication.
Higher crude prices increase headline inflation directly, but the greater concern is whether businesses begin passing higher costs through to consumers.
That process can occur through transportation, airfares, logistics, manufacturing and other services.
The Federal Reserve cannot directly control the price of oil. Its policy response therefore depends on whether the energy shock remains temporary or becomes embedded in inflation expectations and wage-setting behaviour.
If policymakers believe the shock is temporary, they may look through some of the headline impact. If they see evidence of broader pass-through, the policy response could become more restrictive.
What the FOMC Could Mean for Markets
The immediate market reaction is likely to be concentrated in US Treasury yields, the dollar and interest-rate futures.
A more hawkish FOMC could push front-end Treasury yields higher and support the US dollar, particularly against currencies whose central banks are expected to remain more accommodative.
A more dovish interpretation could lower short-term yields and weaken the dollar.
Equity markets may respond in a more complicated way because lower expected rates can support valuations while a hawkish decision could reinforce concerns about financial conditions.
The important distinction will therefore be between the policy decision itself and the policy path implied by the projections.
Economic Report: UK Inflation Sets the Stage for the BoE
The Bank of England faces its own difficult policy balance.
The BoE is entering the September meeting with inflation still above target, while economic growth and labour-market conditions provide reasons for caution.
The latest policy decision left Bank Rate at 3.75%, with the MPC voting 6–3 to hold and three members favouring a 25-basis-point increase.
That voting pattern is important because it demonstrates that the committee is not uniformly comfortable with the current policy stance.
UK CPI Is the Critical Data Release
The UK inflation report on Wednesday arrives immediately before Thursday’s policy decision.
That timing makes the release unusually important.
If inflation is stronger than expected, particularly if core inflation or services inflation accelerates, the argument for maintaining or increasing restrictive policy could strengthen.
If inflation is softer, the case for maintaining the existing rate becomes easier to defend.
Energy prices are likely to remain an important part of the discussion.
Higher energy costs can increase household bills directly and raise business costs indirectly. The BoE’s challenge is determining whether those increases will remain temporary or result in broader price pressures.
The BoE Voting Split
The MPC voting split will be one of the most important details to watch.
The previous meeting produced a 6–3 vote in favour of maintaining Bank Rate, with three members voting for a 25-basis-point increase.
A change in that balance could be interpreted as an important signal about the future policy path.
For example, a move toward a more evenly divided committee could increase expectations for a future rate increase. A more unified vote to hold could reduce immediate tightening expectations.
The vote therefore provides information that the headline Bank Rate alone cannot capture.
Energy Prices Create a Difficult Policy Environment
The UK economy is particularly sensitive to household energy costs because they have a direct effect on disposable income.
Higher energy prices can reduce consumer spending while simultaneously increasing measured inflation.
That creates a difficult situation for the BoE.
If policymakers respond too aggressively to an energy-driven inflation increase, they risk placing additional pressure on economic activity. If they respond too cautiously and inflation spreads into wages and services, they risk allowing inflation expectations to become less firmly anchored.
The MPC therefore has to evaluate both the size and persistence of the shock.
Quantitative Tightening Remains Important
The September meeting also includes the annual review of the BoE’s quantitative-tightening programme.
The market will pay attention to the size and composition of planned gilt sales and maturities.
Quantitative tightening operates differently from changes in Bank Rate, but it can still affect financial conditions by changing the supply of government bonds held by the private sector.
The interaction between QT, government borrowing requirements and long-term gilt yields will therefore remain relevant.
What the BoE Means for Sterling
Sterling’s reaction will depend heavily on the combination of the rate decision, vote split and forward guidance.
A hawkish hold could support sterling even if Bank Rate remains unchanged.
Conversely, a decision to hold accompanied by a more cautious assessment of inflation could reduce expectations for future tightening and weigh on the pound.
The distinction between the headline decision and the underlying policy message will therefore be important.
Economic Report: BoJ Policy Normalisation Remains in Focus
The Bank of Japan concludes the week’s major central-bank sequence.
The BoJ meeting is scheduled for 17–18 September, with the policy rate currently around 1%.
Japan remains in a different monetary-policy position from the United States and United Kingdom.
While the Fed and BoE are focused on how restrictive policy should remain, the BoJ is still assessing the appropriate pace for moving away from its historically accommodative stance.
Why the BoJ Matters
The Japanese policy outlook has become increasingly important for global markets because changes in Japanese interest rates can influence capital flows and currency markets.
For years, the yen was associated with very low domestic interest rates, encouraging investors to seek higher returns elsewhere.
As Japanese rates rise, the relative attractiveness of those strategies can change.
That makes every shift in BoJ expectations relevant beyond Japan itself.
Japanese CPI Before the Decision
Japanese inflation data are particularly important because they arrive close to the policy meeting.
Core CPI is expected to remain relatively stable, but the market will look beyond the headline annual rate for evidence of underlying price pressure.
The BoJ will want to assess whether inflation is becoming increasingly broad-based rather than being driven primarily by temporary energy or government-policy effects.
Higher producer prices and input costs could eventually feed through to consumer prices, but the strength of that pass-through remains uncertain.
The Yen and Interest-Rate Differentials
The yen remains highly sensitive to changes in the expected interest-rate gap between Japan and the United States.
If the Fed adopts a more hawkish stance while the BoJ remains cautious, the US-Japan yield differential could remain supportive of the dollar.
If the BoJ becomes more hawkish at the same time that the Fed signals greater caution, the relative advantage of US rates could narrow.
That combination could produce a meaningful change in foreign-exchange expectations.
Currency Policy Adds Another Dimension
Japanese policymakers are also conscious of the exchange rate.
A weak yen can increase import costs, particularly for energy and commodities. That can contribute to domestic inflation and complicate the BoJ’s assessment of underlying price trends.
At the same time, policymakers must avoid giving the impression that monetary policy is being used solely to target the currency.
The key issue is therefore how the exchange rate interacts with inflation, wages, consumption and economic activity.
Economic Report: Canada, China and Other Key Data
The week contains a substantial amount of economic information beyond the three major central-bank decisions.
Canadian CPI
Canadian CPI is released on Monday.
The previous report showed headline inflation at 3.0% year over year, with gasoline and travel-related prices contributing to the increase.
The August release will provide another test of whether the acceleration is broadening.
The Bank of Canada will be particularly interested in core inflation and measures of underlying price pressure because headline energy movements can be volatile.
The labour market adds another consideration. If employment conditions weaken while inflation remains elevated, the Bank of Canada could face a difficult policy trade-off similar to those confronting other central banks.
Chinese Activity Data
China’s August activity figures will include industrial production, retail sales and fixed-asset investment.
The central theme remains the divergence between external and domestic demand.
Exports have remained comparatively strong, supported by global technology demand and other external factors. Domestic consumption and investment, however, have continued to show signs of weakness.
Retail sales will therefore be especially important.
A stronger consumer sector would provide evidence that policy support is beginning to translate into domestic demand. A weak reading could reinforce expectations for additional fiscal or monetary support.
UK Employment
UK labour-market data will be released ahead of CPI and the BoE decision.
The unemployment rate, employment growth and wage data will all matter.
For the BoE, wage growth remains particularly relevant because persistent services inflation can be linked to labour costs.
A resilient labour market accompanied by elevated wage growth would strengthen the argument for maintaining restrictive policy.
A clear deterioration could encourage policymakers to place greater emphasis on the downside risks to growth.
US Retail Sales
US retail sales will provide a fresh assessment of consumer spending.
Consumer demand remains one of the most important supports for the US economy.
A strong retail-sales report would suggest that households remain capable of absorbing relatively restrictive financial conditions.
A weak result could indicate that higher borrowing costs and other pressures are beginning to affect consumption.
The market reaction will depend not only on the headline number but on its composition, particularly the performance of discretionary categories and sales excluding volatile components.
Brazilian Monetary Policy
Brazil’s central bank is expected to remain active in managing inflation and economic activity.
The policy outlook reflects the interaction between domestic demand, inflation expectations and the level of real interest rates.
A further rate reduction would represent continued movement toward less restrictive policy, although the pace of easing would remain dependent on inflation developments.
Brazil therefore provides another example of how emerging-market central banks are navigating the balance between inflation control and economic growth.
Economic Report: The Week in Review
The previous week provided several important developments that shape the outlook for 14–18 September.
OPEC+ and Oil Supply
OPEC+ maintained October production targets, pausing additional increases after completing the rollback of earlier voluntary reductions.
The focus is increasingly shifting toward 2027 production quotas and the capacity assessments that will influence future baselines.
For financial markets, however, the headline production target is only part of the story.
Actual physical supply can differ from official quotas because of geopolitical disruptions, infrastructure constraints and transportation problems.
That distinction is particularly relevant when disruptions affect major shipping routes.
For central banks, sustained energy-price increases represent a potential inflation risk, even if monetary policy cannot directly influence global oil supply.
German State Elections
The strong performance of the AfD in Saxony-Anhalt was another important political development.
Although regional elections do not directly determine national economic policy, the results can influence political expectations and the future balance of power.
For financial markets, the more immediate significance lies in what the results imply for the stability of Germany’s governing coalition and the broader European political environment.
Swedish Inflation
Swedish CPIF inflation was softer than expected, supporting the view that the Riksbank may remain on hold.
The report reduced some of the pressure for additional tightening, although policymakers continue to monitor the possibility of renewed inflation later in the year.
The Swedish experience highlights the importance of distinguishing between temporary inflation fluctuations and sustained changes in underlying price pressure.
Japanese GDP
Japan’s second-quarter GDP was revised higher, with growth remaining positive for a third consecutive quarter.
The revision was supported by stronger capital expenditure data, while household consumption remained comparatively subdued.
The result provides some evidence of economic resilience and is relevant to the BoJ’s assessment of whether the economy can tolerate further policy normalisation.
Chinese Trade
Chinese exports remained strong in August, while imports also increased.
The resulting trade surplus remained substantial.
The strength of exports contrasts with softer domestic demand and continues to highlight the uneven composition of China’s economic growth.
Technology-related exports remain an important source of external demand, while consumer spending and investment are being watched for signs of broader recovery.
US Treasury Long-End Buybacks
The US Treasury’s long-end buyback programme attracted attention from the bond market.
The Treasury purchased less than the maximum amount announced in the 10–20-year operation.
The result illustrates the importance of auction and buyback mechanics in determining the actual impact of government debt operations.
Markets will also watch subsequent operations for evidence of whether demand and pricing conditions change.
ECB Policy
The European Central Bank’s policy decision reinforced the importance of inflation and growth projections in determining the future path of European monetary policy.
The ECB retained a data-dependent approach, while updated projections provided additional information about how policymakers view inflation and economic activity.
The key question for investors is whether the euro-area economy can tolerate further tightening without creating a material deterioration in growth.
CBRT Policy
Turkey’s central bank maintained its policy rate, while acknowledging that underlying inflation conditions had been improving.
The Bank continues to monitor energy prices and geopolitical developments as potential upside risks.
The Turkish example demonstrates how external energy shocks can complicate disinflation even when domestic demand is relatively weak.
Norwegian Inflation
Norwegian inflation data were mixed.
Headline inflation remained elevated on an annual basis, while underlying measures were more consistent with the central bank’s projections.
The data leave the Norges Bank facing a two-sided policy environment as it assesses whether inflation is moving sustainably toward target.
UK GDP
UK GDP growth was stronger than expected in July.
The performance of services was an important component of the increase, while production and construction remained more subdued.
The stronger activity data provide some support for the economic outlook but do not necessarily determine the BoE’s September decision because inflation remains the more immediate policy concern.
US PPI
US producer prices accelerated in August, although core measures were more restrained.
Energy prices accounted for a significant portion of the increase in goods prices.
That composition matters because a large energy contribution does not necessarily indicate broad-based inflation.
However, continued energy inflation could eventually affect services and consumer prices if businesses pass higher input costs through to customers.
US CPI
US CPI was the most important inflation report of the previous week.
Core CPI increased more strongly than expected on a monthly basis, while the annual rate remained relatively stable.
The increase in supercore inflation was also notable because policymakers closely monitor services categories that are less directly influenced by energy and housing.
The data shifted market expectations toward a more restrictive Fed outcome.
The September FOMC meeting will therefore provide an important test of whether policymakers share the market’s interpretation of the latest inflation data.
Economic Report: What Matters Most for Markets Next Week
The most important feature of the week is not any single economic release.
It is the interaction between several policy decisions.
Central-Bank Divergence
The Fed, BoE and BoJ are approaching monetary policy from different starting points.
The Fed is balancing inflation against labour-market conditions.
The BoE is dealing with above-target inflation alongside weaker growth risks.
The BoJ is continuing a gradual process of policy normalisation.
This divergence creates opportunities and risks across global bond and currency markets.
Inflation Versus Growth
All three central banks face some version of the same question:
How much inflation can be tolerated without unnecessarily damaging economic growth?
The answer differs because each economy has different inflation dynamics, labour-market conditions and policy settings.
For investors, the key is therefore not simply whether inflation is rising or falling, but whether policymakers believe the underlying trend is consistent with their inflation objectives.
Energy Prices and Second-Round Effects
Energy prices have become a common theme across the global monetary-policy outlook.
The initial increase in oil and gas prices is relatively straightforward to measure.
The more difficult question is what happens afterward.
If higher energy prices increase transport and production costs, businesses may raise prices. Workers may then seek compensation for higher household costs, potentially creating a second-round inflation effect.
Central banks are watching for exactly this process.
Bond Yields and Financial Conditions
Government bond yields have remained sensitive to inflation expectations, central-bank policy and fiscal developments.
Long-term yields can rise even when central banks do not change policy rates.
That matters because higher long-term yields tighten financial conditions for households, companies and governments.
The Fed, BoE and other central banks therefore have to consider the broader financial environment rather than focusing exclusively on their own policy rates.
Currency Markets
The dollar, pound and yen will all be highly sensitive to this week’s policy decisions.
For the dollar, the FOMC outlook is the immediate driver.
For sterling, the key variables are UK inflation, the MPC vote and the BoE’s assessment of energy-related risks.
For the yen, the BoJ’s policy decision and the evolving US-Japan rate differential will remain central.
Currency markets may therefore respond more strongly to changes in expected policy paths than to the headline rate decisions themselves.
Economic Report: What Investors Should Watch
There are several practical indicators to monitor throughout the week.
Watch the FOMC Rate Decision and Projections
The Fed’s updated projections could provide more information than the rate decision alone.
Investors should focus on changes in inflation and unemployment forecasts, as well as the distribution of projected policy rates.
Watch the BoE Voting Split
The MPC vote will provide an important indication of how divided the committee has become.
A shift toward more hawkish votes would reinforce expectations for tighter policy.
A more unified hold could reduce immediate rate-hike expectations.
Watch the BoJ’s Forward Guidance
For Japan, the wording around future policy normalisation will be crucial.
The market will want to know whether the BoJ considers current economic conditions sufficient to justify further increases and whether policymakers are becoming more confident about underlying inflation.
Watch Inflation Composition
Headline inflation can sometimes obscure the underlying trend.
Investors should therefore pay particular attention to:
- Core inflation
- Services inflation
- Wage-sensitive components
- Energy-related categories
- Goods prices
- Measures of underlying inflation
Watch Bond Markets
The bond market will provide an important real-time indication of how investors interpret the policy decisions.
Short-term yields will respond primarily to changes in expected central-bank policy.
Long-term yields will also reflect inflation expectations, fiscal policy, term premiums and demand for government debt.
Watch the Dollar, Pound and Yen
The three major currencies could respond differently depending on the relative hawkishness of the respective central banks.
The most important question will be whether the expected policy path changes.
Economic Report: A Week Defined by Monetary Policy
The week of 14–18 September brings together many of the issues that currently define the global economic outlook.
The FOMC and Fed will be assessing whether stronger inflation data and resilient employment justify maintaining a restrictive policy stance.
The BoE will receive fresh UK inflation data immediately before its policy meeting, placing renewed attention on the balance between inflation persistence, energy costs and weaker economic growth.
The BoJ will assess whether the Japanese economy can support another step toward monetary-policy normalisation as inflation remains relatively firm and the yen continues to influence imported price pressures.
At the same time, Canada, China, Europe and emerging markets will provide additional information about the global economic cycle.
The common theme is the changing relationship between inflation and growth.
Central banks cannot directly control energy prices, geopolitical developments or global trade conditions. Their role is to determine how monetary policy should respond to the second-round effects of those developments.
That distinction will remain particularly important this week.
If energy prices remain elevated but broader inflation stays contained, policymakers may be able to look through part of the shock.
If higher energy costs begin feeding into wages, services and inflation expectations, the policy response could become more restrictive.
For markets, the implications extend across bonds, currencies and equities.
The most important reactions may not come from the headline rate decisions. Instead, investors will be looking for changes in the expected path of policy, the tone of central-bank communication, voting splits and updated economic projections.
The sequence of events is also important.
The FOMC comes first, followed by the BoE and then the BoJ. That creates the potential for one central-bank decision to influence expectations for another, particularly through changes in global bond yields and foreign-exchange markets.
The September week therefore provides an unusually useful snapshot of the global monetary-policy landscape.
The key issue is not simply whether rates move.
It is how policymakers assess the persistence of inflation, the resilience of economic growth and the degree of financial restraint already present in their respective economies.
Economic Report: Key Takeaways
- The FOMC is the week’s main US monetary-policy event, with the decision accompanied by updated economic projections.
- Fed policy remains highly dependent on inflation and labour-market data, particularly after stronger-than-expected core inflation.
- The BoE decision follows UK CPI by one day, making the inflation report particularly important for expectations.
- The BoE voting split will be a key signal, alongside the Bank’s assessment of energy-related inflation risks.
- The BoJ meets on September 17–18, with markets assessing the pace of Japanese policy normalisation.
- Japanese inflation and the yen remain important to the BoJ outlook, particularly because imported energy prices can affect domestic inflation.
- Canadian CPI will provide another test of inflation persistence ahead of future Bank of Canada decisions.
- Chinese activity data will help assess the strength of domestic demand, particularly consumer spending and investment.
- US retail sales will provide an important read on consumer resilience.
- Bond yields remain sensitive to monetary policy, inflation, fiscal developments and energy prices.
- The dollar, pound and yen could experience increased volatility as expectations for relative monetary policy change.
- The central theme across the week is the balance between inflation persistence and economic growth.
Frequently Asked Questions
What are the most important economic events for September 14–18, 2026?
The most important events include the FOMC decision and economic projections, UK CPI, the BoE policy decision, the BoJ policy decision, Japanese CPI, Canadian CPI, Chinese activity data and US retail sales.
When is the September 2026 FOMC decision?
The September FOMC meeting is scheduled for September 15–16, with the policy decision and press conference taking place on September 16.
Why is the September FOMC meeting important?
The meeting includes updated economic projections, making the event important for understanding how Federal Reserve officials view inflation, employment, economic growth and the future path of interest rates.
What will the Fed consider before its September decision?
The Fed will assess inflation, labour-market conditions, economic growth, financial conditions and developments in energy prices. The composition and persistence of inflation will be particularly important.
When is the September 2026 BoE decision?
The Bank of England’s Monetary Policy Committee is scheduled to announce its September policy decision on Thursday, September 17.
Will the Bank of England raise interest rates in September 2026?
The decision will depend on the inflation and economic data available to the MPC. The previous meeting produced a divided vote, making the September voting split and guidance particularly important.
Why is UK inflation important for the BoE?
UK inflation is a central part of the Bank of England’s monetary-policy mandate. Higher inflation, particularly persistent services inflation, can increase the need for restrictive policy.
When is the September 2026 BoJ decision?
The Bank of Japan’s September monetary policy meeting is scheduled for September 17–18, with the outcome due on the second day of the meeting.
Why is Japanese CPI important for the BoJ?
Japanese CPI provides evidence about the persistence and breadth of domestic inflation. The BoJ uses inflation, wages, economic activity and financial conditions when assessing the appropriate pace of policy normalisation.
How could the FOMC decision affect financial markets?
A more hawkish Fed could support US Treasury yields and the dollar while tightening broader financial conditions. A more cautious Fed could have the opposite effect, although the market reaction would also depend on the updated economic projections and press conference.
Final Economic Report Outlook
The week ahead combines three major central-bank decisions with a broad range of inflation, employment, spending and industrial data.
The FOMC, Fed, BoE and BoJ will all be assessed through the same broad market question: how should monetary policy respond when inflation remains sensitive to energy prices while economic growth and labour-market conditions are becoming increasingly uneven?
For investors, the answer will depend less on individual headline figures and more on how policymakers interpret the wider trend.
Inflation persistence, labour-market resilience, energy-price pass-through, bond yields and currency movements will all be relevant.
The most important market signals may therefore come from the details surrounding each decision — the FOMC projections, the BoE vote and guidance, and the BoJ’s assessment of future policy normalisation.
Taken together, these developments should provide a clearer indication of how the world’s major central banks are positioning monetary policy for the final months of 2026.