Table of Contents
- Why Earnings Season Starts With the Banks
- JPMorgan Chase: A Broad Banking Franchise Under the Spotlight
- Wells Fargo: Net Interest Margins and Growth Remain Central
- Goldman Sachs: Capital Markets Activity and Revenue Comparisons
- Citigroup: A Useful Comparison for the Banking Sector
- Bank of America: Net Interest Income and Fee Growth
- What the Major Banks Have in Common
- The Economic Signals Investors Should Watch
- How to Read Bank Earnings Beyond the Headline Numbers
- Other Companies Reporting During the Week
- What Could Move Bank Stocks After Earnings?
- A Practical Checklist for Investors
- Conclusion: What Earnings Season Could Reveal About the Banks
- Frequently Asked Questions
- When does Earnings Season begin for the major banks in October 2026?
- Which banks are the main focus this week?
- What should investors watch in JPMorgan’s earnings report?
- Why are net interest margins important for Wells Fargo?
- What matters most in Goldman Sachs’ earnings report?
- Can a bank stock fall after beating earnings expectations?
- How do bank earnings help investors understand the economy?
- Do strong bank earnings guarantee that bank stocks will rise?
- What is the difference between earnings estimates and reported results?
- Why should investors compare more than earnings per share?
Earnings Season begins with investors turning their attention to America’s largest banks, as JPMorgan Chase, Wells Fargo, BlackRock, Goldman Sachs and Citigroup prepare to report third-quarter 2026 financial results. Their earnings will provide an important assessment of lending activity, investment banking demand, trading revenue, consumer credit conditions and the broader health of the financial sector.
The opening bank reports arrive at a time when investors are weighing the effects of higher Treasury yields, changing interest-rate expectations, resilient consumer spending and a more complicated outlook for credit growth. While major financial institutions have benefited from active capital markets and stronger fee-generating businesses, the sustainability of those gains remains a central question.
For investors, this week’s results will be about more than whether individual companies beat or miss analysts’ estimates. Management commentary on net interest income, deposit costs, loan demand, expenses and credit provisions could have a meaningful influence on how markets assess the banking industry’s prospects for the remainder of the year.
JPMorgan Chase, Wells Fargo and Goldman Sachs offer three different perspectives on the sector. JPMorgan combines consumer banking, corporate lending, payments and investment banking. Wells Fargo’s performance provides insight into traditional banking, loan growth and net interest margins. Goldman Sachs offers a closer look at capital markets, advisory activity, trading and wealth management.
Citigroup and Bank of America will add further context, helping investors compare business models and determine whether the industry’s recent earnings momentum is broad-based or concentrated in particular areas.
The week also includes reports from healthcare companies, semiconductor businesses and other major corporations. These results may influence broader market sentiment, but the primary focus remains on what the banks reveal about financial conditions, corporate activity and the resilience of the U.S. economy.
Why Earnings Season Starts With the Banks
The largest banks occupy a central position in the financial system. Their results reflect activity across households, businesses, capital markets and credit markets, making them useful indicators of economic conditions.
When companies borrow to finance expansion, households take out mortgages or businesses complete acquisitions, banks often participate directly or indirectly. Their results can therefore provide insight into whether economic activity is strengthening, slowing or becoming more uneven.
The opening reports are particularly important because they establish an early benchmark for the broader quarterly reporting cycle. Strong results from several large banks may support confidence in corporate earnings, while disappointing credit trends or cautious management guidance could raise questions about the durability of economic growth.
Investors will be looking at several key measures.
Net interest income indicates how much banks earn from interest-bearing assets after accounting for interest paid on deposits and other funding. It remains one of the most important measures of traditional banking profitability.
Investment banking revenue provides insight into corporate mergers, acquisitions, debt issuance and equity offerings. Strong advisory and underwriting activity can signal that companies are becoming more comfortable making strategic decisions and accessing capital.
Trading revenue reflects client activity and market conditions across equities, fixed income, currencies and commodities. Trading can produce substantial income, but results may fluctuate significantly from one quarter to another.
Credit provisions and loan performance reveal whether borrowers are keeping up with their obligations. Rising delinquencies, defaults or expected credit losses can reduce profitability and indicate growing pressure on households or businesses.
Management guidance helps investors understand what executives expect from interest income, expenses, loan demand and capital markets in the coming quarters.
The relationship between these indicators matters more than any single figure. A bank may report higher revenue while experiencing weaker margins, rising expenses or deteriorating credit quality. Another institution may report slower growth but demonstrate stronger cost control and more stable lending conditions.
This is why the opening week of Earnings Season is an opportunity to compare underlying business performance rather than simply rank companies by reported earnings per share.
JPMorgan Chase: A Broad Banking Franchise Under the Spotlight
JPMorgan Chase enters the reporting week as one of the most closely watched institutions in the financial sector. Its extensive operations across consumer banking, commercial banking, payments, asset management and investment banking provide a broad view of financial activity.
The bank is scheduled to report its third-quarter results on Tuesday, October 13, before the U.S. market opens. Analysts’ estimates vary by data provider and reporting methodology, but current published consensus figures place expected earnings near $5.90 to $5.95 per share, with revenue estimates around $51 billion to $52 billion.
These figures are forecasts, not confirmed results. Investors will compare the eventual announcement with both consensus expectations and the bank’s own commentary about the operating environment.
Revenue Growth and Earnings Quality
JPMorgan’s diversified business model is one of its principal strengths. Revenue from consumer banking and payments can provide a different earnings profile from institutional trading and investment banking, while asset management generates fees tied to client assets and market performance.
This diversification can help the bank manage periods of weakness in individual business lines. However, it also makes the composition of earnings important.
If revenue growth is driven mainly by trading activity or unusually strong capital markets, investors will want to understand whether those conditions can persist. If growth is supported by a wider range of businesses, the results may provide stronger evidence of underlying operating resilience.
Investors should therefore examine revenue by division, changes in expenses and the relationship between income growth and profitability.
Net Interest Income and Lending Conditions
Net interest income will remain an important area of attention for JPMorgan.
The bank earns interest on loans and other assets while paying interest on customer deposits and market-based funding. The difference between these income and funding costs is influenced by interest rates, loan balances, deposit composition and competitive pressures.
Higher rates can support income when asset yields adjust faster than funding costs. However, the benefit is not automatic. Customers may move deposits into higher-yielding alternatives, banks may need to pay more to retain funding, and borrowing demand may weaken when financing becomes expensive.
JPMorgan’s ability to grow interest income will therefore depend on both pricing and balance-sheet activity.
Investors should pay attention to management’s outlook for net interest income, deposit costs, loan growth and the potential effects of changing rate expectations.
Investment Banking and Trading
JPMorgan’s markets and investment banking operations will provide another important signal.
A stronger environment for mergers and acquisitions can benefit advisory revenue, while debt and equity issuance can support underwriting activity. Trading revenue may also improve when clients adjust portfolios, hedge exposures or respond to changes in market conditions.
Nevertheless, strong quarterly results do not necessarily establish a permanent upward trend. Capital markets revenue can be affected by volatility, client positioning, transaction timing and comparisons with unusually strong prior periods.
Investors will want to determine whether the bank’s results reflect broad-based demand or a smaller number of especially profitable activities.
Expenses, Credit Quality and Management Guidance
JPMorgan’s expense outlook deserves close attention. Technology investment, employee compensation, regulatory requirements and business expansion can all affect operating costs.
Higher expenses are not necessarily negative if they support profitable growth. The more important question is whether revenue is increasing quickly enough to absorb those costs.
Credit quality will also influence the assessment. Investors should review consumer delinquencies, commercial loan performance, credit-loss provisions and any changes in management’s expectations for future losses.
What matters most for JPMorgan: whether diversified revenue growth, stable credit quality and effective expense management can support earnings without relying excessively on unusually strong trading or capital markets activity.
Wells Fargo: Net Interest Margins and Growth Remain Central
Wells Fargo is scheduled to report its third-quarter results on Tuesday, October 13. Published analyst estimates place expected earnings near $1.85 per share, with revenue forecasts around $22 billion to $22.3 billion, although individual estimates may differ.
For Wells Fargo, the central issue is how effectively the bank converts loan growth and broader business activity into sustainable profitability.
The institution has been working to strengthen operations, expand selected businesses and improve financial performance following years of regulatory constraints. The removal of the Federal Reserve’s asset cap in 2025 removed a significant limitation on balance-sheet growth, giving the bank greater flexibility to pursue opportunities.
However, the ability to grow does not guarantee that every new loan or deposit relationship will generate attractive returns.
Net Interest Income and Margin Pressure
Wells Fargo’s net interest income is particularly important because traditional lending and deposit-taking remain central to its business.
Net interest margin measures the spread between interest earned on assets and interest paid on funding, relative to interest-earning assets. A declining margin can place pressure on profitability even when the bank is expanding its loan book.
For example, a bank may increase lending volumes while simultaneously paying more to attract deposits. If funding costs rise faster than the returns earned on new loans, the additional business may contribute less income than investors expect.
Wells Fargo’s results should help clarify whether margin pressure is stabilizing or remains a significant challenge.
Investors should look for updated net interest income guidance, changes in deposit costs and management’s explanation of how balance-sheet growth is affecting returns.
Loan Growth and Business Expansion
The end of the asset cap provides Wells Fargo with more room to compete across consumer and commercial banking.
Potential opportunities include auto lending, credit cards, commercial loans, treasury services and relationships with businesses that require a broader range of financial products.
Growth across these categories can improve revenue diversification and strengthen customer relationships. It can also increase expenses and credit exposure, making the quality of that growth important.
Investors should distinguish between loan growth driven by healthy demand and growth that requires aggressive pricing or looser underwriting standards.
The bank’s ability to generate attractive returns from incremental lending will be an important part of the earnings assessment.
Investment Banking and Fee Income
Wells Fargo has also been developing its investment banking capabilities. Advisory, underwriting and other fee-generating services can provide additional revenue beyond traditional interest income.
These businesses may benefit when corporate clients pursue acquisitions, issue debt or raise equity. However, they remain sensitive to market conditions and transaction activity.
The quarterly results should provide a clearer indication of whether investment banking is becoming a more meaningful contributor to the bank’s overall earnings profile.
Expenses, Returns and Credit Risk
Investors will also assess Wells Fargo’s cost discipline and profitability targets.
Expanding business lines, improving technology and meeting regulatory expectations can require substantial investment. The challenge is to ensure that these costs translate into stronger operating performance over time.
Credit quality remains equally important. Consumer loan performance, auto lending, credit cards and commercial exposures may respond differently to economic changes.
Management’s commentary on borrowers, delinquency trends and expected credit losses will help investors evaluate whether the bank’s growth strategy is being supported by sound underwriting.
What matters most for Wells Fargo: whether the bank can translate greater operating flexibility into sustainable loan growth and fee income while managing net interest margins, funding costs and credit risk.
Goldman Sachs: Capital Markets Activity and Revenue Comparisons
Goldman Sachs brings a different perspective to Earnings Season.
Unlike JPMorgan and Wells Fargo, Goldman Sachs has a business model with greater exposure to institutional clients, capital markets, investment banking and asset and wealth management. Its results therefore provide a useful indication of activity among companies, institutional investors and large financial clients.
Goldman Sachs is scheduled to report on Tuesday, October 13. Current published estimates vary, with expected earnings generally around $13 per share and revenue forecasts in the vicinity of $16.8 billion to $17 billion.
Investors should pay particular attention to comparisons with the prior-year quarter, the strength of capital markets activity and the relative contributions of different business divisions.
Investment Banking and the Deal Pipeline
Investment banking revenue is a key area of interest for Goldman Sachs.
The business benefits from mergers and acquisitions, corporate advisory work, debt issuance and equity underwriting. These activities tend to improve when executives and boards become more confident about the economic outlook, financing conditions and the strategic value of transactions.
A growing deal pipeline can support future revenue, but it does not guarantee that every proposed transaction will close. Financing costs, regulatory scrutiny, market volatility and changing valuations can delay or cancel deals.
Investors should look beyond the headline revenue figure to determine whether advisory activity and underwriting demand are improving across multiple categories.
Management commentary on client engagement, pending transactions and financing conditions may be particularly useful.
Equities and Fixed-Income Trading
Trading remains a significant part of Goldman Sachs’ business.
Equities revenue can benefit from client demand for execution, financing, derivatives and prime brokerage services. Fixed-income, currencies and commodities operations respond to activity across interest rates, credit, foreign exchange and commodity markets.
Trading performance is influenced by both client demand and market conditions. Strong activity in one category may be offset by weaker performance elsewhere, so investors should examine the composition of revenue.
Comparisons with previous quarters are also important. A bank reporting slower growth after an exceptional period may still be performing well in absolute terms.
The key question is whether the latest results demonstrate sustainable client activity or reflect a temporary concentration of favourable conditions.
Asset and Wealth Management
Goldman Sachs has been seeking to strengthen the contribution of asset and wealth management to its business.
These activities can generate recurring management fees and client-related revenue, potentially providing a different earnings profile from transaction-dependent investment banking and trading.
However, results depend on factors such as assets under management, market valuations, net client inflows, fundraising, investment performance and the timing of fees.
Investors should examine whether asset and wealth management is generating consistent growth and whether the business mix is becoming more diversified.
Expenses, Compensation and Profitability
Goldman’s profitability also depends on compensation costs, technology investment, business expenses and the allocation of capital across divisions.
When markets are active, employee compensation and other variable costs can increase alongside revenue. This means strong revenue growth does not always translate into an equivalent increase in earnings.
Investors will want to understand whether operating expenses are growing at a manageable pace and whether the bank is maintaining attractive returns on capital.
What matters most for Goldman Sachs: whether investment banking, trading and asset management can produce balanced revenue growth while preserving profitability across changing market conditions.
Citigroup: A Useful Comparison for the Banking Sector
Citigroup is another major institution to watch during the opening days of Earnings Season. Its results can help investors compare international banking exposure, institutional client activity, consumer operations and the effects of ongoing business restructuring.
Citigroup’s third-quarter report is expected on Tuesday, October 13, according to current earnings calendars.
The bank’s performance will provide additional context for assessing whether growth is broad-based across large financial institutions.
Revenue and Business Mix
Citigroup operates across institutional services, markets, wealth management and consumer banking in selected markets. Its results can therefore reflect a different mix of corporate and consumer demand from those of its largest domestic competitors.
Investors will be interested in the relative performance of services, trading, investment banking and other fee-generating operations.
Stronger institutional client activity could support revenue, but the durability of that growth will depend on client demand, market conditions and cost control.
Restructuring and Efficiency
Citigroup’s ongoing efforts to simplify its operations and improve efficiency remain important to the investment case.
Restructuring can create near-term expenses while potentially supporting better profitability over time. Investors should distinguish between temporary implementation costs and recurring operating expenses.
Progress should be assessed through measurable improvements in operating performance, capital allocation and management’s ability to execute its strategic priorities.
What matters most for Citigroup: whether its operating improvements and institutional business activity are translating into more consistent financial performance.
Bank of America: Net Interest Income and Fee Growth
Bank of America is scheduled to report on Wednesday, October 14, following the initial Tuesday reports.
The bank provides another important comparison because its business combines consumer banking, commercial lending, wealth management, investment banking and trading.
Analyst forecasts currently place expected earnings near $1.10 to $1.11 per share, with revenue estimates around $30.6 billion. These figures may change as analysts update their models and should be treated as estimates rather than confirmed results.
The Net Interest Income Outlook
Bank of America’s performance remains sensitive to interest rates and deposit pricing.
A large deposit base can provide an important funding advantage, but competition for customer balances can increase funding costs. The bank’s results will help investors assess whether net interest income is benefiting from its balance sheet or facing pressure from the cost of retaining deposits.
Loan demand, securities income, deposit mix and the timing of interest-rate changes will all influence the outlook.
Investors should pay particular attention to management’s updated guidance for net interest income and any changes to expectations for the remainder of 2026.
Investment Banking and Markets Revenue
Investment banking and trading provide additional sources of revenue beyond traditional lending.
If corporate clients remain active in debt issuance, equity transactions and advisory services, these divisions may help offset weaker performance elsewhere. However, the contribution of trading and investment banking can fluctuate from quarter to quarter.
The quality of revenue growth will matter more than a single strong headline figure.
Consumer Spending and Credit Performance
Bank of America also offers insight into the financial condition of U.S. households.
Credit card balances, payment behaviour, delinquencies and consumer loan losses can reveal whether spending remains sustainable or is being supported by increasing borrowing.
Strong consumer activity may support card spending and payment-related revenue. However, higher balances accompanied by worsening repayment trends could indicate growing financial pressure.
What matters most for Bank of America: whether net interest income and fee businesses can sustain profitability while consumer credit remains manageable.
What the Major Banks Have in Common
Although the largest banks have different business models, several themes will connect their earnings reports.
1. Interest Rates and Net Interest Income
Interest rates influence banks through asset yields, deposit costs, loan demand and the value of securities portfolios.
A higher rate environment can support lending income, but the benefit depends on how quickly assets and liabilities reprice. Banks with stronger deposit franchises may be better positioned to manage funding costs, although customer behaviour and competition remain important.

Investors should avoid assuming that higher rates automatically produce higher profits for every bank.
2. Credit Quality and Loan-Loss Provisions
Credit conditions will be one of the most important indicators across the reporting season.
Banks set aside provisions to account for expected losses on loans and other credit exposures. Higher provisions reduce current earnings, even when the losses have not yet materialized.
An increase in provisions does not necessarily indicate a crisis. It may reflect prudent adjustments to economic forecasts, portfolio composition or specific borrower risks.
The more significant concern would be a sustained deterioration in credit performance across multiple loan categories.
Investors should monitor consumer credit cards, auto loans, commercial real estate, corporate lending and other areas where financial stress may emerge.
3. Trading Revenue and Capital Markets
Market activity has been an important source of income for major investment banks and diversified financial institutions.
Trading revenue can be supported by client hedging, portfolio repositioning, financing and market-making activity. Investment banking can benefit from improved merger activity and stronger issuance markets.
However, these businesses are cyclical. Comparisons with exceptionally strong periods may make year-over-year growth appear weaker even when revenue remains healthy.
Investors should examine both absolute revenue levels and the factors driving changes.
4. Deposit Competition and Funding Costs
Deposits are a critical source of funding for traditional banks.
When customers can earn attractive returns on money-market funds, Treasury securities and other alternatives, banks may need to raise deposit rates to retain balances.
That can compress margins, particularly if loan yields do not increase at the same pace.
The latest results should help clarify whether deposit competition is easing, stabilizing or becoming more intense.
5. Operating Expenses and Technology Investment
Banks continue to invest in technology, cybersecurity, compliance, digital services and operational efficiency.
These investments can improve customer experiences and reduce costs over time, but they can also increase expenses in the near term.
Investors should assess whether expense growth is consistent with management’s strategic plans and whether revenue is expanding sufficiently to support those investments.
6. Capital, Liquidity and Shareholder Returns
Capital strength remains essential to a bank’s ability to withstand losses and support lending.
Investors will monitor capital ratios, liquidity, dividends and share repurchases, while considering regulatory requirements and the bank’s growth plans.
A company may have the capacity to return more capital to shareholders, but the decision will depend on profitability, capital needs and management’s assessment of economic risks.
The Economic Signals Investors Should Watch
Bank earnings provide more than company-specific information. They can also offer clues about the wider economy.
Consumer Spending and Borrowing
Consumer spending supports activity across retail, travel, services and other industries. Banks may benefit through credit card transactions, lending and payment services.
However, spending data needs to be considered alongside household debt and repayment behaviour. High transaction volumes are more encouraging when borrowers are managing their obligations effectively.
Investors should look for commentary on spending trends, credit card performance and the condition of different consumer segments.
Business Confidence and Corporate Investment
Corporate borrowing and investment banking activity can reflect business confidence.
When executives expect stronger demand, they may pursue acquisitions, expand operations or raise capital. When uncertainty increases, companies may delay transactions or conserve cash.
Bank management commentary on corporate clients can therefore provide useful context for assessing the business environment.
Commercial Real Estate and Business Lending
Commercial real estate remains an area that deserves attention because refinancing costs, property valuations and occupancy conditions can differ considerably across markets.
Not every commercial real estate loan carries the same risk. Property type, borrower quality, loan-to-value ratios, maturity schedules and geographic exposure all influence potential losses.
Investors should assess whether banks are reporting isolated weaknesses or broader deterioration across commercial lending portfolios.
Treasury Yields and Financial Market Conditions
Higher Treasury yields can influence borrowing costs, securities valuations, corporate financing decisions and investor appetite for risk.
The effects vary by institution. Some banks may benefit from certain rate movements, while others may experience higher funding costs or weaker demand for loans.
Management guidance will be important in explaining how current market conditions are affecting each institution.
How to Read Bank Earnings Beyond the Headline Numbers
A reported earnings beat is not always a reason for a stock to rise, just as a modest miss does not automatically indicate deteriorating fundamentals.
Share prices respond to results relative to expectations, the quality of reported earnings and the outlook presented by management.
Compare Results With Consensus Estimates
The first step is to compare earnings per share and revenue with current analyst forecasts.
However, investors should also examine the size of any difference and whether it results from recurring operations, one-time items or accounting adjustments.
A small beat driven by lower taxes may have a different significance from one supported by stronger recurring revenue.
Review the Year-Over-Year Comparison
Growth rates help investors assess whether the business is expanding, but comparisons can be affected by unusual prior-year results.
A bank that reported exceptionally strong trading revenue a year earlier may record slower growth even if its latest quarter is solid.
Conversely, a weak prior-year comparison can produce a high growth rate that exaggerates the underlying improvement.
Both absolute figures and percentage changes should be considered.
Listen to the Earnings Call
Management commentary often explains the factors behind the reported figures.
Investors should listen for changes in guidance, descriptions of customer behaviour, credit expectations, expense plans and the pipeline for investment banking activity.
The language used by executives can also help identify changes in confidence, although qualitative commentary should be assessed alongside measurable financial data.
Watch the Market Reaction
The share-price response can reveal whether results exceeded what investors had already priced in.
A stock may fall after a strong report if the outlook disappoints or investors expected even better results. It may rise after a modest miss if the underlying trends are improving and management provides reassuring guidance.
Market reactions can be volatile immediately after earnings announcements. A single trading session does not necessarily establish a long-term trend.
Other Companies Reporting During the Week
The focus of this Earnings Season preview is the banking sector, but other major corporate reports will provide additional information about the economy and market sentiment.
ASML and Taiwan Semiconductor: Semiconductor Demand
ASML is scheduled to report on Wednesday, October 14, while Taiwan Semiconductor Manufacturing is expected to report on Thursday, October 15.
Both companies are important to the semiconductor supply chain. Their results may help investors assess demand for advanced chipmaking equipment, manufacturing capacity and semiconductor products used in artificial intelligence, data centres and other applications.
For ASML, investors will focus on orders, equipment demand, production capacity and management’s outlook for semiconductor capital spending.
For Taiwan Semiconductor, revenue growth, advanced-process demand, capital expenditure and margins will be important indicators.
These reports are relevant to the wider market, but their business drivers differ substantially from those of the banks.
UnitedHealth Group: Healthcare Costs and Profitability
UnitedHealth Group is expected to report on Tuesday, October 13.
Investors will be watching medical costs, insurance performance, Optum operations and management’s outlook for profitability. Changes in healthcare utilisation and reimbursement conditions can influence margins, making the company’s guidance especially important.
Its results will offer a separate perspective on the healthcare sector rather than a direct indicator of banking conditions.
Johnson & Johnson: Pharmaceutical and Medical Technology Performance
Johnson & Johnson is also scheduled to report on Tuesday.
Investors will examine pharmaceutical sales, product performance, medical technology demand and the company’s latest outlook. Product-level growth and competitive conditions will help determine whether the company can maintain momentum across its business lines.
Domino’s Pizza: Consumer Demand and Sales Trends
Domino’s Pizza is expected to report on Tuesday, providing a view of consumer spending in the restaurant sector.
Investors will focus on comparable-store sales, order volumes, pricing, promotions, franchisee profitability and management’s growth outlook.
The results may help clarify whether consumers are responding to value-oriented offers and whether demand remains resilient in a competitive restaurant environment.
Alcoa: Aluminum Demand and Industrial Conditions
Alcoa is expected to report on Thursday, October 15.
The aluminum producer’s results will provide insight into production, pricing, energy costs, industrial demand and cash flow. Investors will also assess production guidance and the company’s ability to manage operational challenges.
Although these companies operate in different industries, their reports contribute to the broader assessment of corporate profitability and market expectations.
What Could Move Bank Stocks After Earnings?
The market response to the opening bank reports will depend on how actual results compare with expectations and how management describes the next several quarters.
Several factors could influence investor sentiment.
Stronger-than-expected net interest income: If banks report better lending income or more favourable deposit trends, investors may become more confident about the outlook for traditional banking profits.
Improved investment banking activity: Strong advisory and underwriting results could support expectations for corporate transactions and capital markets revenue.
Stable credit quality: Limited deterioration in delinquencies and manageable loan-loss provisions would provide reassurance that borrowers remain broadly capable of meeting their obligations.
Higher expenses or weaker guidance: Rising costs, margin pressure or cautious commentary could weigh on share prices even when quarterly earnings meet expectations.
Unexpected credit deterioration: A meaningful increase in expected loan losses could raise questions about the economic outlook and the sustainability of current profitability.
Changes in interest-rate expectations: Shifts in bond yields and monetary policy expectations could influence valuations across the banking sector.
These factors may affect individual banks differently. An institution with a strong deposit franchise may respond differently to interest-rate changes from one that relies more heavily on institutional markets.
A Practical Checklist for Investors
Before drawing conclusions from the upcoming reports, investors can use a consistent checklist to compare the major banks.
- Did earnings per share exceed or fall short of consensus expectations?
- Was revenue growth supported by recurring business activity?
- Did net interest income meet management’s guidance?
- Are deposit costs rising, stabilizing or declining?
- Is loan growth consistent with prudent underwriting?
- Are credit-loss provisions changing materially?
- Did investment banking and trading revenue improve?
- Are operating expenses growing faster than revenue?
- Has management changed its outlook for the remainder of 2026?
- Are capital, liquidity and shareholder-return plans consistent with the bank’s financial position?
Using the same framework across institutions makes it easier to identify differences in business quality and risk.
It also reduces the temptation to focus exclusively on the largest earnings beat or the most dramatic stock-price reaction.
Conclusion: What Earnings Season Could Reveal About the Banks
Earnings Season begins with a closely watched group of financial institutions whose results will help investors evaluate the health of the U.S. banking sector.
JPMorgan Chase offers a broad view of consumer banking, lending, payments and capital markets. Wells Fargo provides insight into traditional banking profitability, net interest margins and the benefits of greater operating flexibility. Goldman Sachs offers a perspective on investment banking, trading and wealth management. Citigroup and Bank of America add further comparisons across institutional and consumer businesses.
The most important questions extend beyond whether each company beats analysts’ estimates. Investors need to understand where revenue growth is coming from, whether credit quality remains sound, how funding costs are evolving and whether management teams are confident about the months ahead.
A strong report supported by recurring revenue, disciplined expenses and stable credit conditions would provide a more convincing signal than a headline earnings beat driven by temporary factors. Similarly, weaker growth does not automatically indicate trouble if a bank is maintaining sound underwriting, strong capital and a credible long-term strategy.
The broader corporate reporting week will also provide information about semiconductor demand, healthcare costs, consumer spending and industrial activity. Those reports may influence overall market sentiment, but the opening bank results are likely to be especially important for assessing lending conditions and financial-sector profitability.
For investors, the most useful approach is to compare the banks on a consistent basis, examine management guidance carefully and avoid treating short-term market reactions as definitive conclusions.
The opening reports will not answer every question about the economic outlook. They will, however, establish an important starting point for evaluating whether bank profitability, credit conditions and capital markets activity remain resilient as the reporting season progresses.
Frequently Asked Questions
When does Earnings Season begin for the major banks in October 2026?
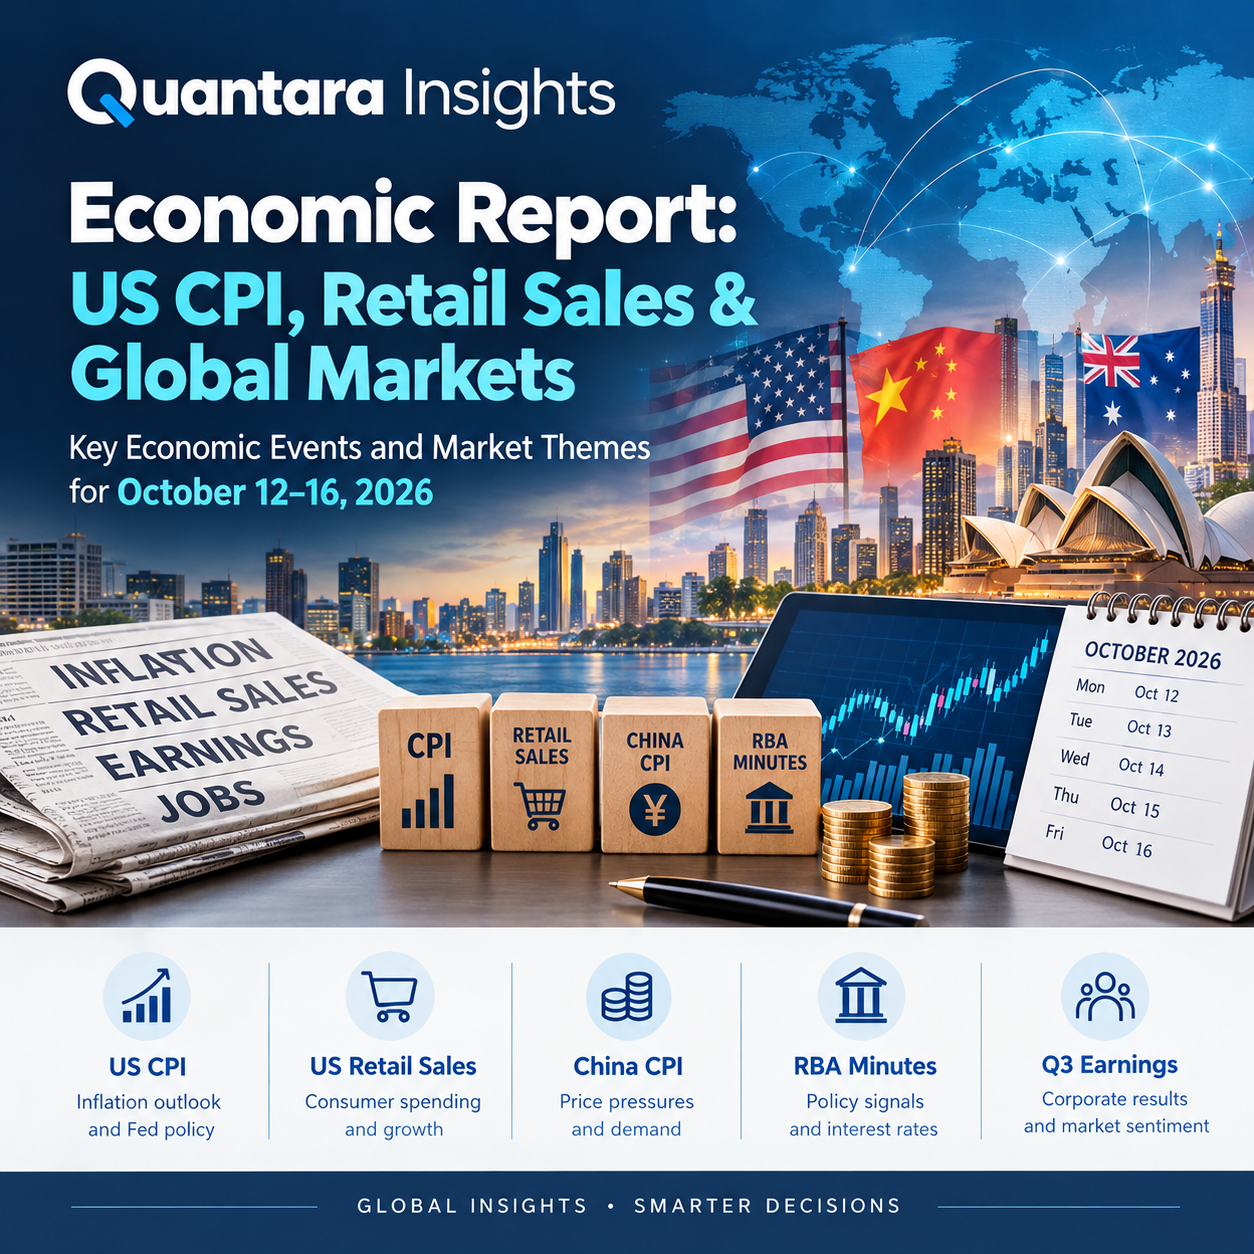
Several major U.S. banks are scheduled to report third-quarter results on Tuesday, October 13, 2026. Bank of America is scheduled to report on Wednesday, October 14, alongside other financial institutions.
Which banks are the main focus this week?
JPMorgan Chase, Wells Fargo, Goldman Sachs and Citigroup are among the key banks reporting on Tuesday. Bank of America follows on Wednesday, providing another important measure of conditions across the sector.
What should investors watch in JPMorgan’s earnings report?
Investors should focus on revenue growth, net interest income, investment banking activity, trading performance, expenses, credit quality and management’s guidance for the remainder of 2026.
Why are net interest margins important for Wells Fargo?
Net interest margins measure the spread banks earn between interest income on assets and interest paid on funding. Changes in deposit costs, loan yields and balance-sheet composition can materially affect profitability.
What matters most in Goldman Sachs’ earnings report?
Investment banking activity, equities and fixed-income trading, asset and wealth management, operating expenses and the sustainability of revenue growth are key areas to monitor.
Can a bank stock fall after beating earnings expectations?
Yes. A stock may decline if revenue quality, management guidance or credit conditions disappoint investors, even when reported earnings exceed consensus estimates. Share prices reflect expectations about future performance as well as the latest results.
How do bank earnings help investors understand the economy?
Banks interact with consumers, businesses and financial markets. Their lending trends, deposit activity, credit losses and corporate client demand can provide useful information about spending, borrowing, investment and financial conditions.
Do strong bank earnings guarantee that bank stocks will rise?
No. Share prices also reflect valuations, interest-rate expectations, market positioning, risk perceptions and the outlook for future earnings. Strong quarterly results may already be reflected in a stock’s price.
What is the difference between earnings estimates and reported results?
Earnings estimates are forecasts made by analysts before a company reports. Reported results are the actual figures disclosed by the company. Estimates can change before the announcement and should not be treated as confirmed financial results.
Why should investors compare more than earnings per share?
Earnings per share does not explain the full quality of a bank’s performance. Revenue composition, credit provisions, funding costs, expenses, capital strength and management guidance help investors determine whether reported profits are sustainable.