
Table of Contents
- Economic Report | October 4–9, 2026
- Global Economic Report: Key Events for October 4–9, 2026
- Sunday, October 4: Brazil election and OPEC+
- Monday, October 5: Global PMI data and US services activity
- Tuesday, October 6: European activity and US trade
- Wednesday, October 7: Federal Reserve minutes and economic indicators
- Thursday, October 8: ECB minutes and political developments
- Friday, October 9: Employment and consumer sentiment
- Brazil Election: Fiscal Policy, Trade Relations and Market Implications
- OPEC+ Meeting: Production Policy and the Global Oil Market
- US ISM Services PMI: A Key Measure of Economic Momentum
- US Treasury Buybacks: Liquidity and Long-Term Bond Market Conditions
- Federal Reserve FOMC Minutes: Inflation, Employment and Interest-Rate Expectations
- Indian Monetary Policy: RBI Decision and Inflation Developments
- Swedish CPIF Inflation: Riksbank Policy Expectations
- ECB Minutes: European Interest Rates and the Inflation Outlook
- UK Holborn and St Pancras By-Election: Political Risk and Market Sentiment
- Norwegian CPI: Inflation Risks and Norges Bank Policy
- Canadian Jobs Report: Employment Growth and Economic Resilience
- Other Economic Indicators and Policy Developments to Monitor
- Week in Review: The Economic Developments Shaping the Outlook
- What This Economic Report Means for Global Financial Markets
- Conclusion: Global Economic Outlook for October 2026
Economic Report | October 4–9, 2026
The global economic calendar for October 4–9, 2026, brings together several important developments for financial markets, including the US ISM Services PMI, the latest Federal Reserve and European Central Bank minutes, the OPEC+ production meeting, and employment and inflation data across major economies. These events arrive against a backdrop of elevated energy prices, shifting interest-rate expectations, geopolitical uncertainty and mixed signals from economic activity indicators.
The central focus of this Economic Report is the interaction between economic growth, inflation and monetary policy. Recent US data have presented a more complicated picture for policymakers. While services activity has accelerated, labour-market conditions have softened and inflation readings have provided some relief. This combination has contributed to a reassessment of the Federal Reserve’s policy outlook, although the persistence of price pressures remains an important consideration.
In Europe, attention turns to the ECB’s September meeting minutes and incoming economic indicators. The central bank’s latest decision and communication have kept the possibility of additional tightening in focus. Meanwhile, inflation developments in Scandinavia could influence expectations for the Riksbank and Norges Bank, both of which remain attentive to the persistence of price pressures.
Energy markets will also be closely monitored following the OPEC+ meeting. The group’s production decisions, compliance discussions and future capacity assessments are relevant not only for crude oil prices but also for inflation expectations, transport costs and the broader outlook for global economic activity.
Elsewhere, Brazil’s presidential election introduces a political dimension to the week’s market considerations. In North America, Canadian employment data will provide another indication of labour-market resilience, while the US consumer sentiment survey will offer insight into household expectations.
Taken together, these developments create a busy week for investors, policymakers and businesses. The key question is whether the latest data will reinforce expectations of persistent inflation and restrictive monetary policy or point towards a gradual moderation in economic pressures.
Global Economic Report: Key Events for October 4–9, 2026
The economic calendar is concentrated around several high-profile releases and policy updates. The US services sector, central bank communication and energy-market developments are likely to attract the most attention, although regional inflation and employment figures could also generate meaningful market responses.
Sunday, October 4: Brazil election and OPEC+
The week begins with Brazil’s presidential election and an OPEC+ meeting. The Brazilian vote is important for assessing the country’s future fiscal direction, international relationships and policy priorities. OPEC+ will review market conditions, production compliance and the next phase of its output strategy.
Monday, October 5: Global PMI data and US services activity
Monday brings the final September global PMI readings, eurozone producer prices and the US ISM Services report. The services indicator is particularly important because it offers an updated assessment of activity in a major part of the US economy.
The combination of business activity, new orders, employment and prices data will help establish whether the September expansion was accompanied by a meaningful increase in inflationary pressure.
Tuesday, October 6: European activity and US trade
German factory orders, eurozone retail sales and the US balance of trade are among Tuesday’s main releases. The data will provide additional insight into manufacturing demand, consumer activity and international trade conditions.
The EIA’s Short-Term Energy Outlook will also be relevant for energy-market participants assessing supply, demand and price assumptions.
Wednesday, October 7: Federal Reserve minutes and economic indicators
The September FOMC minutes are the principal event on Wednesday. Investors will look for additional detail about policymakers’ views on inflation, employment and the future path of interest rates.
German industrial production, Swedish inflation data, the Bank of England’s policy announcement and US Treasury buyback operations add to the day’s schedule.
Thursday, October 8: ECB minutes and political developments
The ECB’s September meeting accounts will be released alongside German trade data and the UK Holborn and St Pancras parliamentary by-election.
The minutes will be scrutinised for insight into the policy debate and the extent to which further interest-rate increases were considered.
Friday, October 9: Employment and consumer sentiment
Friday’s focus shifts towards Norwegian inflation, Canadian employment and the University of Michigan’s preliminary October consumer sentiment survey.
The data will provide a final assessment of several important economic themes before the following week’s US inflation releases and further central bank developments.
Brazil Election: Fiscal Policy, Trade Relations and Market Implications
Brazil’s presidential election is one of the week’s most important political developments for emerging-market investors. The first round takes place on October 4, with 13 candidates competing. A candidate requires more than 50% of valid votes to win outright. If no candidate reaches that threshold, the two leading candidates proceed to a runoff scheduled for October 25.
Polling ahead of the first round indicates a competitive contest between President Luiz Inácio Lula da Silva and Senator Flávio Bolsonaro. Datafolha polling cited in the original outlook places Lula at 42% and Bolsonaro at 38%. The possibility of a second round therefore remains significant.
Runoff polling has also indicated a close contest. Datafolha has Lula leading Bolsonaro by 48% to 45%, within the poll’s stated margin of error, while Atlas polling has Bolsonaro narrowly ahead. With a portion of voters still undecided, the political outlook remains uncertain.
Economic policy differences
Lula’s economic programme has included expanded welfare measures, household debt relief and stronger regulation of online betting. His foreign-policy approach has emphasised strategic independence from Washington and closer trade relationships with China.
Bolsonaro, the son of former president Jair Bolsonaro, has positioned himself around tougher crime policies and closer ties with the United States. His campaign proposals include expanded prison capacity and a more assertive security agenda.
For financial markets, the distinction between the candidates is not limited to their political positioning. Investors are also assessing fiscal policy, government spending, regulatory priorities and the potential direction of Brazil’s international relationships.
Some analysts regard Bolsonaro as the more market-oriented candidate because of concerns about Lula’s fiscal spending and the prospect of closer alignment with the United States. However, the eventual market response will depend on the policies actually pursued, the composition of Congress and the credibility of fiscal commitments.
US relations and trade uncertainty
Relations with Washington are another consideration. US President Donald Trump has imposed tariffs on Brazilian goods, which Lula has described as interference in domestic politics. The Bolsonaro family has maintained closer political connections with Washington.
A Lula victory could leave trade tensions elevated, while a Bolsonaro victory could create scope for a more constructive bilateral relationship. Nevertheless, tariff policy is influenced by a range of strategic and domestic considerations in both countries.
Political investigations and investor confidence
The election is also taking place amid several investigations involving prominent political figures and business interests.
Flávio Bolsonaro is under investigation in connection with allegations linked to financial activities, while Lula’s son, Fábio Luís Lula da Silva, is separately facing scrutiny over alleged influence peddling. The Banco Master collapse has also triggered investigations involving alleged fraud, money laundering and political connections.
Such developments can affect investor confidence, particularly when they raise questions about institutional stability, governance and the potential for policy disruption.
For Brazilian assets, the key considerations will include polling trends, fiscal expectations, currency volatility and the degree of uncertainty surrounding the period between the first round and the runoff. Investors will also be watching whether campaign developments influence expectations for public debt and the Brazilian real.
OPEC+ Meeting: Production Policy and the Global Oil Market
The OPEC+ meeting on October 4 is a central event for energy markets. The group is expected to keep November production targets unchanged after completing the rollback of its 1.65 million barrels per day voluntary cuts in September and pausing further increases in October.
The meeting comes at a time when actual production, shipping conditions and geopolitical developments remain important determinants of available supply.
Production targets and compliance
The Joint Ministerial Monitoring Committee will review market conditions and member compliance before the seven core producers meet to discuss output policy.
The distinction between official production targets and actual supply is important. Production capacity, operational constraints, maintenance requirements and export infrastructure can all influence how much oil reaches the market.
A decision to maintain targets would therefore not necessarily translate into unchanged physical supply. Market participants will assess the meeting’s language around compliance and the possibility of adjustments in subsequent months.
The delayed capacity review
The production capacity review intended to help establish 2027 baselines has been delayed until mid-November because some members have yet to submit the required information.
The review matters because future production quotas are linked to the capacity and baseline framework agreed by the group. Differences between existing allocations and potential future production capacity can create difficult negotiations.
Iraq’s push for a higher baseline is one example of the competing interests involved. Members with greater capacity may seek additional room to produce, while the group must also consider the impact of higher output on market stability.
Strait of Hormuz and supply disruptions
Actual output remains affected by shipping and infrastructure disruptions around the Strait of Hormuz. This is particularly important because the region is a major route for internationally traded crude oil and petroleum products.
Disruptions to shipping can influence freight costs, insurance premiums, delivery schedules and the effective availability of energy supplies. Even when production targets remain unchanged, logistical constraints can tighten the market.
For this reason, the OPEC+ decision should be considered alongside developments in shipping and infrastructure rather than in isolation.
Oil prices and inflation expectations
Energy prices affect the global economy through several channels. Higher crude prices can increase transport and production costs, raise household energy expenditure and contribute to headline inflation.
For central banks, persistent energy-related inflation can complicate decisions about interest rates. Policymakers may be reluctant to ease monetary conditions when energy prices are feeding into broader costs or influencing inflation expectations.
However, the effect is not uniform across economies. Energy exporters may benefit from stronger revenues, while energy-importing countries face greater pressure on trade balances, household purchasing power and business margins.
The key questions following the OPEC+ meeting will be whether the group signals further production increases, whether compliance concerns become more prominent and whether shipping conditions change the balance between planned and available supply.
US ISM Services PMI: A Key Measure of Economic Momentum
The US ISM Services PMI is one of the week’s most closely watched economic releases. It provides insight into business conditions across the services sector and helps investors assess the direction of economic activity, employment and inflation.
The services sector represents a substantial share of US economic output. Its performance is therefore an important part of the broader assessment of growth.
The September ISM report will be interpreted against the latest S&P Global services survey, which showed a notable acceleration in business activity.
Recent services activity
S&P Global’s flash services PMI business activity index rose to 58.7 in September from 56.5 in August. The reading marked a 59-month high and helped lift the composite output index to 58.4 from 56.0, its fastest expansion since July 2021.
The acceleration was led by services. Business activity increased at its strongest pace in more than five years, while new business growth reached its fastest rate since March 2022.
Demand was primarily domestic. Services exports increased only modestly, suggesting that the improvement was driven more by conditions within the US economy than by a broad-based strengthening in international demand.
Although the S&P Global survey is not the same as the ISM Services PMI, it provides useful context for the upcoming release.
New orders and outstanding business
New orders are an important component of services-sector activity because they provide an indication of future production and revenue.
The acceleration in new business reported by S&P Global suggests that demand strengthened during September. At the same time, the increase in outstanding work points towards potential capacity constraints.
Services backlogs rose at a faster rate, contributing to the sharpest economy-wide increase in outstanding orders since May 2022.
Rising backlogs can reflect strong demand, but they can also indicate that businesses are having difficulty completing work at the required pace. If capacity constraints persist, firms may respond by hiring additional employees, increasing operating hours or raising prices.
For the ISM release, investors will therefore monitor new orders and business activity alongside the employment and supplier delivery components.
Supplier deliveries and supply-chain pressures
Supplier delivery times offer insight into supply-chain conditions. Slower deliveries can indicate stronger demand, logistical difficulties or disruptions to the movement of goods and services.
S&P Global’s economist described bottlenecks as among the most severe in the survey’s nearly two-decade history outside the pandemic period.
If these pressures are reflected in the ISM supplier deliveries index, the report could indicate that operating conditions are becoming more constrained.
The distinction between demand-driven and supply-driven delays is important. Strong demand can be consistent with healthy economic growth, while supply disruptions can raise costs without generating equivalent increases in productive capacity.
This creates a more difficult environment for businesses attempting to maintain output while managing expenses.
Employment and wage pressures
Services payrolls increased at the fastest rate since June 2022 in the S&P Global survey. Firms hired additional workers to meet stronger demand, although the survey also indicated growing difficulty in finding suitable employees.
Labour-market conditions are particularly important for the inflation outlook. Strong employment can support household incomes and consumption, but labour shortages and wage pressures may also increase the cost of providing services.
The relationship between wages and prices is not automatic. Productivity, profit margins, competition and demand conditions influence how much of any increase in labour costs is passed on to customers.
Nevertheless, sustained wage pressure can make services inflation more persistent, especially in labour-intensive industries.
Prices and business confidence
Services input-cost inflation reached its highest level since November 2022 in the S&P Global survey. Higher fuel and transport expenses were identified as major contributors, while wage pressures also increased.
Selling-price inflation rose as well, although competition within the services sector limited the extent of price increases.
This combination suggests that businesses are facing higher costs but may not have full pricing power. Where companies cannot pass on expenses, profit margins may come under pressure.
Business sentiment remained below its longer-term trend, with cost-of-living concerns, elevated borrowing costs and political uncertainty weighing on confidence.
What to watch in the ISM report
The September ISM Services PMI will be assessed across several areas:
- Business activity: whether the pace of services-sector growth accelerated or moderated.
- New orders: whether demand remains sufficiently strong to support future activity.
- Employment: whether hiring conditions are improving or labour demand is weakening.
- Prices paid: whether input-cost inflation is becoming more persistent.
- Supplier deliveries: whether supply-chain constraints are intensifying.
- Business activity expectations: whether firms remain confident about the outlook.
A stronger-than-expected report could reinforce concerns about inflation persistence, particularly if prices paid and employment rise alongside activity.
A softer reading could support the view that restrictive monetary conditions are beginning to moderate demand. However, weaker activity accompanied by higher input prices would present a more complicated signal.
The central issue is not simply whether the index rises or falls. The composition of the report will help determine its implications for interest rates, Treasury yields and the US dollar.
US Treasury Buybacks: Liquidity and Long-Term Bond Market Conditions
The US Treasury’s 20–30-year buyback operation is another development worth monitoring during the week.
The Treasury will announce the preliminary size of the operation on Tuesday, with the final size confirmed on Wednesday ahead of the transaction.
Enhanced buyback operations have generally involved a maximum of USD 6 billion per operation. With yields elevated, market participants will assess whether the Treasury changes this limit.
Understanding Treasury buybacks
Treasury buybacks involve the government repurchasing previously issued securities. These operations can support market functioning by helping manage the composition of outstanding debt and providing an additional source of liquidity.
They should not be confused with a broad monetary stimulus programme. The operations are primarily related to Treasury debt management and market functioning.
Buybacks can help address liquidity conditions in older securities and support the orderly operation of the government bond market.
Previous operation and market implications
In the previous 20–30-year operation, the Treasury accepted USD 4.08 billion of the USD 10.47 billion in offers submitted.
The accepted amount was below the USD 6 billion maximum. This may indicate that the Treasury did not consider enough of the submitted offers economically attractive to justify buying up to the limit.
For investors, the distinction matters. An operation below its maximum does not automatically indicate weak demand for Treasury securities. It can reflect the prices at which holders were willing to sell and the Treasury’s assessment of value.
What investors will monitor
The preliminary size announcement, final operation limit and accepted offers will provide information about the Treasury’s approach to liquidity support.
The broader interest-rate environment remains important. Higher yields can influence the attractiveness of longer-dated securities, portfolio duration decisions and the cost of financing across the economy.
However, buybacks are only one part of the Treasury market’s functioning. Issuance volumes, investor demand, inflation expectations and Federal Reserve policy will continue to play a larger role in determining the direction of longer-term yields.
Federal Reserve FOMC Minutes: Inflation, Employment and Interest-Rate Expectations
The September FOMC minutes are among the week’s most important policy releases. They will provide a detailed account of the discussions behind the Federal Reserve’s latest interest-rate decision and may help clarify how policymakers assessed the balance of risks.
At the September meeting, the Fed unanimously raised interest rates by 25 basis points. The statement made relatively limited changes, noting that the increase would help return inflation to target in a timelier manner while reaffirming the central bank’s commitment to price stability.
The Fed continued to describe inflation as elevated but removed earlier language that partly attributed inflation to supply shocks.
The updated economic projections
The September Summary of Economic Projections indicated that the median participant expected one additional rate increase in 2026, followed by rates remaining on hold through 2027.
The distribution of individual projections was more varied.
Four participants projected two further increases in 2026, 12 projected one additional increase and two expected no further increases.
Views for 2027 were more divided. Eight participants projected at least two further increases from current levels by the end of the year, six projected one additional increase and four expected rate cuts from current levels.
These projections highlight the uncertainty surrounding the policy outlook. They represent individual policymakers’ assessments rather than a binding commitment by the Federal Reserve.
Inflation remains central to policy
The Fed’s assessment of inflation risks was an important feature of the September projections.
Fifteen participants judged that risks to core PCE inflation were weighted to the upside, while three viewed them as broadly balanced.
This suggests that policymakers remained concerned about the possibility that inflation could prove more persistent than expected.
By contrast, the assessment of labour-market risks was relatively balanced. Seventeen participants saw unemployment risks as broadly balanced, one viewed risks as weighted to the downside and none considered them weighted to the upside.
The difference between these assessments indicates that inflation remained the more prominent concern at the time of the meeting.
Recent data have changed the policy backdrop
Developments after the September meeting have complicated the outlook.
The August PCE report was softer than expected. Core PCE increased by 0.2% month on month, compared with 0.4% previously and a 0.3% consensus forecast. The annual core rate was reported at 3.0%, below the 3.3% forecast.
Headline PCE increased by 0.3% month on month, below the expected 0.4%. Its annual rate was 3.4%, also below the 3.7% forecast.
The report provided some relief, although revisions associated with the annual national income and product accounts update affected the interpretation of the data.
Some of the downward revision to core inflation was concentrated in financial-services categories, including portfolio management and investment advice fees. These categories can be volatile and may receive different weight in the Fed’s assessment compared with broader market-based inflation measures.
Market-based PCE measures accelerated during the month, suggesting that the underlying inflation picture was not uniformly soft.
Employment conditions have also weakened
The September US employment report added to the debate about the appropriate policy response.
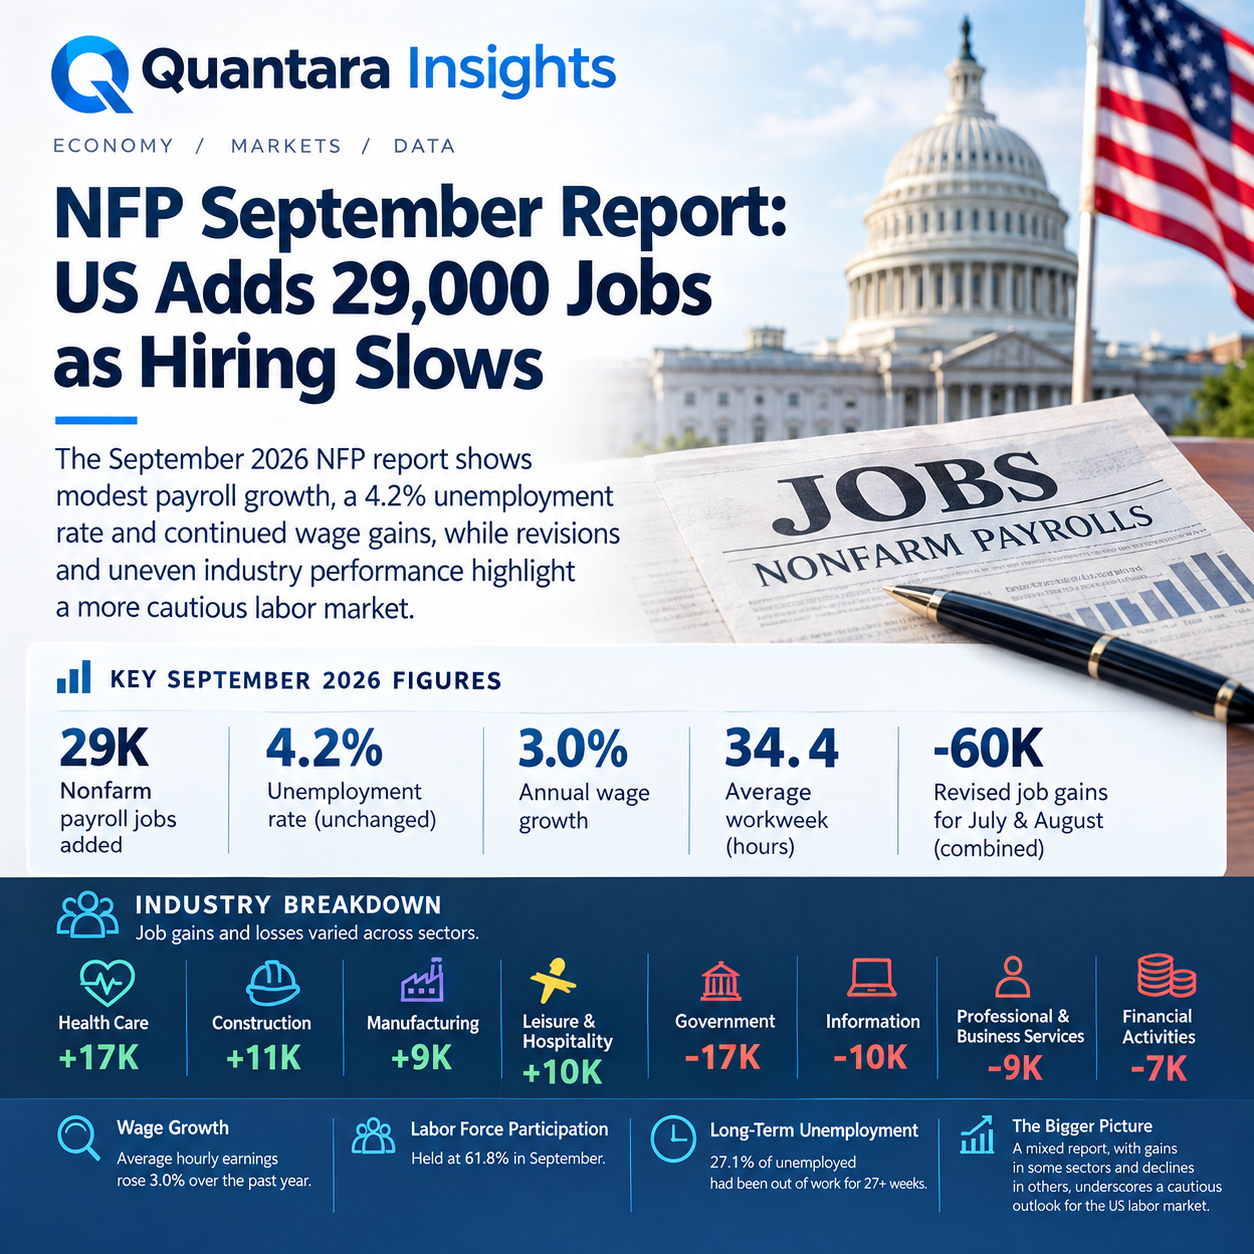
Nonfarm payrolls increased by just 29,000, below the 90,000 consensus forecast. The previous month’s payroll increase was revised down, and the combined revision to July and August was negative.
The unemployment rate rose to 4.2% from 4.1%, while the participation rate increased to 61.8% from 61.6%.
These figures indicate that employment growth was weaker than previously estimated. The increase in labour-force participation also suggests that the rise in unemployment cannot be interpreted solely as a result of workers leaving the labour market.
The three-month average of payroll growth has fallen substantially, raising questions about the pace of job creation needed to maintain labour-market stability.
However, a single report does not establish a definitive change in labour-market conditions. Policymakers will continue to evaluate trends across employment, wages, vacancies, participation and unemployment.
Fed communication and expectations for October
Comments from Federal Reserve officials since the September meeting have indicated that some policymakers see no need to rush additional rate increases.
Vice Chair Williams has described another increase this year as reasonable, while also signalling that policy decisions should remain responsive to incoming information. Other officials have expressed a more cautious approach.
The softer PCE data and weaker employment report have contributed to a reduction in market expectations for an October rate increase.

The minutes will be useful in determining whether the more patient tone expressed after the meeting was already evident in the September discussions.
However, the minutes will not incorporate the subsequent PCE and employment releases. Their value will therefore lie in explaining the original policy debate rather than providing a fully updated assessment of the economy.
Implications for bonds, currencies and equities
For bond markets, the minutes could influence expectations for the timing and pace of future interest-rate changes.
A more cautious discussion could support shorter-dated Treasury prices and reduce yields, while renewed concern about inflation could produce the opposite response.
The US dollar may also react through changes in interest-rate differentials and broader risk sentiment.
Equity markets will be sensitive to the balance between growth and borrowing costs. A more accommodative policy outlook can support valuations, but weaker economic data may weigh on earnings expectations.
The overall market response will depend on whether the minutes add genuinely new information or largely repeat the policy signals already reflected in prices.
Indian Monetary Policy: RBI Decision and Inflation Developments
The Reserve Bank of India is scheduled to hold its latest three-day monetary policy meeting during the week.
Economists’ expectations are divided, although a major newswire poll cited in the original outlook found that 35 of 61 economists expected a 25-basis-point increase in the repurchase rate, from 5.25% to 5.50%.
The RBI left rates unchanged at its August meeting, maintaining a neutral policy stance. Governor Sanjay Malhotra emphasised uncertainty in the global economic environment, including volatility in crude oil prices, currencies and financial markets.
He also noted that headline inflation had moved above the central bank’s target, while some supply-side pressures linked to the West Asia conflict had eased.
Inflation and policy considerations
India’s August CPI inflation increased to 4.82% year on year, compared with 4.45% previously and expectations of 4.8%.
The increase placed inflation above the central bank’s 4% target, strengthening the argument for a rate increase.
Nevertheless, the RBI must consider the broader inflation trajectory rather than responding mechanically to one monthly release.
Supply-side pressures, food prices, energy costs and currency movements can all affect headline inflation. Policymakers must assess whether these pressures are temporary or likely to become more persistent.
The case for caution
Malhotra has indicated a preference for greater clarity before changing interest rates. This suggests that a decision to remain on hold cannot be ruled out despite inflation exceeding the target.
The central bank must also consider the effects of earlier policy decisions on borrowing costs, credit conditions and economic activity.
A rate increase could help reinforce inflation control and support confidence in the policy framework. However, tighter financial conditions could also weigh on investment and consumption.
For the Indian rupee and domestic bond market, the decision and accompanying communication will be important. The emphasis will be on whether the RBI signals a sustained tightening cycle or frames any increase as a response to near-term inflation risks.
Swedish CPIF Inflation: Riksbank Policy Expectations
Sweden’s September inflation report is expected to show an increase in both headline and core CPIF inflation.
Headline CPIF is forecast to rise to 1.6% year on year from 0.7%, slightly above the Riksbank’s own forecast of 1.5%.
Core CPIF is expected to increase to 0.7% from 0.5%, in line with the central bank’s projection.
The data will be relevant because the Riksbank’s September communication indicated that interest-rate increases could begin again before the end of the year.
Inflation and monetary policy
An inflation reading above expectations could strengthen the case for tightening, particularly if the increase is broad-based rather than concentrated in a narrow set of components.
Even an in-line result may attract attention because it would confirm the central bank’s projection of a gradual increase in price pressures.
However, policymakers will also assess economic growth, household demand and the broader outlook for inflation.
A central bank may tolerate some short-term volatility in headline inflation if underlying price pressures remain consistent with its objectives.
Market implications
The Swedish krona and government bond yields may respond to the report, especially if the figures change expectations for the timing of the next policy decision.
SEB analysts have suggested that a November rate increase is possible.
The main consideration will be whether the inflation data provide sufficient evidence of persistent pressure to justify tightening despite uncertainty about the pace of domestic economic activity.
ECB Minutes: European Interest Rates and the Inflation Outlook
The ECB’s September meeting minutes are another major event for European financial markets.
At the September meeting, the ECB increased interest rates by 25 basis points. The decision was unanimous, and the accompanying communication indicated that the increase would have been implemented under each of the additional economic scenarios considered by policymakers.
The decision did not produce a substantial shift in market pricing. Subsequent developments, however, have kept expectations for further tightening in focus.
Understanding the September decision
The ECB’s policy decisions reflect an assessment of inflation, economic growth, financial conditions and the balance of risks.
The September increase indicated that policymakers remained concerned about inflation persistence.
The accompanying scenarios were important because they suggested that the decision was not dependent on a single narrow economic forecast.
For investors, the minutes may clarify how policymakers evaluated the different scenarios and whether the possibility of holding rates unchanged or delivering a larger increase was considered.
Was October already a live meeting?
Market attention will focus on whether policymakers discussed the possibility of another increase at the October meeting.
Sources following the September decision had suggested that October remained a potential opportunity for further tightening.
The minutes could provide insight into whether that possibility was actively discussed and how policymakers assessed the balance between inflation risks and the effects of previous rate increases.
A more cautious discussion could support expectations for a pause. Conversely, evidence that policymakers remained concerned about persistent price pressures could reinforce the case for further tightening.
Eurozone inflation and energy costs
Energy prices remain a major influence on the European inflation outlook.
The eurozone inflation figures cited in the original analysis showed headline inflation at 3.8% year on year, with core inflation at 2.2% and super-core inflation at 2.5%.
The energy component increased to 18.8% from 14.3%, indicating that energy was an important contributor to the headline acceleration.
Food-related components and services prices also showed signs of upward pressure.
The ECB must distinguish between the direct impact of higher energy prices and the risk that these increases spread into wages, services and other prices.
If energy-related costs remain elevated for an extended period, the likelihood of second-round effects could increase.
Implications for European markets
ECB communication can affect government bond yields, the euro and European equity valuations.
A more restrictive policy outlook may support the euro through interest-rate differentials, although broader growth concerns and global risk sentiment also matter.
Higher borrowing costs can affect corporate financing and household demand. They may also influence the valuation of companies whose earnings are sensitive to economic growth and discount rates.
The minutes will therefore be assessed in the context of incoming inflation and activity data rather than treated as a standalone signal.
UK Holborn and St Pancras By-Election: Political Risk and Market Sentiment
The Holborn and St Pancras parliamentary by-election is scheduled for Thursday, October 8.
The contest has attracted attention because of its potential implications for the governing Labour Party and the wider political outlook.
Polling cited in the original analysis places Labour at around 39%, the Greens at 32%, the Conservatives at 10% and Reform at 9%.
If the figures are representative, they would suggest a significant shift towards the Green Party compared with previous electoral patterns.
Political implications
The by-election is being watched as a test of the political environment following the Labour Party’s annual conference.
The result may influence perceptions of party leadership, domestic policy priorities and the possibility of an early general election.
However, a single constituency result should not be interpreted as a direct forecast of national voting behaviour.
Local issues, candidate selection, turnout and tactical voting can all influence the outcome.
Fiscal policy and financial markets
For financial markets, the main concern is whether political developments create uncertainty around taxation, public spending, debt management and the government’s economic programme.
The possibility of an early election could affect expectations for future policy, particularly if the result is interpreted as evidence of weakening political support.
Nevertheless, political developments influence asset prices most strongly when they produce a meaningful change in expected economic policy or fiscal credibility.
Investors will therefore be assessing the result alongside developments in government borrowing, the autumn budget and relations between the UK and European Union.
Norwegian CPI: Inflation Risks and Norges Bank Policy
Norway’s September inflation report is expected to show an increase in annual inflation.
Headline CPI is forecast to rise to 3.7% year on year from 3.3%, above Norges Bank’s stated 3.5% target.
The closely watched CPI-ATE measure is expected to increase to 3.1% from 3.0%, remaining above the central bank’s objective.
The inflation outlook
The expected increase in Norwegian inflation comes after Norges Bank raised interest rates by 25 basis points in September.
The accompanying statement suggested that the policy rate would likely need to remain elevated for some time.
This communication indicates that policymakers remain focused on ensuring inflation returns sustainably towards the target.
A stronger-than-expected CPI report could reinforce expectations that restrictive policy will remain necessary.
Policy expectations and the krone
SEB analysts believe the central bank may have reached its policy peak, although they acknowledge that risks are skewed to the upside.
The Norwegian krone could respond to the inflation release through changes in interest-rate expectations.
A stronger reading may increase the likelihood of further tightening, while softer data could support the view that the September increase was the final move in the current cycle.
However, currency performance will also depend on oil prices, global risk appetite and developments in other major central banks.
Canadian Jobs Report: Employment Growth and Economic Resilience
Canada’s September employment report is scheduled for Friday and will provide an updated assessment of labour-market conditions.
Employment declined by 41,700 in August, compared with expectations for an increase of 15,000. The decline followed three consecutive months of employment growth.
Full-time employment fell by 35,900, while part-time employment declined by 5,800.
The unemployment rate stood at 6.4%, despite a decrease in the participation rate.
Labour-market volatility
Canadian employment data have been volatile, making it difficult to identify the underlying trend from individual monthly releases.
The August decline raised questions about the resilience of hiring, particularly as businesses face uncertainty surrounding international trade and domestic demand.
A recovery in September employment would offer some reassurance, although the composition of the increase would remain important.
Full-time employment, hours worked, participation and wage growth can provide a more complete picture than the headline employment change alone.
Trade uncertainty and hiring
Oxford Economics expects the Canadian economy to continue facing difficulties in generating employment in the near term.
The outlook identifies several headwinds, including new US–Canada tariffs, trade-war uncertainty, the Iran conflict and a shrinking population.
Trade restrictions can affect business confidence, investment decisions and export demand. These effects may eventually influence hiring and household income.
At the same time, changes in population growth can alter the relationship between employment gains and the unemployment rate.
Implications for the Bank of Canada
The employment report will be relevant for expectations about Canadian monetary policy.
A weaker labour market could strengthen the argument for a more accommodative stance, particularly if inflation is also moderating.
However, the Bank of Canada must consider the broader price outlook, financial conditions and the effects of previous policy decisions.
For the Canadian dollar, the report may influence expectations for domestic interest rates relative to those in the United States.
The scale and composition of employment changes will be more informative than the headline figure alone.
Other Economic Indicators and Policy Developments to Monitor
Several additional releases will provide useful context for the global economic outlook.
German factory orders and industrial production
German factory orders and industrial production will offer insight into the performance of Europe’s largest manufacturing economy.
Factory orders are a forward-looking indicator of demand for manufactured goods. Industrial production measures activity across manufacturing and other industrial sectors.
Weak order growth could point towards subdued demand and limited visibility for manufacturers.
Stronger figures would provide some reassurance that industrial activity is stabilising, although the outlook will remain sensitive to energy costs, global trade and financing conditions.
Eurozone producer prices and retail sales
Eurozone producer prices will help assess cost pressures further along the supply chain.
Changes in producer prices can eventually influence consumer inflation, although the relationship depends on margins, demand and the extent to which businesses pass on higher costs.
Retail sales will provide a separate indication of household spending.
If sales remain weak, the data could suggest that elevated prices and borrowing costs are continuing to constrain consumer demand.
French industrial production and trade
French industrial production and trade data will provide additional information about economic activity and external demand.
The figures are particularly relevant in an environment where trade policy, energy costs and global supply conditions are creating uncertainty for European businesses.
The data may also contribute to broader assessments of the eurozone’s growth outlook.
US trade balance
The US balance of trade for August will be another relevant indicator.
Trade figures can be influenced by changes in imports, exports, inventories and exchange rates.
A widening deficit does not necessarily indicate a deterioration in economic conditions. Strong domestic demand can support imports, while changes in energy purchases and capital goods can create significant monthly fluctuations.
The composition of trade flows will therefore be important for interpretation.
US consumer sentiment
The University of Michigan’s preliminary October consumer sentiment survey will provide an indication of household confidence and inflation expectations.
Consumer sentiment is influenced by employment conditions, income growth, prices, interest rates and perceptions of the broader economy.
Rising fuel prices can weigh on household confidence by reducing disposable income, particularly for lower-income households.
The inflation-expectations component will be especially important for financial markets and policymakers.
If consumers expect prices to rise persistently, their behaviour can influence purchasing decisions, wage negotiations and broader inflation dynamics.
However, survey expectations do not necessarily translate directly into realised inflation. They should be evaluated alongside actual price data and other indicators.
Week in Review: The Economic Developments Shaping the Outlook
The previous week delivered a range of economic and policy developments across the United States, Europe, Asia and Australia.
Several of these releases have influenced expectations for monetary policy and will provide context for the events scheduled during October 4–9.
Bank of Japan minutes
The Bank of Japan’s July meeting minutes indicated that members generally considered financial conditions accommodative.
Policymakers discussed the gradual pass-through of higher raw-material costs and the possibility that inflation expectations were rising among households and businesses.
Several members noted that price increases for consumer goods could broaden from the summer onwards. Some also considered underlying inflation to be approaching 2%, reinforcing the importance of maintaining price stability.
A few members highlighted the impact of higher import costs on consumer prices.
One member observed that markets appeared to expect the Bank of Japan to raise rates approximately once every six months, although faster tightening could not be ruled out.
The minutes attracted limited market reaction because a more recent policy meeting had already taken place in September.
At that meeting, the BoJ delivered a widely expected 25-basis-point increase, bringing its short-term policy rate to 1.25%.
The September decision is therefore more relevant to current expectations than the older July discussion.
Reserve Bank of Australia policy announcement
The Reserve Bank of Australia raised its cash rate by 25 basis points to 4.60%, in line with expectations. The decision was unanimous.
The accompanying statement retained a hawkish tone, highlighting elevated inflation and the materialisation of some upside risks identified at the previous meeting.
The Board reiterated that it would take whatever action it considered necessary to return inflation sustainably to target, including additional increases if required.
The RBA also noted that the Middle East conflict had widened and that global energy prices were significantly higher than assumed in its August forecasts.
Recent inflation outcomes were stronger than expected, adding to concerns about the persistence of price pressures.
At the same time, the central bank acknowledged that previous increases in the cash rate had tightened financial conditions and that economic momentum appeared to be slowing.
Governor Bullock’s communication
RBA Governor Michele Bullock struck a relatively more cautious tone during the press conference.
She acknowledged that inflationary pressures could persist longer than previously expected and reiterated that further rate increases remained possible.
However, she also indicated that additional tightening might not be necessary if inflation moderated sufficiently.
The comments highlighted the tension between controlling inflation and avoiding an unnecessarily restrictive policy stance.
For Australian financial markets, the distinction between the central bank’s formal statement and the governor’s subsequent communication was important in interpreting the policy outlook.
UK Labour Party annual conference
The UK Labour Party’s annual conference attracted attention because of developments in domestic policy and the potential implications for future fiscal decisions.
Chancellor Rachel Healey did not substantially alter the existing economic narrative, while Prime Minister Andy Burnham’s remarks generated greater interest.
Domestic proposals included a social-care plan, discussion around the triple lock and the potential nationalisation of water companies.
On foreign policy, Burnham outlined several possible approaches to the UK’s relationship with the European Union, including the prospect of closer integration.
These proposals would require political support and, in several cases, an electoral mandate before implementation.
The conference was generally viewed as a success for Burnham because the remarks did not trigger a fresh market sell-off.
UK government debt performed relatively better than several international peers during the week.
Attention now shifts towards the upcoming by-election, the autumn budget and the next EU–UK summit as potential tests of the government’s political and economic direction.
Australian CPI
Australian headline CPI increased to 4.0% year on year in August from 3.5%, slightly below the expected 4.1%.
The trimmed mean inflation measure remained unchanged at 3.6%, indicating that underlying price pressures remained persistent.
Fuel, electricity and housing costs contributed significantly to the increase in headline inflation.
The supply-side contribution is important because it complicates the interpretation of inflation. Higher energy costs can lift headline prices even when domestic demand is moderating.
Nevertheless, underlying inflation remained above the RBA’s 2–3% target range.
The data supported a cautious policy stance, although the softer-than-expected headline reading reduced some immediate pressure for another increase.
Westpac analysts maintained their view that another rate increase in November was possible, citing the potential for higher energy costs to feed through into broader prices.
US PCE price index
The August US PCE report was softer than expected, with downward revisions to some previously published figures.
Core PCE rose by 0.2% month on month, cooling from 0.4% and below the 0.3% consensus forecast.
The annual core inflation rate remained at 3.0%, below expectations of 3.3%.
Headline PCE increased by 0.3% month on month, compared with 0.1% previously and expectations for 0.4%.
The annual headline rate was 3.4%, below the forecast of 3.7%.
However, the composition of the report was more complicated.
PCE services prices excluding energy and housing accelerated to 0.4% from 0.1%, while goods prices increased by only 0.03%.
The annual national accounts update also produced larger-than-expected downward revisions to core PCE inflation.
These revisions were concentrated in areas such as software and accessories, portfolio management and legal services.
Oxford Economics noted that the revisions eased the reported inflation picture but did not eliminate concerns about supply-driven pressures associated with geopolitical developments, AI investment and tariffs.
Market-based PCE inflation measures also accelerated, suggesting that underlying inflation pressures remained uneven.
Personal income increased by just 0.2%, below the expected 0.5%, while consumption accelerated to 0.6% from 0.1%.
The report contributed to a reduction in expectations for additional near-term Federal Reserve tightening.
Japanese Tankan survey
Japan’s third-quarter Tankan survey showed an improvement in sentiment among large manufacturers.
The index rose to +24 from +22, reaching its strongest level since 2018, although the result was below expectations of +25.
Strong demand associated with semiconductors and artificial intelligence contributed to the improvement.
By contrast, sentiment among large non-manufacturers declined to +35 from +37.
Higher input costs and labour shortages continued to weigh on services businesses.
The mixed results suggest that Japan’s industrial and services sectors are experiencing different economic conditions.
For the Bank of Japan, the survey provides information about business confidence, financing conditions and the potential sustainability of investment.
Swiss CPI
Swiss inflation was broadly in line with expectations in September.
Monthly CPI was unchanged, compared with a 0.4% increase previously, while annual inflation remained at 1.0%.
The result was within the Swiss National Bank’s 0–2% price-stability range.
Core inflation edged higher to 0.5% from 0.4%.
Higher oil prices appeared to be offset by tourism-related costs, leaving limited evidence of broader second-round inflation effects.
The data supported the expectation that the SNB would keep interest rates unchanged in the near term.
However, a sustained increase in inflation towards the upper end of the target range could eventually prompt markets to reassess the possibility of tighter policy in 2027.
US ISM Manufacturing PMI
The US ISM Manufacturing PMI edged down to 54.5 in September from 54.6, slightly below expectations of 55.
Despite the modest decline in the headline index, several components strengthened.
New orders increased to 55.3 from 53.7, while the employment index rose to 52.7 from 51.2.
The prices-paid index recorded a more substantial increase, rising to 77.9 from 71.1 and exceeding the expected 72.3.
Backlogs of orders increased to 56.4 from 51.8, indicating stronger outstanding demand.
Supplier deliveries remained broadly stable at 59.0, while inventories declined below the expansion threshold.
The rise in input prices was a key feature of the report.
Higher oil prices were contributing to cost pressures, raising the possibility that manufacturers would face additional inflationary pressure in the near term.
Oxford Economics also highlighted downside risks to manufacturing activity from higher borrowing costs and energy prices, which could delay household and business spending on durable goods.
Tokyo CPI
Tokyo inflation accelerated sharply in September.
Core CPI increased to 2.7% year on year from 1.8%, while core-core inflation rose to 3.0% from 2.0%.
The increase reflected the unwinding of government subsidies and firmer services inflation.
The figures suggest that price pressures are becoming broader, strengthening the case for additional monetary tightening by the Bank of Japan later in the year.
An immediate October increase appeared less likely than a December move, although expectations remain dependent on incoming data and policy communication.
The BoJ’s October 30 meeting will also include the release of its quarterly economic projections.
Eurozone CPI
Eurozone inflation was hotter than expected, although the data did not immediately trigger a significant market reaction.
Headline inflation reached 3.8% year on year, while core and super-core inflation stood at 2.2% and 2.5%, respectively.
Energy remained a major contributor, with the energy component increasing to 18.8% from 14.3%.
Food-related components also showed upward pressure, while services inflation edged higher.
The report reinforced concerns that energy price increases could begin to influence a wider range of prices.
For the ECB, the data kept the possibility of further tightening in focus, although the ultimate policy response will depend on the persistence of inflation and the broader growth outlook.
US nonfarm payrolls
The September US jobs report was weaker than expected.
Nonfarm payrolls increased by just 29,000, compared with the 90,000 consensus forecast. The previous month’s increase was also revised lower.
The combined revision to July and August payrolls was negative, indicating that earlier employment growth had been overstated.
Private payroll growth slowed, while the unemployment rate increased to 4.2% from 4.1%.
The participation rate increased to 61.8% from 61.6%.
The report added to concerns that employment conditions were losing momentum.
Pantheon Macroeconomics estimated that the three-month average of payroll growth had fallen to approximately 51,000, a pace that could be slightly below the level required to maintain stable employment.
However, Federal Reserve officials have generally described the labour market as close to full employment.
The weaker figures therefore need to be evaluated alongside wage growth, unemployment claims, participation and other labour-market indicators.
Implications for the Federal Reserve
The employment report reinforced expectations that the Fed could pause in October, particularly following the softer PCE data and cautious communication from several officials.
Money-market pricing cited in the original analysis placed the probability of an October increase at 16%, down from 24% on the previous Thursday evening.
The outlook for December remained less certain.
Pantheon Macroeconomics expected the Fed to hold in October and suggested that continued weakness in payroll growth, combined with slower services inflation, could provide sufficient grounds to leave policy unchanged.
However, the upcoming CPI report will be important in assessing whether inflation pressures are moderating or becoming more persistent.
The latest data have therefore shifted the balance of risks, but they have not eliminated the possibility of further tightening.
What This Economic Report Means for Global Financial Markets
The events scheduled for October 4–9 will be interpreted through three main themes: economic growth, inflation persistence and the future direction of monetary policy.
These themes are closely connected. Stronger activity can support employment and corporate earnings, but it may also contribute to inflation if supply capacity is constrained. Weaker activity can reduce inflationary pressure, although it may also create risks for employment and investment.
Interest-rate expectations
The Federal Reserve and ECB minutes are important because they provide additional information about the policy debate.
However, the minutes are backward-looking documents. Their market impact depends on whether they reveal information that has not already been reflected in policy expectations.
Incoming inflation, employment and activity data will remain more important for the future policy outlook.
For investors, the main consideration is whether the balance between inflation and growth is shifting sufficiently to justify a change in expected interest rates.
Bond yields and government financing
Government bond yields reflect expectations for future policy rates, inflation, economic growth and the supply of debt.
The US Treasury buyback operation adds another element to the market’s assessment of liquidity and debt management.
In Europe, ECB communication and regional inflation data may influence expectations for sovereign bond yields.
Differences in policy expectations between the United States and Europe can also affect currency markets and international capital flows.
Currency-market considerations
The US dollar, euro, Brazilian real, Canadian dollar, Swedish krona and Norwegian krone could all respond to the week’s developments.
Currency movements are influenced by interest-rate differentials, commodity prices, economic growth expectations and political risk.
The Brazilian election introduces a specific source of uncertainty for the real, while the OPEC+ meeting and energy prices are particularly relevant for commodity-linked currencies.
In Europe, ECB communication and regional inflation data will contribute to expectations for the euro.
For smaller currencies such as the Swedish krona and Norwegian krone, domestic inflation surprises can have an outsized effect when markets are uncertain about the next policy decision.
Equity-market conditions
Equity markets will be sensitive to the interaction between borrowing costs and corporate earnings expectations.
Stronger services activity can support revenue expectations, but persistent input-cost inflation may weigh on margins.
Higher interest rates can also reduce the present value of future earnings, particularly for companies with long-duration growth expectations.
For investors, the composition of economic data matters more than the headline direction alone.
An economy showing moderate growth alongside declining inflation may provide a more supportive environment for equities than one experiencing stronger activity accompanied by accelerating prices and tighter monetary policy.
Energy prices and the inflation outlook
The OPEC+ meeting and shipping conditions around the Strait of Hormuz remain important for the global inflation outlook.
Higher energy prices can increase headline inflation and place pressure on household purchasing power.
If elevated energy costs persist, they may also influence business pricing decisions and wage negotiations.
However, the eventual impact will depend on the duration and scale of price increases, the extent of pass-through and the response of governments and central banks.
Political and trade uncertainty
Brazil’s election and the UK by-election introduce political developments into an already complex economic environment.
Political uncertainty can influence currencies, sovereign bond markets and investment decisions, particularly when it creates doubts about fiscal policy or international trade relationships.
Nevertheless, markets typically respond most strongly when political events change expectations for actual policy rather than simply generating uncertainty.
Conclusion: Global Economic Outlook for October 2026
The economic calendar for October 4–9 brings several important tests for global financial markets.
The US ISM Services PMI will provide a fresh assessment of business activity, employment and inflationary pressures in the services sector. Its composition will be particularly important following the acceleration in the S&P Global services survey.
The September FOMC minutes will offer additional insight into the Federal Reserve’s assessment of inflation and labour-market risks. However, the subsequent moderation in inflation data and weaker employment report have already changed the policy backdrop, potentially limiting the minutes’ ability to alter expectations significantly.
In Europe, the ECB minutes will be assessed for evidence of further tightening discussions, while regional inflation releases will provide additional information about the persistence of price pressures.
OPEC+ will remain central to the energy-market outlook. The group’s production strategy, compliance discussions and delayed capacity review will be monitored alongside shipping conditions and geopolitical risks.
Elsewhere, Brazil’s election introduces uncertainty around fiscal policy and international trade relationships. Canadian employment, Norwegian inflation, Swedish CPIF and US consumer sentiment will add further detail to the assessment of regional economic conditions.
The broader picture remains mixed. Services activity has strengthened in the United States, but employment growth has weakened. Inflation has moderated in some measures, although energy and selected services components continue to present risks. Central banks therefore face a challenging balance between maintaining price stability and avoiding unnecessary pressure on economic activity.
For investors and businesses, the most useful approach is to evaluate each release within the broader economic context. Headline figures matter, but the underlying components, revisions and implications for policy expectations will ultimately determine their significance.
This Economic Report highlights the developments most likely to shape the market narrative during the week. The key question is whether incoming information confirms a gradual moderation in inflation and growth or points towards a more persistent combination of price pressures and restrictive monetary policy.