Table of Contents
- Introduction: Economic Report for October 12–16, 2026
- Economic Calendar: Key Events for October 12–16, 2026
- RBA Minutes: Australian Inflation and Interest Rate Expectations
- US Q3 Earnings Season: Banks and Corporate Profitability
- US Treasury Buyback Announcement: Liquidity and Bond-Market Conditions
- China CPI: Consumer Inflation and Producer Price Pressures
- US CPI and PPI: Inflation, Energy Costs and Federal Reserve Policy
- Australian Employment: Labour-Market Conditions and RBA Policy
- UK GDP: Assessing Economic Momentum
- US Retail Sales: Consumer Spending and Economic Growth
- European Inflation and Industrial Production
- Japanese PPI and Other Asian Developments
- US Import and Export Prices
- US Industrial Production and the Philadelphia Fed Index
- OPEC and the International Energy Agency: Oil Market Conditions
- Federal Reserve Beige Book: Regional Economic Conditions
- Global Markets: What Investors Should Monitor
- Week in Review: Key Developments Entering October 12–16
- What Investors Should Watch During the Week Ahead
- Frequently Asked Questions
- What is the most important Economic Report for October 12–16, 2026?
- Why is US CPI important to financial markets?
- What does US Retail Sales measure?
- Why are China CPI figures important?
- What are the RBA Minutes?
- How could Australian employment data affect the Australian dollar?
- Why does the start of Q3 earnings season matter?
- How can the Treasury buyback programme affect bond markets?
- What is the difference between CPI and PPI?
- Why should investors compare economic forecasts with actual results?
- Conclusion: Economic Report for October 12–16, 2026
Introduction: Economic Report for October 12–16, 2026
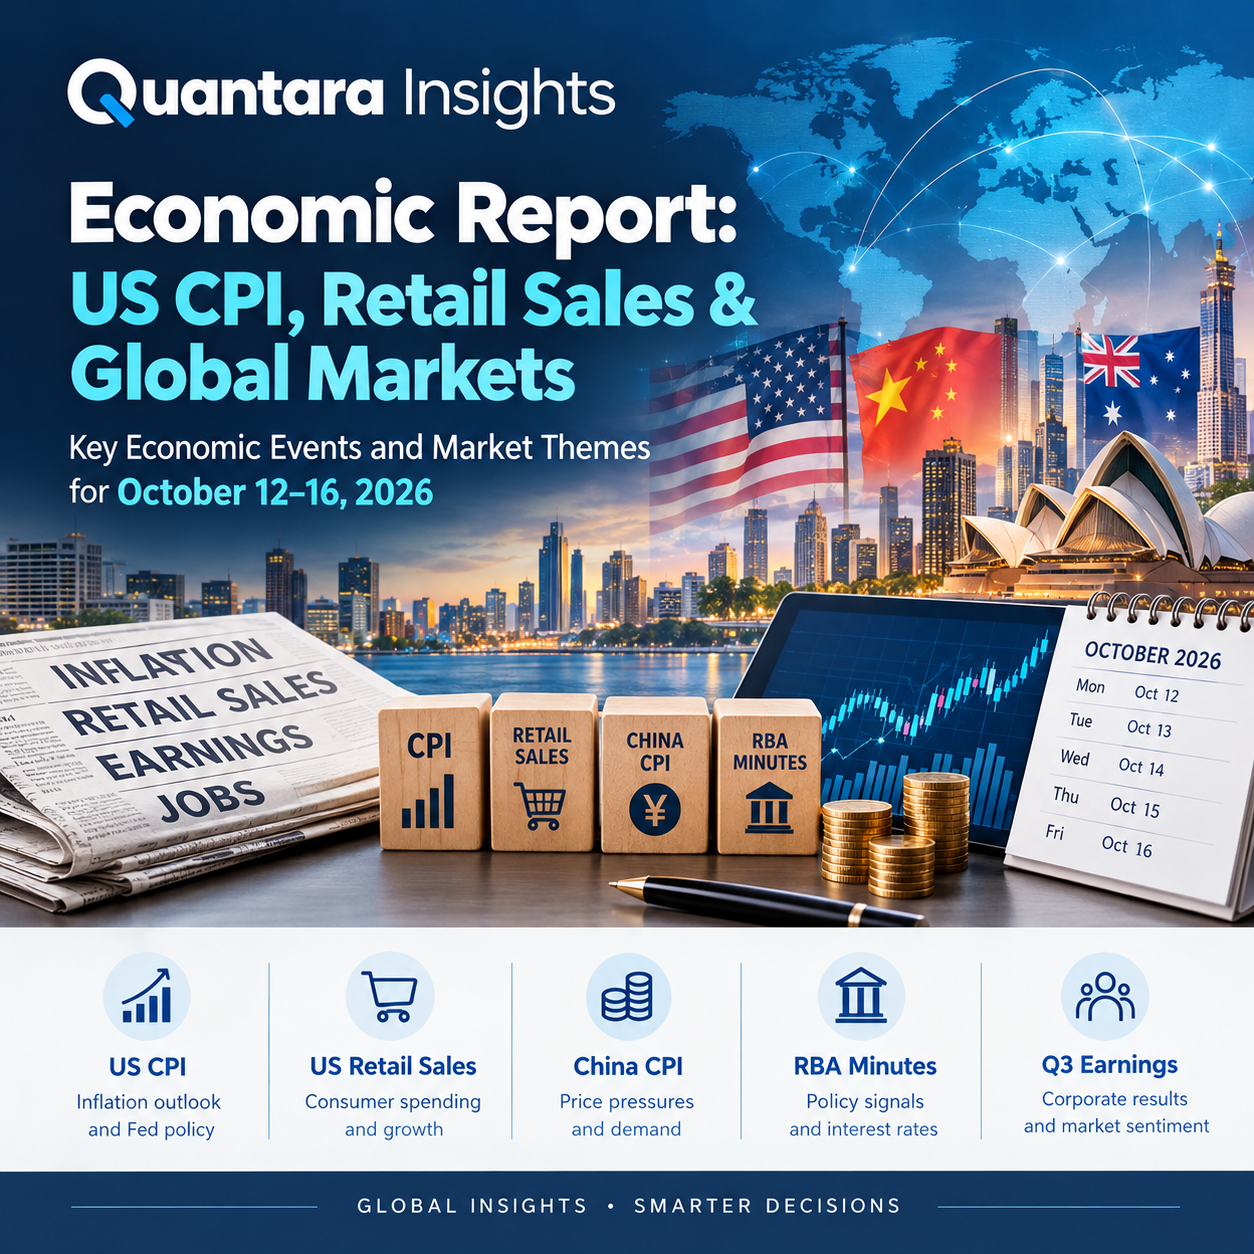
The Economic Report for October 12–16, 2026, features a concentrated series of economic releases and corporate announcements that could influence global financial markets. Investors will assess US inflation, consumer spending, Chinese price pressures, Australian employment and central-bank communications alongside the first major reports of the third-quarter earnings season.
The US Consumer Price Index (CPI) is expected to be one of the most closely watched releases. Following concerns about persistent inflation and the effect of higher energy costs, the September figures should provide additional information about the pace of consumer price increases. The US Producer Price Index (PPI), due the following day, will offer a complementary view of price pressures at the producer level.
US Retail Sales will provide another important measure of economic momentum. The report should help investors evaluate whether household spending remains resilient despite elevated living costs, fluctuating consumer confidence and uncertainty about the interest-rate outlook.
In Asia-Pacific markets, China CPI will provide an updated assessment of consumer inflation, while the Reserve Bank of Australia’s minutes should offer further insight into the Board’s assessment of inflation, economic growth and the appropriate monetary policy stance. Australia’s September employment report will add another important data point for investors monitoring the domestic labour market.
Corporate earnings will also receive considerable attention. Major US financial institutions are scheduled to begin reporting third-quarter results, providing an early indication of profitability, credit conditions, lending activity and the strength of corporate and household demand. Technology and energy companies will remain important to the wider earnings outlook.
Elsewhere, UK GDP, European industrial production, regional inflation figures, US import and export prices, and US industrial production will contribute to the week’s economic picture. The US Treasury’s planned buyback announcement will also be relevant to investors monitoring liquidity and government bond-market conditions.
The central theme of this Economic Report is the relationship between inflation, economic growth and financial conditions. Stronger activity alongside persistent inflation could complicate the outlook for central banks, while softer data might strengthen expectations for a less restrictive policy path. Corporate earnings will provide an additional test of whether company fundamentals can sustain market valuations in an environment of elevated borrowing costs.
Economic Calendar: Key Events for October 12–16, 2026
The following calendar summarises the principal releases and events scheduled for the week.
Monday, October 12
- Canadian Thanksgiving holiday.
- US markets and trading schedules may be affected by the Columbus Day federal holiday.
Tuesday, October 13
- Reserve Bank of Australia Minutes.
- OPEC Monthly Oil Market Report.
- Major US bank earnings.
- Japanese Producer Price Index for September.
- Final German CPI for September.
Wednesday, October 14
- US Treasury buyback announcement covering 10–20-year nominal securities.
- International Energy Agency Oil Market Report.
- Federal Reserve Beige Book for October.
- China CPI for September.
- German wholesale prices for September.
- Final Swedish CPI for September.
- Final Spanish CPI for September.
- US CPI for September.
Thursday, October 15
- Australian employment report for September.
- UK GDP for August.
- Final French CPI for September.
- Eurozone industrial production for August.
- US PPI for September.
- US Retail Sales for September.
- Philadelphia Federal Reserve manufacturing index for October.
Friday, October 16
- Final eurozone CPI for September.
- Final Italian CPI for September.
- US import and export prices for September.
- US industrial production for September.
The timing of releases is important because several reports will arrive in quick succession. The US CPI release on Wednesday and US PPI and Retail Sales on Thursday may produce a particularly concentrated period of market reassessment.
Investors should distinguish between the scheduled publication of a report, consensus expectations and the eventual result. Forecasts can change before release, and revisions to previous months may alter the interpretation of the latest figures.
RBA Minutes: Australian Inflation and Interest Rate Expectations
The Reserve Bank of Australia’s minutes, scheduled for Tuesday, October 13, will be an important focus for Australian dollar markets, government bonds and interest-rate expectations.
The minutes from the September policy meeting should provide additional detail on how policymakers assessed inflation risks, economic momentum and the balance between price stability and employment. Investors will examine the discussion for indications of whether the Board remains concerned about persistent inflation or sees sufficient evidence that restrictive monetary policy is beginning to moderate demand.
The minutes are particularly relevant because monetary policy decisions depend on more than the latest headline inflation rate. Policymakers also consider services inflation, wage growth, household spending, productivity, labour-market conditions and the persistence of price increases.
Inflation Remains Central to the RBA Outlook
The Reserve Bank’s policy challenge is to bring inflation sustainably towards its target while avoiding an unnecessarily sharp deterioration in economic activity.
Higher energy prices can complicate that task. Increases in fuel and electricity costs affect household purchasing power directly and can also raise business expenses across transport, manufacturing, agriculture and services. If businesses pass those costs on to consumers, the initial energy shock may become more persistent.
However, higher energy prices can also weaken real household income and reduce discretionary spending. That effect may eventually moderate demand and limit the extent to which businesses can increase prices.
The minutes should help investors understand how the Board weighs these competing effects. Particular attention is likely to fall on whether policymakers regard the latest inflation pressures as temporary or evidence of a more persistent problem.
Economic Growth and Financial Conditions
The RBA must also assess the effect of previous interest-rate decisions on borrowing costs and demand.
Higher mortgage repayments can reduce disposable income, particularly for households with substantial variable-rate debt. Businesses may also postpone investment when financing costs rise and demand becomes less certain.
These effects generally emerge gradually. As a result, policymakers must consider both current economic conditions and the likely cumulative impact of earlier policy tightening.
If the minutes indicate that financial conditions are already restrictive and economic activity is losing momentum, investors may become less confident that additional rate increases are necessary. Conversely, evidence that demand remains strong despite higher borrowing costs could reinforce expectations for a prolonged period of restrictive policy.
What the RBA Minutes Could Mean for the Australian Dollar
The Australian dollar may respond to changes in expectations for the domestic interest-rate outlook.
A more hawkish interpretation of the minutes could support the currency if investors anticipate higher Australian yields relative to those available elsewhere. A more cautious assessment of growth or inflation could have the opposite effect.
However, exchange rates also respond to global risk appetite, commodity prices, Chinese economic conditions and movements in the US dollar. The minutes should therefore be considered alongside China CPI, broader market conditions and the Australian employment report due Thursday.
The key question is whether the minutes suggest that inflation risks remain sufficiently persistent to justify additional restraint or whether policymakers believe previous measures are likely to deliver the desired result.
US Q3 Earnings Season: Banks and Corporate Profitability
The start of the US third-quarter earnings season will provide a second major theme for the Economic Report.
Analysts’ expectations point to substantial year-over-year earnings growth for S&P 500 companies. FactSet’s October 9 assessment put the current projected growth rate at approximately 29.6%, potentially marking a third consecutive quarter with earnings growth above 25%.
These estimates remain subject to change as more companies report actual results. Nevertheless, the figures indicate that investors are entering the reporting season with relatively high expectations.
The central question is whether companies can meet those expectations while managing higher input costs, elevated financing expenses and uncertainty about the strength of consumer demand.
Financial Institutions Begin Reporting
Major US banks are expected to be among the first large companies to report results. JPMorgan Chase, Goldman Sachs, Citigroup and Wells Fargo are among the institutions scheduled to report Tuesday, followed by additional major financial institutions during the week.
Their results should provide information about lending activity, net interest income, deposit costs, credit quality, trading revenue and investment banking demand.
Banks may benefit from resilient economic activity and stronger capital-markets conditions. However, the relationship between interest rates and bank profitability is complex.
Higher rates can increase returns on some loans and securities, but they can also raise deposit costs, reduce demand for borrowing and increase pressure on customers with variable-rate debt. The effect on net interest income depends on the composition of each bank’s assets and liabilities.
Investors will also monitor provisions for credit losses. An increase in loan-loss provisions could indicate that banks are preparing for weaker repayment conditions, even if current credit performance remains relatively stable.
Investment Banking and Trading Revenue
Investment banking revenue will be another important area of attention.
Underwriting, mergers and acquisitions, debt issuance and equity-market activity can be influenced by market volatility, financing costs and corporate confidence. Stronger activity in these areas could support fee income.
Trading revenue may also benefit from market movements, particularly when clients increase hedging activity or adjust portfolios in response to changes in interest-rate expectations.
However, strong market activity does not guarantee uniformly stronger earnings. Results will depend on each institution’s exposure, market share, business mix and operating costs.
Technology and Artificial Intelligence
Technology companies are expected to remain important contributors to overall earnings growth.
Demand for artificial intelligence infrastructure has supported investment in semiconductors, data centres, networking equipment and cloud computing. Companies involved in these areas may continue to report substantial revenue growth, although their performance will depend on capital expenditure, pricing, supply constraints and the ability to convert investment into sustainable profits.
Investors should distinguish between earnings growth driven by a broad improvement in business conditions and growth concentrated in a relatively small group of large technology companies.
A narrow concentration of earnings gains can support major indices while leaving other sectors less resilient. It can also increase the market’s sensitivity to disappointing results from the largest companies.
Energy Sector Earnings
Energy companies are another area of interest following the rise in oil prices during the quarter.
Higher realised prices can support revenue and profitability for producers, particularly when output remains stable and operating costs do not increase at the same pace. Analysts have projected exceptionally strong year-over-year earnings growth for the sector.
However, energy results depend on more than the headline oil price. Production volumes, refining margins, hedging arrangements, operating expenses and regional price differentials can materially affect profitability.
Investors will also consider whether current prices can be sustained. If energy prices retreat, companies may face less favourable comparisons in subsequent quarters.
Sector Differences Matter
The overall earnings outlook can conceal substantial differences between sectors.
Technology and energy may benefit from favourable industry-specific conditions, while consumer staples, healthcare, materials and other sectors face different demand and cost pressures.
Investors should examine revenue growth, earnings per share, operating margins and management guidance together. A company can beat earnings expectations because of cost reductions even when sales growth is weak. Similarly, strong revenue growth may fail to translate into higher profits if wages, financing costs or raw-material expenses increase sharply.
The quality and sustainability of earnings growth will be at least as important as the headline growth rate.
US Treasury Buyback Announcement: Liquidity and Bond-Market Conditions
The US Treasury is scheduled to announce the maximum amount it intends to purchase in the 10–20-year nominal coupon maturity sector on Wednesday, ahead of the planned operation on Thursday.
The programme is relevant to government bond-market functioning and liquidity. Treasury buybacks allow the government to repurchase eligible outstanding securities, potentially helping improve market functioning by providing a source of demand for older or less actively traded issues.
The operation should not be confused with a Federal Reserve asset-purchase programme. Treasury buybacks are part of the government’s debt-management activities and do not, by themselves, constitute a change in monetary policy.
Expected Purchase Size
The supplied market outlook notes that Treasury operations in the 10–20-year maturity sector have previously been conducted at a maximum purchase amount of approximately $6 billion, above the stated minimum guidance of $4 billion.
A similar amount may be considered, although the announcement and subsequent operation will determine the actual figure.
The amount purchased depends on the securities offered, their prices and the Treasury’s assessment of whether the offers represent attractive opportunities within the programme’s objectives.
Why Liquidity Matters
Government bond liquidity influences transaction costs, price discovery and the ability of investors to adjust positions without moving market prices excessively.
Older securities may become less actively traded as newer issues become the preferred instruments for investors seeking benchmark exposure. Buybacks can provide an additional mechanism for managing the outstanding supply of selected securities.
However, the overall effect on Treasury yields should not be assessed in isolation. Yields are also influenced by inflation expectations, anticipated Federal Reserve policy, government borrowing requirements, economic growth and demand from domestic and international investors.
Implications for Financial Markets
Investors will monitor the announcement for information about the scale of the operation and the securities eligible for purchase.
The result may influence trading in particular Treasury issues, but a broader change in government bond yields would require consideration of other market drivers.
The Treasury buyback programme is therefore best understood as one component of the wider market structure rather than a standalone signal for the direction of interest rates.
China CPI: Consumer Inflation and Producer Price Pressures
China CPI is scheduled to be released on Wednesday, October 14, providing an updated assessment of domestic price conditions.
The supplied consensus outlook anticipates that annual consumer inflation could increase to approximately 0.9%–1.0% in September, from 0.8% previously. Producer-price inflation is expected to remain elevated, with the draft forecast placing the annual PPI rate at approximately 3.8%.
These are forecasts rather than confirmed results. The actual releases will determine whether inflation is accelerating, slowing or broadly maintaining its recent pattern.
Consumer Inflation and Household Demand
China’s consumer inflation outlook is closely connected to household spending, employment confidence, food prices, energy costs and conditions in the property sector.
An increase in headline CPI could reflect higher energy prices or changes in selected food categories rather than a broad-based acceleration in domestic demand.
For this reason, investors will examine the composition of the inflation report rather than relying exclusively on the annual headline rate.
Persistently weak underlying price pressures may indicate that households remain cautious about discretionary purchases or that businesses have limited pricing power. In such circumstances, stronger headline inflation may not necessarily signal a durable recovery in domestic demand.
Producer Prices and Industrial Activity
The relationship between consumer and producer prices is another important consideration.
Higher producer prices can reflect increases in industrial input costs, commodity prices or supply constraints. Yet companies may struggle to pass those costs on to customers when demand is weak and competition remains intense.
If producer prices remain elevated while consumer inflation stays subdued, manufacturers could experience pressure on profit margins.
The extent of that pressure will vary by industry. Companies with strong pricing power may be better positioned to pass on higher costs, while firms operating in highly competitive markets may need to absorb a greater share of the increase.
Property-Sector Conditions
China’s property market remains relevant to household confidence, investment and broader economic activity.
Weak property conditions can affect construction, materials demand, household wealth perceptions and local-government finances. They may also influence decisions about major purchases and precautionary savings.
If the latest CPI data point to limited domestic demand, investors may renew their focus on the potential for additional policy support. However, a single inflation report will not determine the policy response.
Authorities must also consider growth, financial stability, employment, the exchange rate and the effectiveness of previous measures.
Market Implications of China CPI
China CPI can influence regional currencies, industrial commodities and the broader outlook for Asian markets.
Stronger-than-expected consumer inflation could be interpreted as evidence of improving demand, depending on its composition. Weaker underlying inflation may reinforce concerns about household spending and the need for additional support.
Investors should also consider the producer-price figures, credit conditions and broader indicators of industrial activity when assessing the implications for commodities and regional growth.
US CPI and PPI: Inflation, Energy Costs and Federal Reserve Policy
US CPI is likely to be the most closely watched economic release of the week.
The September report is expected to influence expectations for Federal Reserve policy, particularly because investors are assessing the persistence of inflation alongside evidence of changing labour-market conditions.
The supplied forecast anticipates a 0.6% month-over-month increase in headline CPI, compared with 0.4% previously. The annual headline rate is expected to rise to 3.6%, from 3.4%.
Core CPI, which excludes food and energy, is forecast to increase by 0.2% month over month, following a 0.3% rise previously. The annual core rate is expected to edge higher to 2.5%, from 2.4%.
These figures represent the consensus estimates included in the original market outlook and should not be treated as actual results.
Headline Inflation and Energy Prices
Energy costs are a major consideration in the September inflation outlook.
Higher petrol and other energy prices can quickly affect the headline CPI calculation. Their broader economic impact depends on how long the increases persist and whether they feed through to transportation, production, utilities and other services.
A rise in headline inflation does not automatically imply that underlying inflation is accelerating at the same rate. Investors should therefore compare headline CPI with core CPI and examine the categories responsible for the increase.
If energy accounts for most of the acceleration while core inflation moderates, the implications for monetary policy may differ from a report showing broad-based increases across services and other categories.
Core CPI and Underlying Price Pressures
Core inflation is particularly important because it can provide a clearer indication of persistent domestic price pressures.
Housing-related costs, services, insurance, medical expenses and other categories may respond differently to changes in demand and interest rates. Some components adjust gradually, making the trend over several months more informative than a single reading.
A softer monthly core CPI figure could provide reassurance that underlying price pressures are easing. However, investors would need to consider whether the improvement is broad-based and whether previous figures have been revised.
A stronger core reading could indicate that inflation remains more persistent than policymakers would prefer, especially if increases are concentrated in categories sensitive to domestic demand.
Federal Reserve Policy Expectations
The Federal Reserve faces the challenge of maintaining progress towards price stability without unnecessarily weakening employment and economic activity.
Interest-rate decisions depend on the totality of incoming information. Inflation is central to the assessment, but policymakers also consider employment, wages, financial conditions, consumer demand and the outlook for economic growth.
The supplied market outlook describes a shift in expectations following weaker employment information and comments from several Federal Reserve officials suggesting that policymakers can assess incoming data before making another move.
That context makes the September CPI release particularly important. If inflation is stronger than expected, markets may reconsider the timing and extent of potential policy easing or tightening. A softer report could reduce concerns about the need for additional restraint.
Neither outcome guarantees a specific policy decision. The Federal Reserve will continue to assess whether the data demonstrate a durable change in the inflation outlook.
US PPI: The Producer-Level Inflation Picture
The US Producer Price Index, scheduled for Thursday, will provide a complementary view of inflation.
The supplied forecast anticipates a 0.5% monthly increase in headline PPI, following a 0.4% rise previously. The annual rate is expected to ease slightly to 5.3%, from 5.4%.
Producer prices measure changes in prices received by domestic producers. They can be affected by commodity costs, transportation expenses, intermediate goods, margins and demand conditions.
Higher producer prices can place pressure on business costs, but the relationship between PPI and consumer inflation is not direct. Businesses may absorb cost increases, pass them on gradually or offset them through productivity gains and changes in profit margins.
Investors will therefore compare PPI with CPI rather than assume that one mechanically determines the other.
What to Watch in the US Inflation Reports
The most useful approach is to assess the two reports together.
Key questions include:
- Is headline inflation accelerating because of energy, or are increases broad-based?
- Is core inflation moderating consistently?
- Are services and housing-related costs continuing to put pressure on prices?
- Are producer costs rising faster than companies can absorb them?
- Does the combined evidence change expectations for Federal Reserve policy?
The answers may influence US Treasury yields, the dollar, equity valuations and interest-rate-sensitive sectors.
Australian Employment: Labour-Market Conditions and RBA Policy
Australia’s September employment report is scheduled for Thursday and will provide an important test of the domestic labour-market outlook.
The supplied consensus forecast anticipates an increase in employment of approximately 20,000, following a rise of 39,500 previously. The unemployment rate is expected to remain at 4.6%, while the participation rate is forecast to ease slightly to 67.0%, from 67.1%.
These forecasts should be distinguished from the eventual results.
Employment Growth and Labour Supply
Headline employment growth provides an important indication of demand for workers, but it must be interpreted alongside population growth, labour-force participation and hours worked.
Employment can increase while the labour market gradually loses momentum if the number of people seeking work grows more quickly than the number of available jobs.
Similarly, a slower increase in employment does not necessarily indicate a sharp deterioration. Businesses may adjust hiring gradually as demand moderates, particularly when they are reluctant to reduce staffing levels after previous recruitment difficulties.
The relationship between employment and labour supply will therefore be central to the interpretation of the September report.
The Unemployment Rate
The unemployment rate measures the proportion of the labour force that is unemployed and actively seeking work.
A stable rate of 4.6% would suggest limited month-to-month change, but the details of the report could still indicate a shift in labour-market conditions.
A higher unemployment rate could point to increasing slack, particularly if employment growth slows and the participation rate remains steady. A lower rate could indicate that labour demand remains resilient, although changes in participation can also affect the result.
Investors should also monitor full-time and part-time employment, hours worked and revisions to previous months.
Implications for the RBA
The employment report will be important for interpreting the RBA Minutes released earlier in the week.
A stronger-than-expected report could reinforce concerns that labour demand remains sufficiently firm to sustain domestic inflation pressures. A weaker report could provide evidence that financial conditions are moderating economic activity.
However, the labour market is only one part of the policy assessment. Inflation, household spending, wages, productivity and global energy prices will also influence the RBA’s decisions.
The combination of the minutes and employment report should provide a clearer picture of the Board’s priorities and the balance of risks facing the Australian economy.
UK GDP: Assessing Economic Momentum
UK GDP for August is scheduled for Thursday, adding another important data point to the European economic outlook.
The supplied forecast anticipates a month-over-month contraction of approximately 0.3%–0.4%, following stronger readings in June and July.

If realised, such a decline would indicate a loss of momentum after the preceding expansion. However, one month’s GDP estimate should not be interpreted as definitive evidence of a sustained downturn.
Services and Domestic Demand
The services sector is particularly important to the UK economy. Changes in consumer-facing activity, business services, transport and other industries can materially influence monthly GDP.
A weaker August reading may reflect a correction after stronger previous months, temporary disruptions or broader pressure on domestic demand.
Investors will want to determine whether weakness is concentrated in a small number of industries or spread across the economy.
The distinction matters because a broad-based decline would provide stronger evidence of deteriorating momentum than a temporary setback in selected sectors.
Monetary Policy Implications
The Bank of England must balance inflation risks against the outlook for economic activity.
Persistent inflation can justify restrictive policy, while weaker output and softer demand may reduce the need for additional tightening.
A weaker GDP report could complicate the policy outlook, but its influence will depend on the broader inflation and labour-market picture.
Investors should avoid assuming that one monthly contraction automatically rules out further rate increases or guarantees a more accommodative policy stance.
US Retail Sales: Consumer Spending and Economic Growth
US Retail Sales, scheduled for Thursday, will provide one of the clearest indications of how American consumers performed during September.
The supplied forecast anticipates a 0.3% month-over-month increase in headline retail sales, compared with a previous rise of 1.1%. The control-group measure is also expected to rise by 0.3%, following an increase of 1.2%.
The forecasts suggest that spending growth may moderate from the previous month’s pace while remaining positive.
Retail sales are an important measure of economic activity because household consumption represents a substantial component of US GDP. Nevertheless, the headline report must be interpreted carefully.
Nominal Sales Versus Real Spending
US Retail Sales are reported in nominal terms and are not adjusted for inflation.
This distinction is essential when assessing the strength of consumer demand.
If retail sales rise by 0.3% while prices increase substantially, the volume of goods purchased may grow more slowly or even decline. Conversely, moderate nominal sales growth can still represent a reasonable increase in real activity if prices are stable.
Investors should therefore consider the sales figures alongside CPI, energy prices and other measures of consumer demand.
The distinction between nominal and real growth is especially relevant during periods when fuel and other essential costs rise quickly.
The Control Group
The retail-sales control group is another important indicator because it excludes several categories that can be volatile or treated differently in GDP calculations.
Changes in this measure can help investors assess the underlying direction of consumer spending.
A stronger control-group reading would suggest that spending momentum extends beyond individual categories that can produce large swings in headline sales. A weaker result could indicate that the previous month’s strength was concentrated in areas less representative of broader consumption.
The composition of sales across categories will also matter.
Consumer Confidence and Actual Spending
Consumer confidence surveys can provide useful information about household perceptions, but they do not always move in line with actual expenditure.
Households may express concern about inflation, employment prospects or future economic conditions while continuing to spend on essential goods and services.
Conversely, strong confidence does not guarantee that spending will accelerate if households face higher debt repayments or have limited disposable income.
The supplied outlook notes that consumer spending indicators remained relatively solid in September, even as some confidence measures raised concerns.
That divergence makes the retail-sales report particularly useful. It can help determine whether household expenditure is maintaining its momentum or beginning to respond more clearly to financial pressures.
Energy Prices and Household Budgets
Higher petrol prices affect consumer spending in two ways.
First, they increase the amount households must spend on fuel and transportation. Second, they can reduce the money available for discretionary purchases such as dining, clothing, entertainment and household goods.
An increase in petrol spending can therefore support nominal retail-sales figures without necessarily indicating stronger underlying demand.
Investors should examine sales excluding motor vehicles and other volatile categories where possible, while recognising that fuel costs can influence a wide range of household decisions.
What Stronger or Weaker Retail Sales Could Mean
A stronger-than-expected report could reinforce the view that US consumption remains resilient. That may support expectations for economic growth, although it could also complicate the inflation outlook if demand remains strong while prices continue to rise.
A weaker report could indicate that households are becoming more cautious or that elevated costs are reducing purchasing power. However, the result should be assessed alongside employment, wages, inflation and revisions to earlier figures.
The most important issue is whether the report indicates a durable change in consumer momentum rather than a temporary monthly fluctuation.
European Inflation and Industrial Production
European data will provide additional context for the global economic outlook.
The calendar includes final inflation figures for France, Spain, Italy and the eurozone, as well as eurozone industrial production for August. German wholesale prices will offer another perspective on cost pressures earlier in the supply chain.
Final CPI Releases
Final CPI readings are important because they confirm or revise preliminary estimates and provide a more complete picture of inflation across the region.
Investors will examine whether price pressures are easing consistently across countries or whether some economies continue to experience stronger inflation than others.
Differences in energy exposure, domestic demand, wage growth and services inflation can produce divergent national outcomes.
A broadly softer inflation picture could support expectations for a less restrictive policy stance, while persistent price pressures may strengthen the case for continued caution.
However, the European Central Bank considers the eurozone-wide outlook and a range of indicators rather than relying on individual national readings.
German Wholesale Prices
Wholesale-price movements can provide information about pressures affecting businesses before some costs reach final consumers.
An increase may reflect higher commodity prices, energy expenses or changes in demand for intermediate and finished goods.
Yet wholesale inflation does not necessarily translate into an equivalent increase in consumer prices. Businesses may absorb cost changes, adjust margins or pass them on with a delay.
Investors should therefore consider the data alongside consumer inflation and industrial conditions.
Eurozone Industrial Production
Industrial production measures activity across manufacturing, mining and related industrial sectors.
The August report will help investors assess whether industrial activity is stabilising or weakening.
Manufacturers face a combination of domestic demand conditions, export demand, energy expenses, financing costs and competition from international producers.
A stronger reading could suggest improving industrial momentum, particularly if the increase is broad-based. A weaker result could point to continuing pressure on production and investment.
The sectoral composition will be important because growth in a few industries may conceal weakness elsewhere.
Japanese PPI and Other Asian Developments
Japanese PPI for September is scheduled for Tuesday and will provide an updated measure of price pressures facing domestic producers.
Producer prices are influenced by imported energy, raw materials, exchange-rate movements and domestic demand. Japan’s dependence on imported commodities means that changes in global prices and the yen can have a meaningful effect on business costs.
Higher producer inflation does not necessarily lead to an equivalent increase in consumer inflation. The extent of pass-through depends on demand conditions, competition, corporate margins and the pricing decisions of individual companies.
Investors will assess the figures alongside Japan’s broader inflation outlook and expectations for Bank of Japan policy.
More generally, Asian markets will remain sensitive to China CPI, global energy prices and developments in US monetary policy. These factors can influence regional currencies, commodity demand and capital flows.
US Import and Export Prices
The US import and export price indexes, scheduled for Friday, will provide additional information about international price pressures.
Import prices are affected by foreign production costs, transportation expenses, commodity prices and exchange-rate movements. Export prices provide information about the prices US producers receive for goods sold abroad.
Higher import prices can increase costs for businesses and households, especially when the increases affect energy, industrial inputs or widely used consumer goods.
However, the relationship between import prices and consumer inflation is not automatic. Businesses may change suppliers, absorb costs or adjust their pricing strategies.
Export prices also matter because they can influence the competitiveness of US goods in international markets.
Investors will consider whether the figures indicate that external price pressures are strengthening or easing, particularly after the CPI and PPI releases earlier in the week.
US Industrial Production and the Philadelphia Fed Index
US industrial production and the Philadelphia Federal Reserve manufacturing index will help investors assess conditions in the manufacturing sector.
Industrial production provides a broad measure of output, while the Philadelphia Fed survey offers a regional perspective on manufacturing conditions and business expectations.
Industrial Production
Changes in industrial production can reflect shifts in manufacturing demand, utility output, mining activity and other industrial operations.
A stronger reading may indicate improving production conditions, although the details will determine whether the increase reflects broad-based demand or a temporary rise in selected industries.
A weaker reading may suggest that businesses are adjusting output to slower demand or higher operating costs.
Industrial production should also be considered alongside new orders, inventories and capacity utilisation to assess whether changes in output are likely to persist.
Philadelphia Fed Manufacturing Index
The Philadelphia Fed index is a survey-based indicator that can provide timely information about manufacturing activity.
Investors will examine indicators related to new orders, shipments, employment, prices and business expectations.
A stronger survey could suggest improving regional activity, while weaker readings may indicate that manufacturers remain cautious about demand and costs.
Price components will be particularly relevant following the US CPI and PPI releases. If manufacturing firms report rising input prices alongside stronger activity, the combination could complicate the assessment of inflation and growth.
OPEC and the International Energy Agency: Oil Market Conditions
Energy-market reports from OPEC and the International Energy Agency will provide additional context for the inflation outlook.
Oil prices influence headline inflation directly through fuel costs and indirectly through transportation, logistics, manufacturing and other energy-intensive activities.
The relationship between production targets and actual supply is important. Announced quotas do not necessarily translate into equivalent changes in physical output, because individual producers may operate below their allocations or face operational constraints.
Investors will monitor production estimates, demand forecasts, inventories and regional supply disruptions.
The supplied outlook describes OPEC+ as maintaining November production targets for a second consecutive month after completing the rollback of voluntary cuts in September. It also notes that the assessment of production capacity relevant to 2027 quotas has been delayed until mid-November.
These developments should be considered alongside actual production, exports and demand conditions rather than interpreted solely through headline quota announcements.
The International Energy Agency’s oil market assessment may provide a complementary view of global demand, supply and inventory trends.
For financial markets, the main question is whether energy prices are likely to remain elevated or begin to ease. Sustained increases could reinforce inflation concerns, while a decline could reduce some pressure on household budgets and business costs.
Federal Reserve Beige Book: Regional Economic Conditions
The Federal Reserve Beige Book, scheduled for Wednesday, will provide qualitative information about economic activity across the twelve Federal Reserve districts.
Unlike CPI or Retail Sales, the Beige Book is not a single statistical measure. It compiles information gathered from businesses, contacts and regional sources about economic conditions.
Investors will look for evidence concerning consumer demand, hiring, wages, business investment, pricing behaviour and credit conditions.
Employment and Business Activity
Comments about hiring plans and worker availability can help investors assess whether labour demand is cooling.
Businesses may report slower recruitment, reduced turnover or more selective hiring even before those changes become fully visible in national employment statistics.
Similarly, comments about consumer demand can help explain whether spending is holding up across industries or becoming concentrated in essential goods and services.
Pricing and Costs
The Beige Book can also provide insight into how businesses are responding to higher costs.
Some firms may report passing through increases in wages, energy or raw materials, while others may describe pressure on margins because customers resist higher prices.
This qualitative information can complement the CPI and PPI reports by helping investors understand the mechanisms behind price changes.
However, anecdotal reports should be considered alongside the quantitative data rather than treated as a substitute for it.
Global Markets: What Investors Should Monitor
The week’s economic releases could affect several major asset classes, although the market response will depend on how the results compare with expectations and what investors have already priced in.
Foreign Exchange
Currency markets will focus on changes in relative interest-rate expectations.
Stronger US inflation could support the dollar if investors anticipate a more restrictive Federal Reserve policy outlook. Softer inflation could have the opposite effect, depending on other economic developments.
The Australian dollar may respond to the RBA Minutes, Australian employment data and China CPI. These releases influence perceptions of Australian monetary policy and the region’s economic outlook.
Currency movements will also depend on risk appetite, commodity prices and developments in other major economies.
Government Bonds
US Treasury yields may react to CPI, PPI, Retail Sales and the Beige Book.
Stronger inflation or resilient demand could lead investors to reassess the expected path of interest rates. Weaker data may support lower yields if markets anticipate less monetary restraint.
However, yields also reflect expectations for economic growth, government borrowing, term premiums and demand for safe assets.
The Treasury buyback announcement may influence particular securities, but its effect should be distinguished from the broader forces determining the yield curve.
Equities
Equity markets will weigh economic data against corporate earnings expectations.
Stronger activity can support revenue growth, but persistent inflation may raise borrowing costs and place pressure on valuation multiples.
Weaker data can reduce interest-rate concerns, but an abrupt deterioration in demand may threaten earnings.
The reaction will therefore depend on the balance between growth, inflation and profitability rather than whether an individual release is simply stronger or weaker than expected.
Commodities
Energy prices will remain relevant because they affect inflation, industrial costs and household purchasing power.
China CPI and the broader Chinese economic outlook may also influence sentiment towards industrial commodities.
Investors should monitor actual supply and demand conditions alongside production announcements, inventory data and geopolitical developments.
Week in Review: Key Developments Entering October 12–16
The previous week’s developments provide useful context for the coming data releases.
Brazil’s Presidential Election
The supplied market review reports that Senator Flávio Bolsonaro led Brazil’s first-round presidential election with 47.03% of the vote, ahead of incumbent President Luiz Inácio Lula da Silva at 45.16%, setting up a runoff scheduled for October 25.
It also notes that Brazilian assets strengthened following the result as investors assessed the potential implications for fiscal policy and the country’s economic outlook.
Political developments can influence currencies, bond yields and equities through expectations about taxation, public spending, regulation and debt sustainability.
However, election-related market moves do not establish the direction of future policy. Investors will need to assess campaign commitments, legislative constraints and the eventual policy programme before drawing longer-term conclusions.
OPEC+ Production Policy
The supplied review states that OPEC+ maintained its November production targets, marking a second consecutive month without further output increases after completing the rollback of voluntary cuts in September.
The distinction between production targets and actual output remains important. Physical supply can differ from announced quotas because of operational constraints, export disruptions and differences in national production capacity.
The next phase of the production-capacity assessment will be relevant to the longer-term allocation of quotas and the outlook for global supply.
US Services Activity
The September ISM Services PMI declined to 54.9 from 55.4 in August, according to the supplied review. The reading remained above 50, indicating expansion, although the pace moderated.
Business activity and new orders both eased, while the prices index increased to 74.0 from 72.6. The employment index returned to expansionary territory at 50.1.
The combination of continued expansion and elevated input-price pressure suggests that the services sector may remain a source of resilience and inflation risk.
For the coming week, these details will be relevant when assessing CPI, Retail Sales and the Federal Reserve’s qualitative assessment of regional economic conditions.
Federal Reserve Meeting Minutes
The supplied review describes broad support among policymakers for the September rate increase and notes that participants continued to view inflation as elevated.
It also reports discussion of Treasury yields, financial conditions, geopolitical uncertainty and financing needs associated with investment in artificial intelligence infrastructure.
These issues illustrate the range of factors influencing the broader policy environment. Monetary policy expectations are important, but longer-term bond yields can also respond to government borrowing, private investment demand and changes in the compensation investors require for holding duration risk.
The latest CPI release will help determine whether the inflation outlook has changed enough to alter market expectations.
Reserve Bank of India
The supplied review reports that the Reserve Bank of India increased its repo rate by 25 basis points to 5.50% and adopted a more restrictive policy stance.
It also notes that the central bank raised its inflation forecast while increasing its real GDP growth forecast.
These developments highlight the challenges faced by central banks when economic activity remains firm but inflation risks increase.
The policy implications for India differ from those for Australia or the United States, but the broader issue is similar: policymakers must determine how much restraint is necessary to bring inflation under control without imposing unnecessary costs on economic growth.
European Central Bank and Swedish Inflation
The supplied review describes a hawkish tone in the ECB minutes, while noting that policymakers continued to emphasise a data-dependent approach.
It also reports Swedish inflation readings that were broadly consistent with the Riksbank’s forecast for headline CPIF, while core CPIF was below the Bank’s projection.
These developments underline the importance of distinguishing between headline inflation and underlying price pressures. A central bank may respond differently to a temporary energy-driven increase than to persistent inflation across domestic services and wages.
The coming European inflation releases should help investors assess whether these pressures are becoming more consistent across the region.
Canadian Employment
The supplied review reports that Canadian employment declined by 68,300, well below the anticipated increase of 7,000, while the unemployment rate rose to 6.5%.
If confirmed in the reported data, the result would point to further labour-market weakness and could influence expectations for Bank of Canada policy.
However, the policy outlook remains sensitive to inflation risks, trade conditions and developments in energy markets.
This is another example of why central-bank expectations cannot be inferred from employment data alone.
What Investors Should Watch During the Week Ahead
The October 12–16 calendar contains several reports that may reinforce or contradict one another. Investors should therefore evaluate the information collectively.
1. The Direction of US Inflation
The most important question is whether US CPI indicates that price pressures are becoming more persistent or beginning to moderate.
Headline inflation, core inflation and the composition of monthly changes will help determine whether energy prices are driving the result or whether increases are spreading across the economy.
PPI will provide a further indication of business cost pressures.
2. The Resilience of US Consumers
US Retail Sales will help investors assess whether consumer demand remains firm despite higher living costs and financing expenses.
The control group, sales excluding volatile categories and the distinction between nominal and real spending will be particularly relevant.
3. Australian Monetary Policy
The RBA Minutes and employment report will provide complementary information about inflation risks and labour-market conditions.
A strong labour market combined with persistent inflation could support a restrictive policy outlook. Softer employment alongside evidence of moderating inflation could provide more room for policymakers to assess the effects of previous decisions.
4. Chinese Demand and Inflation
China CPI will help investors assess whether domestic price pressures are strengthening and whether household demand is showing signs of improvement.
Producer prices, property-sector conditions and wider indicators of industrial activity will remain important to the interpretation.
5. Corporate Earnings Quality
The first major bank reports will provide information about lending, credit quality, trading revenue and corporate demand.
Investors should assess whether earnings growth reflects sustainable business activity, improved margins or temporary factors.
Technology and energy results will also be important, particularly given their contribution to current earnings expectations.
6. Bond Yields and Financial Conditions
US Treasury yields may respond to inflation and activity data, while the buyback announcement may affect trading in specific securities.
Investors should distinguish between changes in short-term policy expectations and movements in longer-term yields caused by supply, demand and term premiums.
7. Energy Prices and Global Risk
Oil prices will remain a cross-market variable because they influence inflation, corporate costs, consumer budgets and commodity-linked currencies.
The OPEC and IEA reports may help investors assess the balance between supply and demand, although actual market conditions will remain decisive.
Frequently Asked Questions
What is the most important Economic Report for October 12–16, 2026?
US CPI is likely to be one of the most important releases because it provides updated information about inflation and can influence expectations for Federal Reserve policy. US Retail Sales, US PPI, the RBA Minutes and Australian employment data are also significant.
Why is US CPI important to financial markets?
US CPI measures changes in consumer prices and helps investors assess inflation trends. The report can influence interest-rate expectations, government bond yields, the US dollar and equity valuations.
What does US Retail Sales measure?
US Retail Sales measures the value of sales at retail businesses and food-service establishments. The report is expressed in nominal terms, so it does not directly measure inflation-adjusted spending.
Why are China CPI figures important?
China CPI provides information about consumer price pressures and domestic demand. It can influence expectations for Chinese economic policy, regional growth and sentiment towards commodities and Asian currencies.
What are the RBA Minutes?
The RBA Minutes summarise the discussion surrounding a monetary policy meeting. They help investors understand policymakers’ assessment of inflation, economic growth, employment and the risks influencing future interest-rate decisions.
How could Australian employment data affect the Australian dollar?
Stronger employment may reinforce expectations for a restrictive RBA policy stance, potentially supporting the Australian dollar. Weaker employment could have the opposite effect. Currency movements also depend on global risk sentiment, commodity prices and US dollar performance.
Why does the start of Q3 earnings season matter?
Corporate earnings provide evidence about company profitability, revenue growth and management expectations. Results from major banks offer an early indication of credit conditions and financial activity, while technology and energy results may influence broader index performance.
How can the Treasury buyback programme affect bond markets?
Treasury buybacks can support market functioning by providing demand for eligible outstanding securities. Their effects on individual bonds may differ from broader movements in Treasury yields, which also depend on inflation, monetary policy and government borrowing.
What is the difference between CPI and PPI?
CPI measures changes in prices paid by consumers for goods and services. PPI measures changes in prices received by domestic producers. The two indexes provide different perspectives on inflation and do not necessarily move in parallel.
Why should investors compare economic forecasts with actual results?
Markets frequently respond to the difference between reported results and expectations rather than the absolute figure alone. Revisions, the composition of the data and the implications for future policy can also affect the market response.
Conclusion: Economic Report for October 12–16, 2026
The Economic Report for October 12–16, 2026, brings together a broad range of inflation, employment, consumption and corporate earnings indicators.
US CPI and PPI will be central to the assessment of inflation and the Federal Reserve’s policy outlook. US Retail Sales will provide information about consumer demand, while China CPI will help investors assess price pressures and economic conditions in the world’s second-largest economy.
The RBA Minutes and Australian employment report will be important for understanding the outlook for Australian monetary policy. UK GDP, European inflation and industrial production will add context to regional growth conditions, while the US Treasury buyback announcement will be relevant to government bond-market liquidity.
Meanwhile, the start of the US third-quarter earnings season will test expectations for corporate profitability. Results from major banks, technology companies and energy producers should provide valuable information about the resilience of business activity, credit conditions and sector-specific growth.
The week’s releases should be interpreted as a connected set of indicators rather than isolated market events. Stronger activity may support earnings and growth expectations, but persistent inflation could complicate the policy outlook. Softer inflation may improve the outlook for financial conditions, although weaker demand could present challenges for corporate revenue.
For investors, the priority is to assess whether incoming data confirm or challenge existing expectations. The interaction between inflation, growth, central-bank policy and earnings will remain central to the direction of global financial markets as October progresses.